


Snowflake Inc Stock (SNOW) Moved Down by 3.56% on Sep 15: Drivers Behind the Movement



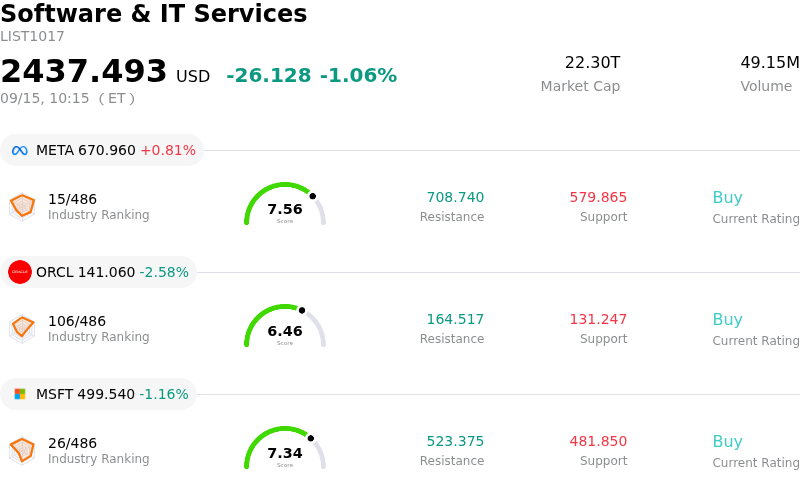
Snowflake Inc (SNOW) moved down by 3.56%. The Software & IT Services sector is down by 1.06%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Meta Platforms Inc (META) up 0.45%; Oracle Corp (ORCL) down 2.58%; Microsoft Corp (MSFT) down 1.15%.
What is driving Snowflake Inc (SNOW)’s stock price down today?
Snowflake experienced downward momentum as high-valuation enterprise software and cloud infrastructure stocks faced broader market pressure. Following a strong rally earlier in the month driven by second-quarter financial results and an upgraded full-year outlook, the stock reached stretched valuation multiples. With interest rate sensitivity and macroeconomic caution mounting ahead of upcoming central bank policy decisions, investors reassessed elevated valuation premiums across high-growth technology names, prompting a shift toward risk mitigation.
Beyond macroeconomic headwinds, company-specific dynamics contributed to the selling pressure. Although Snowflake recently demonstrated accelerating product revenue and increased client adoption for its artificial intelligence tools, independent analysts and market commentators have raised concerns over the widening gap between the company's market price and fundamental fair value estimates. Persistent GAAP operating losses, substantial stock-based compensation expenses, and a slight lag in billings relative to total revenue growth have kept long-term profitability under scrutiny.
Furthermore, profit-taking activity naturally intensified after the stock recorded significant multi-month gains leading into mid-September. Recent regulatory disclosures regarding insider stock transactions also contributed to cautious short-term sentiment. As momentum traders lock in profits from the post-earnings surge, Snowflake remains exposed to intraday volatility, where minor shifts in market sentiment can trigger pullbacks in richly valued cloud platforms.
Technical Analysis of Snowflake Inc (SNOW)
Technically, Snowflake Inc (SNOW) shows a MACD (12,26,9) value of -4.740, indicating a neutral signal. The RSI at 49.457 suggests neutral condition and the Williams %R at 79.212 suggests sell condition. Please monitor closely.
Fundamental Analysis of Snowflake Inc (SNOW)
Snowflake Inc (SNOW) is in the Software & IT Services industry. Its latest annual revenue is $4.68B, ranking 69 in the industry. The net profit is $-1.33B, ranking 605 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $425.29, a high of $525.00, and a low of $110.00.
More details about Snowflake Inc (SNOW)
Company Specific Risks:
- Gross Margin Compression from AI Expansion: Management lowered full-year product gross margin guidance to 74% as a strategic shift to prioritize rapid adoption of compute-heavy AI features, such as Cortex AI, increases infrastructure cost overhead and compresses unit margins despite revenue growth.
- Valuation Multiples Vulnerable to Interest Rate Volatility: Trading at elevated multiples exceeding 23x forward sales, Snowflake exhibits high intraday sensitivity to macroeconomic shifts and Federal Reserve rate decisions, leaving the stock prone to sharp pullbacks if growth or discount rate assumptions fluctuate.
- Persistent GAAP Losses and Stock-Based Compensation Overhead: Despite reporting non-GAAP profitability, Snowflake continues to generate significant GAAP net losses ($191.7 million in recent quarterly filings), burdened by heavy stock-based compensation and large executive equity incentive packages that weigh on real shareholder return.
- Competitive Pressures and AI Consumption Conversion Risks: Intensifying competition from cloud infrastructure rivals like Databricks, alongside enterprise risks that early AI experimentation may not fully convert into high-volume paid consumption credits, threatens long-term platform burn rates and revenue retention.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.