


Marvell Technology Inc Stock (MRVL) Moved Down by 6.12% on Sep 14: A Full Analysis



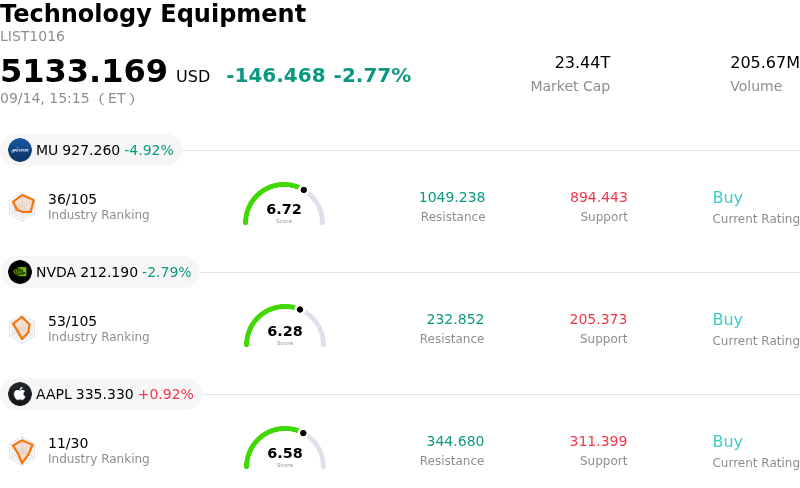
Marvell Technology Inc (MRVL) moved down by 6.12%. The Technology Equipment sector is down by 2.77%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) down 4.89%; NVIDIA Corp (NVDA) down 2.76%; Apple Inc (AAPL) up 0.89%.
What is driving Marvell Technology Inc (MRVL)’s stock price down today?
Marvell Technology experienced significant downward pressure as part of a broader sell-off across the semiconductor and artificial intelligence hardware space. The primary catalyst driving the pull-back was heightened market concern surrounding the near-term trajectory of AI infrastructure capital expenditure. Public comments from key leaders at prominent AI research organizations, calling for a more cautious pace of frontier model deployment to address safety and regulatory considerations, sparked fears that hyperscalers could temporarily moderate the rapid expansion of their data center buildouts. Given Marvell's heavy revenue exposure to data center networking, custom silicon, and optical interconnects, the stock was particularly sensitive to shifts in sentiment regarding infrastructure deployment timelines.
The broader macroeconomic backdrop further compounded sector-specific pressure. Heightened investor caution ahead of key Federal Reserve monetary policy deliberations and renewed focus on interest rate outlooks weighed heavily on high-multiple growth equities. Semiconductor companies whose valuations heavily discount long-dated future cash flows faced notable multiple contraction. After strong previous performance driven by expanding AI design wins and elevated multi-year revenue projections, Marvell faced targeted institutional profit-taking as investors reduced risk exposure across higher-duration technology names.
Despite the short-term pressure driven by macro and sector sentiment, Marvell's underlying business drivers remain anchored in key structural technology trends. The company continues to capture custom application-specific integrated circuit design wins and expand its footprint in high-speed optical switching across major cloud providers. Near-term price movement will likely remain sensitive to broader industry capital spending commentary and policy signaling, with investors closely watching upcoming technology conferences and corporate investor events for further clarity on cloud infrastructure demand.
Technical Analysis of Marvell Technology Inc (MRVL)
Technically, Marvell Technology Inc (MRVL) shows a MACD (12,26,9) value of 0.416, indicating a buy signal. The RSI at 49.391 suggests neutral condition and the Williams %R at 60.448 suggests sell condition. Please monitor closely.
Media Coverage of Marvell Technology Inc (MRVL)
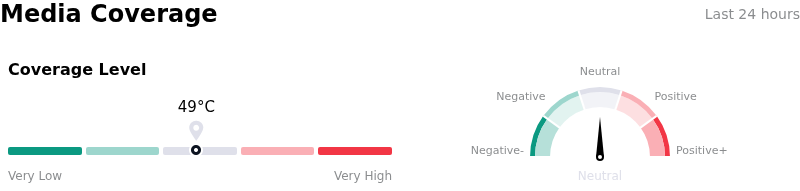
In terms of media coverage, Marvell Technology Inc (MRVL) shows a coverage score of 49, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Marvell Technology Inc (MRVL)
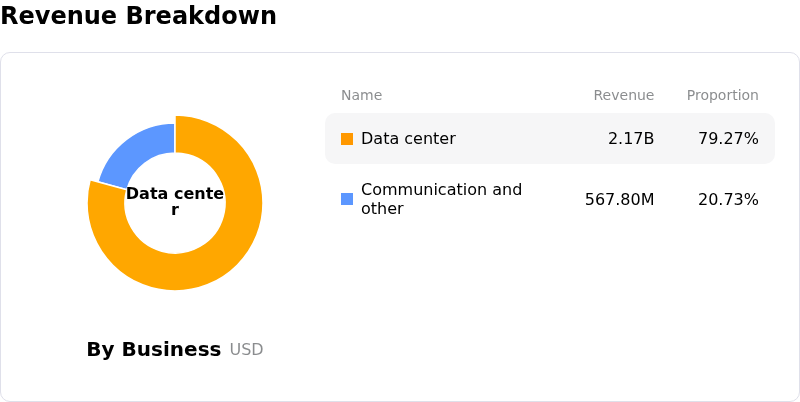
Marvell Technology Inc (MRVL) is in the Technology Equipment industry. Its latest annual revenue is $8.19B, ranking 19 in the industry. The net profit is $2.67B, ranking 13 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $280.29, a high of $400.00, and a low of $90.00.
More details about Marvell Technology Inc (MRVL)
Company Specific Risks:
- Sensitivity to AI Capital Expenditure Slowdown: Following industry commentary urging a moderation in AI development velocity, market sentiment has shifted, exposing Marvell's heavy reliance on hyperscaler data center buildouts to severe revenue volatility if key customers scale back infrastructure investments.
- Elevated Valuation and Cash Flow Duration Sensitivity: Marvell trades at a premium valuation of nearly 22x sales and over 78x earnings, leaving its stock highly susceptible to sharp multiple contractions when market discount rates adjust or long-term cash flow projections are questioned.
- Gross Margin Dilution from Custom ASIC Revenue Mix: Institutional commentary from recent industry conferences highlighted that Marvell's rapidly expanding custom silicon business carries lower gross margins than its traditional high-margin networking products, threatening to compress overall profit margins as custom chips become a larger share of revenue.
- Supply Chain Constraints and Competitive Pressure: To meet aggressive long-term revenue targets, Marvell faces ongoing supply chain constraints and high capital commitments for advanced foundry capacity, while competing directly against dominant rivals like Broadcom for key hyperscaler custom chip wins.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.