


Vertiv Jumps Over 15% Pre-Market: Q3 Orders Surge Over 100%, AI Data Center Demand Supports Growth Expectations



AI Podcast


As of October 28 US Eastern Time, Vertiv surged 15.62% in pre-market trading to $241.14 following robust third-quarter results. Net sales grew 61% year-over-year to $4.313 billion, and organic orders doubled, driven by strong data center infrastructure demand. Adjusted EPS reached $2.21, with the operating margin expanding to 25.2%. Consequently, the company raised its full-year 2026 net sales guidance to $14.45 billion–$14.85 billion and projected persistent AI-driven demand into 2027. However, future performance remains contingent on customer capital expenditures, order fulfillment, and capacity expansion.
TradingKey - As of press time on October 28 US Eastern Time, data center infrastructure provider Vertiv (VRT) rose 15.62% in pre-market trading to $241.14.
The company's third-quarter net sales grew 61% year-over-year to $4.313 billion, with organic orders up more than 100% year-over-year, and it raised its full-year 2026 guidance.
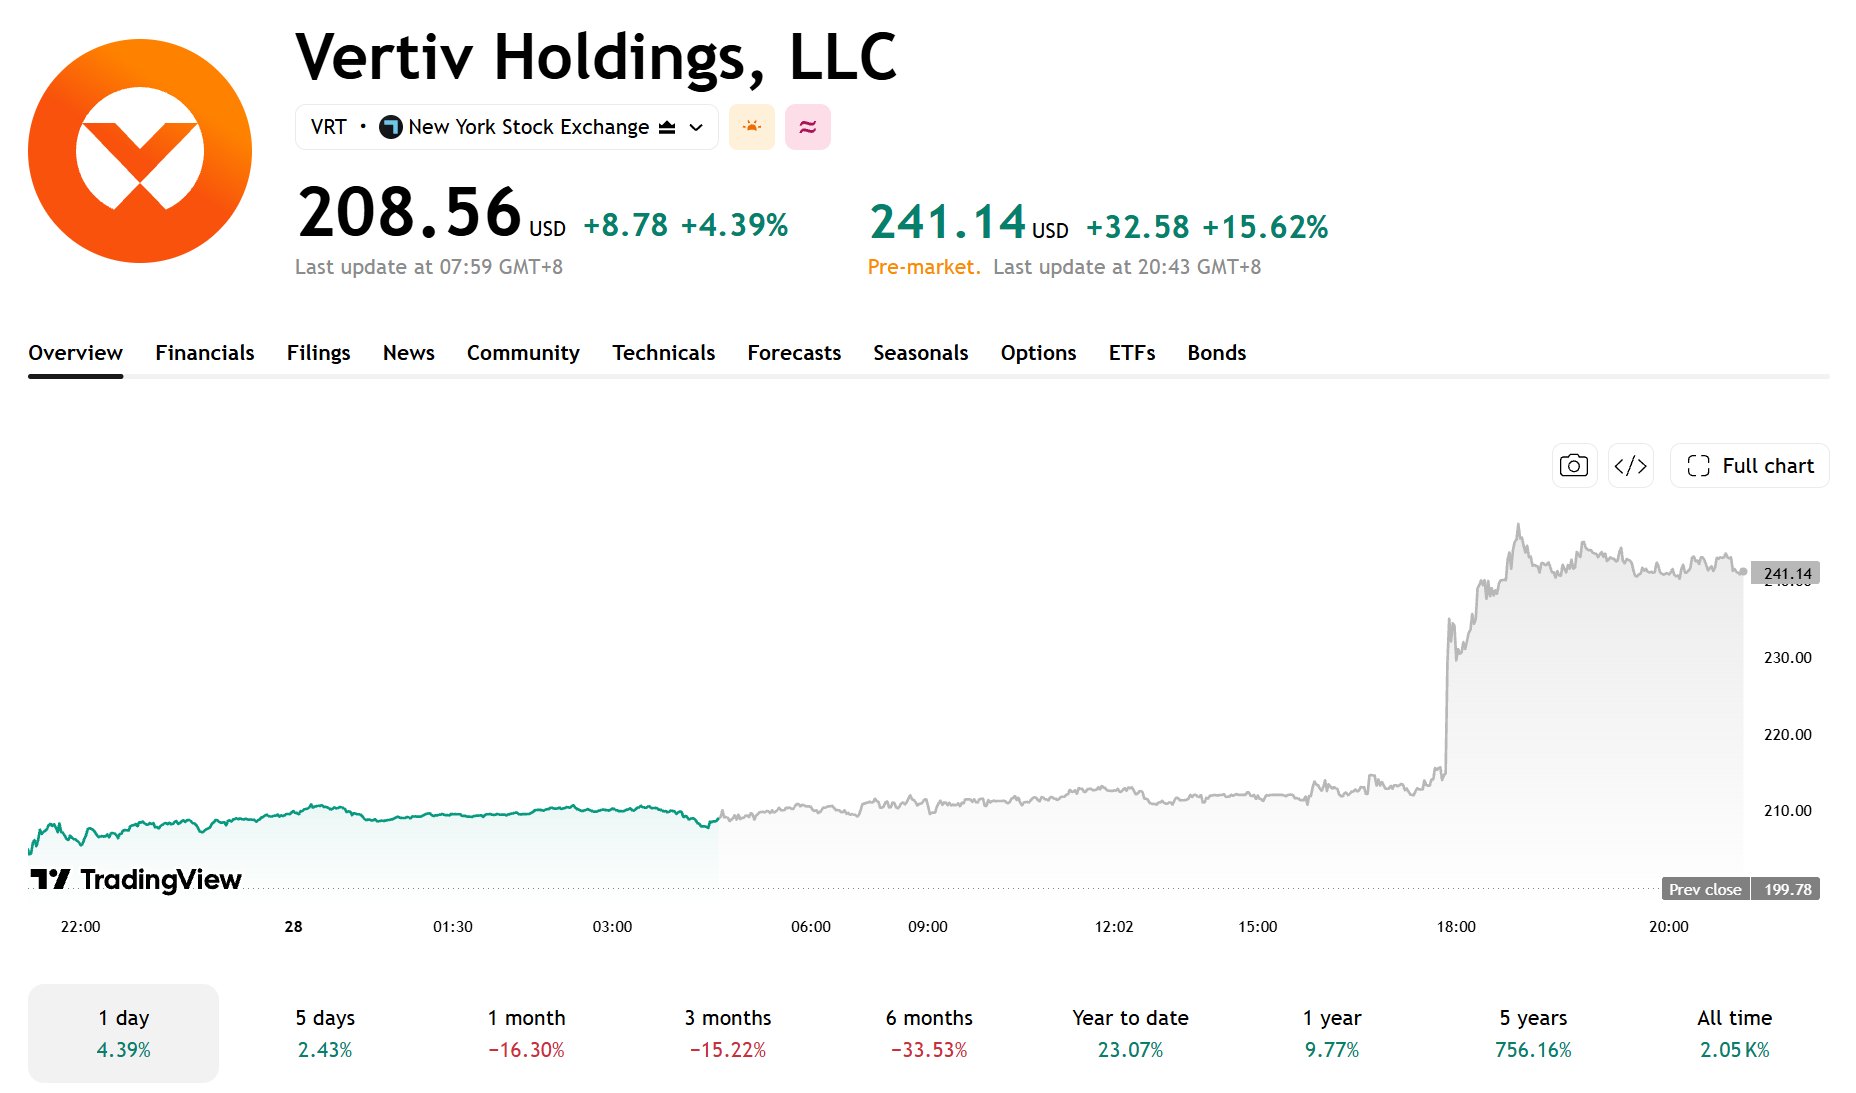
[Source: TradingView]
Q3 Revenue Grows 61%, Organic Orders Jump Over 100%
The financial report showed that Vertiv's third-quarter net sales grew 61% year-over-year to $4.313 billion, while adjusted earnings per share reached $2.21, up 78% year-over-year.
During the same period, the company's organic sales increased 55%, overall organic orders surged by more than 100% year-over-year, and the adjusted operating margin rose to 25.2%, up 2.9 percentage points year-over-year.
Vertiv primarily provides power supply, power distribution, and thermal management equipment for data centers. Driven by growing demand for data center infrastructure, both sales and orders increased significantly. Future performance will remain dependent on factors such as order fulfillment, customer demand, and capacity expansion.
Raises Full-Year Guidance, Expects Demand to Remain Strong in 2027
Vertiv raised its full-year 2026 net sales guidance to $14.45 billion to $14.85 billion, with the midpoint up $650 million from its prior forecast; full-year adjusted EPS is projected at $7.10 to $7.20.
Looking ahead to 2027, the company expects AI-driven data center demand to remain strong and is optimistic about organic sales growth. Whether future performance meets expectations remains dependent on customer capital expenditures, order delivery progress, and margin performance.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.