


Apple FQ4 Preview | iPhone Sales Expected to Rise About 7%; Services Sales Might Increase 13%


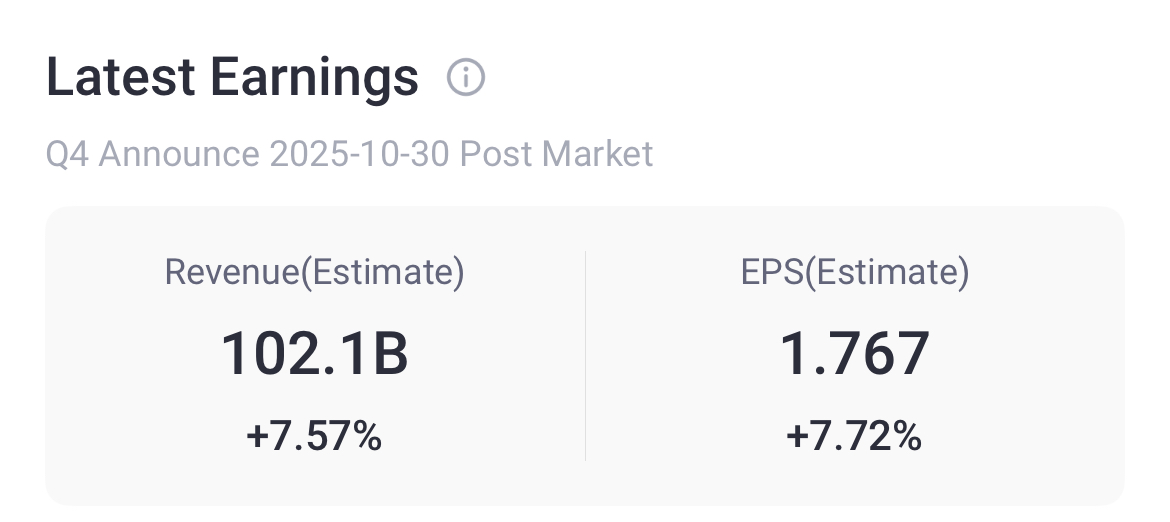
Apple is set to release its Fiscal Q4 2025 results on Oct. 30 after the US market closes. Apple's Q4 revenue is expected to be $102.1 billion, up 7.57% year-on-year. Earnings per share is expected to grow 7.72% YoY to $1.767, according to data from Tiger Trade App.
 Source: Tiger Trade App
Three Things to Watch in F4Q
iPhone Sales Expected to Rise About 7%
Apple's fiscal 4Q results could ease investor fears about the company losing smartphone market share in China amid reports that the reception for iPhone 17 has been strong in the region, with Counterpoint data suggesting a 14% increase in initial iPhone 17 sales vs. last year.
However, US smartphone survey suggests muted interest by consumers to upgrade their iPhones. Consequently, it's reasonable to expect iPhone sales to rise about 6%-7% in 4Q.
Product sales could rise 5%, compared with a 4% gain in 2024, as a 7% increase in iPhone revenue offsets flat iPad growth and a decline in Wearables, Home, and Accessories.
Services Sales Might Increase 13% to $28.2 Billion
Management indicated September quarter Services growth would be similar to June, at roughly 13% y/y, above the 12% gain a year earlier.
Apple's Services segment now drives nearly a third of revenue, with gross margin near 75%, supporting stable company-wide margins of 46–47% or better. For Q1 FY26 guidance, services should stay in the low- to mid-teens range and remain the main buffer against EPS volatility.
Apple Navigates Tariff Pressures With Favorable Product Mix
Tariff-related costs for 1Q will likely be another big factor, with calculations suggesting about $1.3 billion in 4Q and close to $2 billion in 1Q. We expect Apple to offset this from a greater mix shift to services as well as higher-priced products such as the Pro models, keeping operating margin growth flat to slightly down through 1Q.
Gross margins are projected at 46.6% for Q4 and 47% for Q1, as a favorable product mix is seen offsetting possible rises in "memory input costs". Adding that key future catalysts include the approval of Apple Intelligence in China and the expected 2026 launches of advanced Siri and foldable devices.
Operating margin is expected to narrow by about 10 basis points to 31.1%, reflecting increased R&D spending relative to sales.
Analysts' Opinions
Morgan Stanley said Apple is expected to surpass Wall Street expectations when it reports fiscal Q4 results on the back of stronger-than-anticipated iPhone 17 demand and continued strength in its Services business. Morgan Stanley reiterated an overweight rating on the stock with a $298 price target.
Evercore said Apple is best positioned heading into earnings on October 30.
“We believe AAPL is well positioned to report upside to upside to current Sep-qtr consensus expectations and could guide to upside for the Dec-qtr. Our positive bias is driven by iPhone data points that suggest this may be more than the average iPhone refresh cycle, as lead times for the base iPhone 17 are above last year’s October levels.”
KeyBanc Capital Markets analyst Brandon Nispel said Apple’s hardware metrics were solid but not enough to justify the valuation.
“With AAPL trading at all-time highs, we see the stock as expensive and pricing in lofty expectations though we are lacking a bear case,” Nispel wrote in a note to clients.
Wedbush analyst Dan Ives said, "With Apple on the doorstep of joining the $4 trillion market cap club, it’s clear that Cook & Co. have a hit with iPhone 17. Now it’s the AI roadmap."
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.