


Amazon Q3 Earnings Preview: AWS Expansion and AI's Role in Boosting Profitability in a Competitive Market in Focus


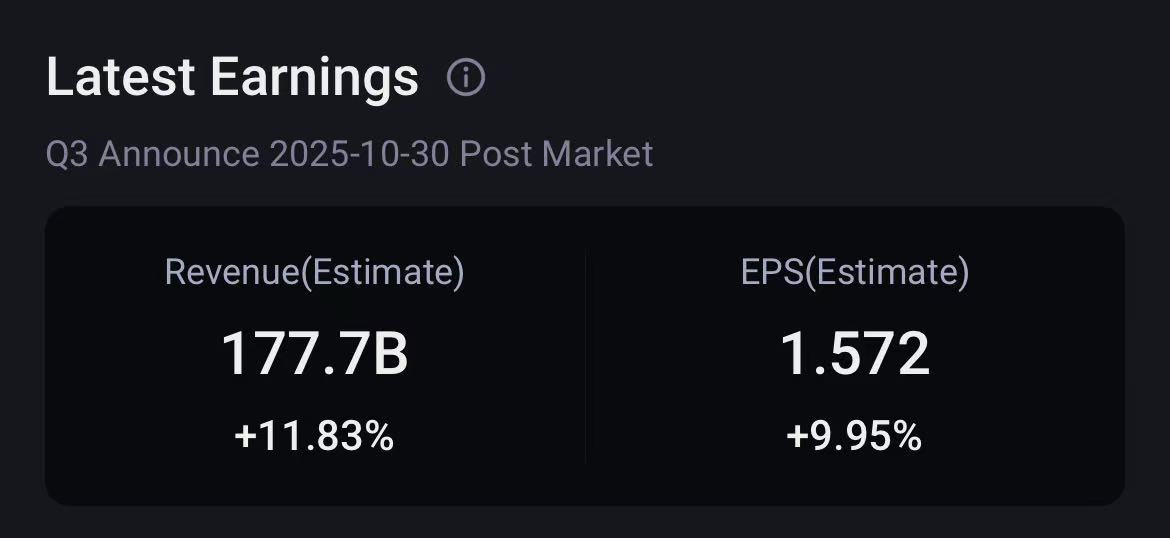
Amazon.com is expected to report its third quarter (Q3) 2025 earnings after the market closes on Thursday, 30 October 2025.
Here are consensus expectations from Tiger Trade for Microsoft's Q1 earnings:
Revenue: $177.7 billion, up 11.83% YoY
EPS: $1.572, up 9.95% YoY
Previous Quarter Review
Amazon's second-quarter (Q2) results, delivered in late July, exceeded expectations in both revenue and earnings per share (EPS), although its share price fell by 8.27% the following session as it failed to live up to lofty expectations for its Amazon Web Services cloud computing unit after rivals handily beat Wall Street forecasts.
Revenues of $167.7 billion, surpassing the $162.09 billion expected
Amazon Web Services (AWS) revenues increased by 17.5% YoY to $30.9 billion in Q2. By comparison, sales for Microsoft's Azure rose 39% and Google Cloud gained 32%
AWS profit margins were 32.9% in the second quarter, down from 39.5% in this year's first quarter and 35.5% a year ago
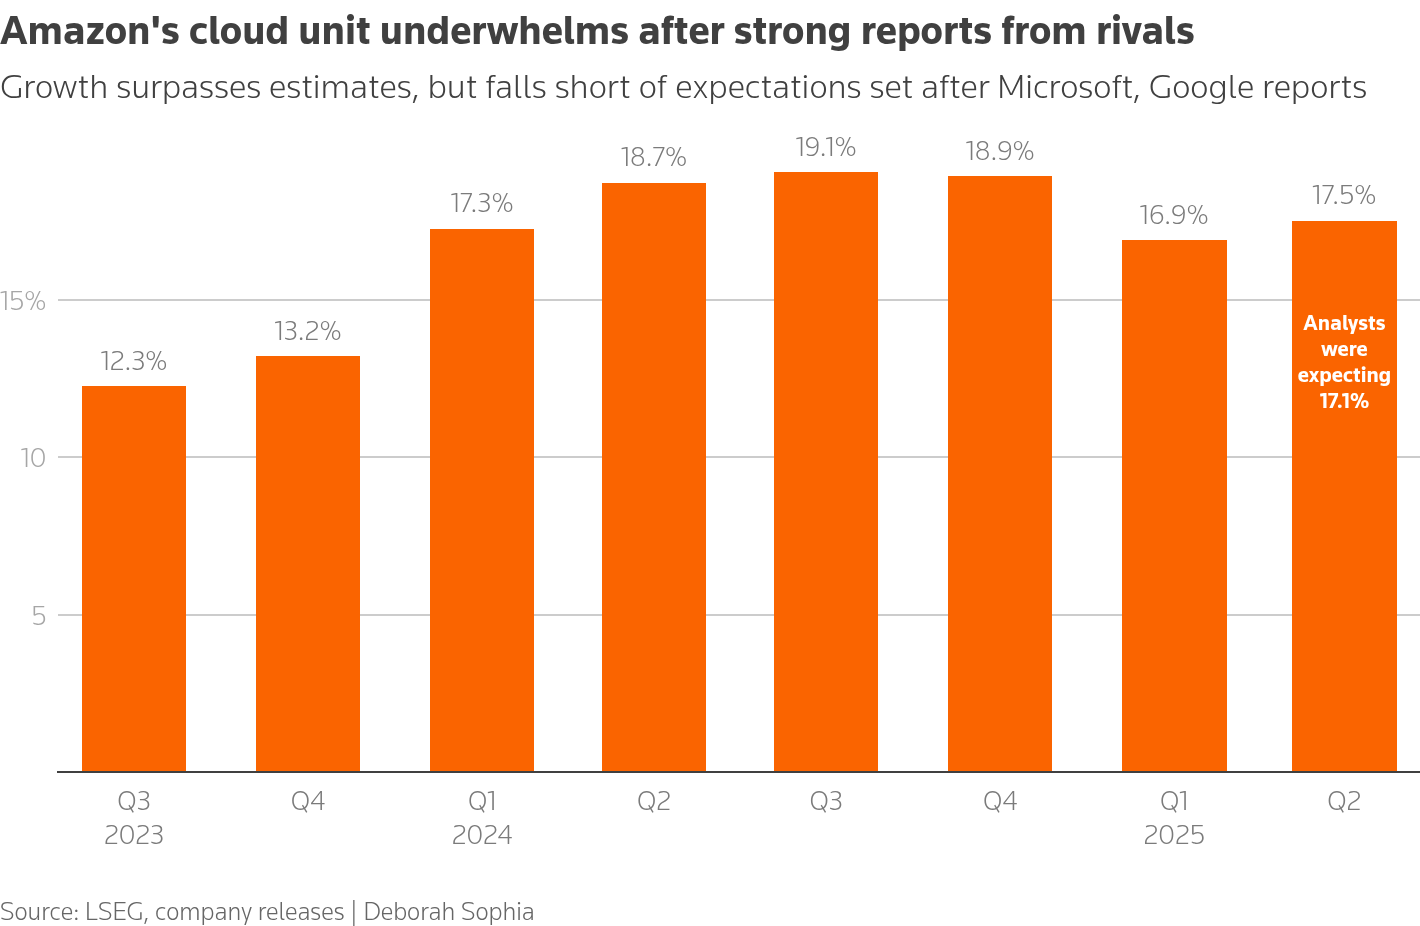 Amazon's cloud unit underwhelms after strong reports from rivals
Andy Jassy, President and CEO, stated, 'Our AI progress across the board continues to improve our customer experiences, speed of innovation, operational efficiency, and business growth, and I'm excited for what lies ahead.'
AWS Margins & AI Uptake
Investors will closely monitor AWS revenue growth, a key driver of Amazon’s profitability. Amazon will need to show investors that it can accelerate AWS growth after last quarter’s ho-hum 17.5% growth rate, which led some to wonder if AWS was failing to gain incremental artificial-intelligence workloads.
Deutsche Bank analyst Lee Horowitz pointed out that the fate of the stock "all comes down to AWS." While Amazon has been constrained by supply this year, Horowitz said that increasing capacity from Project Rainier coming online will help boost AWS growth to the 18% to 19% range for the current quarter.
Project Rainier is an Amazon data-center initiative that's viewed as key to an AWS reacceleration. Analysts anticipate this development could help ease some of Amazon's capacity constraints, which have hurt AWS' ability to gain a bigger share of existing AI workloads up to this point.
Investors also need to watch for commentary on Bedrock, Titan, and Anthropic partnerships and particularly whether enterprise demand is driving incremental GPU utilization and higher pricing.
Any sign that AI adoption is slow or margin-dilutive could weigh on sentiment.
Capex and AI investments
Amazon's CapEx (purchases of property and equipment less its proceeds) totaled $31.4 billion in the most recent quarter, or about 19% of the company's total revenues—when in the last three quarters this percentage had not exceeded 13% to 16%.
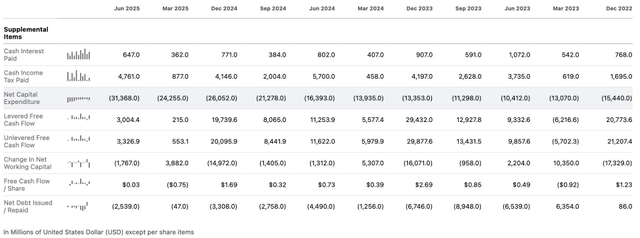 Q2 Capex
The ongoing capex surge, largely for AI-driven data centre expansion and custom silicon like Trainium chips, will be scrutinised for early returns on AI workloads, especially as competitors like Microsoft Azure and Google Cloud intensify their AI offerings.
E-Commerce and Advertising Growth
In Q2, Amazon posted online store sales of $61.5 billion, an 11% gain, and the company projected similar growth for Q3. Advertising sales, a fast-growing segment for Amazon, were up 23% to $15.7 billion in the second quarter.
As Q3 leads into the critical Q4 holiday season, Amazon’s guidance for Q4 sales and operational efficiency in its e-commerce segment will be key.
Amazon’s e-commerce segment has benefited from cost cuts and logistics automation, but a weakening consumer backdrop and higher credit card and consumer spending could limit upside.
Advertising has become Amazon’s hidden profit engine, but it’s highly correlated with broader ad budgets. A slowdown in retail media or competition from TikTok and Walmart Connect could compress growth rates.
Wall Street Sentiment and Forecasts
Despite 2025’s relatively tepid stock performance, investor sentiment around Amazon remains largely positive. The sheer scale and diversification of Amazon’s businesses – e-commerce, cloud, ads, devices, media, and more – give many market experts confidence that the company can navigate economic ups and downs. As mentioned, analysts are almost unanimously bullish on AMZN. According to TipRanks data, Amazon carries a “Strong Buy” consensus with dozens of buy ratings and virtually no sell ratings. The average price target is roughly $265–270 per share, implying significant upside.
Goldman Sachs reaffirmed Amazon as one of its top picks, raising its 12-month price target from $240 to $275. Goldman’s thesis is that the market is underestimating Amazon’s long-term cloud and advertising strength, and that margins in those segments will expand as growth continues. Morgan Stanley likewise added Amazon to its focus list of top investments, arguing that Amazon’s foray into groceries and continued e-commerce innovation could unlock new growth drivers worth hundreds of billions in sales. And in mid-October, BMO Capital and Wedbush both highlighted Amazon’s upside around the coming earnings season: BMO expects AWS growth to reaccelerate into year-end, and Wedbush believes Amazon (along with Microsoft and Google) will surprise the Street with strong Q3 results given “very robust AI enterprise demand” in cloud services. Wedbush’s tech analyst Dan Ives went as far as saying the Street is “still underestimating” the scale of the AI boom and its benefit to Big Tech, predicting a wave of blockbuster earnings and higher capital spending guidance for 2026 as companies double down on AI.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.