


Meta 3Q Preview | Meta Aided by Video Ads; Higher Spending Limits Upward Revisions to 2025 Operating Margin


Meta Platforms is set to release its Q3 2025 financial results on Oct 29 after the US market closes. Meta's Q3 revenue is expected to be $49.38 billion, up 21.65% year-on-year. Earnings per share is expected to grow 10.69% YoY to $6.675, according to data from Tiger Trade App.
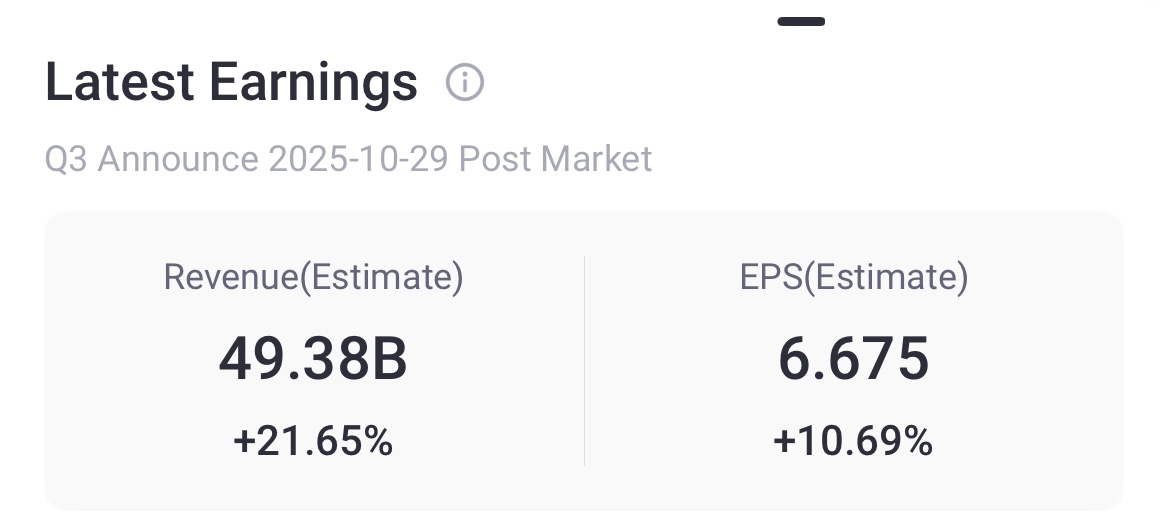 Source: Tiger Trade App
Three Things to Watch in 3Q
Ad-Pricing Growth Expected With Improved Targeting, AI Content
Meta's ad business remains the cash machine funding everything else. Ad pricing may remain supported by the company's improved ad targeting and recommendation system, which was key to sustaining top-line growth of above 20% in 1H.
The company's share of video ads continues to increase amid uncertainty around the divestiture of TikTok US, while the introduction of ads on WhatsApp could be another driver of ad impressions growth. Amid recent traction for Al-generated images from OpenAI's Sora and Gemini's Nano Banana, Meta may focus on adding more AI content to its family of apps to boost engagement.
Higher Spending Limits Upward Revisions to 2025 Operating Margin
Recent multiyear Al deals with CoreWeave and Oracle suggest Meta might rent compute infrastructure on top of its capital-spending growth expectation of 40-45% for 2026, which could drag on free cash flow in the near term.
Meta’s operating margin jumped to 43% in Q2, thanks to both rising sales and cost efficiency. Any comments on expense trends will be key, especially as Meta’s full-year 2025 expense outlook ($114–118B) and huge capital spending budget are well known.
If Meta managed to keep costs in check even as it invests in AI and the metaverse, that could bode well for earnings. On the flip side, if expenses swelled or if ad revenue came in lighter than expected, that could raise some concerns.
Reality Labs Losses May Widen as Tariff Exposure RaisesHardware Costs
Meta is also likely to provide updates on Reality Labs in its report. Shareholders understand that segment will show a deep loss, but they will look for signs of progress – e.g. new AR/VR features, user stats for Horizon Worlds, or traction of the new Quest 3 headset launched in October. Even modest wins could help justify the continued investment.
Meta’s experimental ventures are costly. Its Reality Labs division, which develops virtual reality, augmented reality, and metaverse platforms, continues to run heavy losses (about $3.7 billion lost in Q2 alone). Those red ink figures reflect massive spending on long-term projects like the metaverse, AR glasses, and AI research that may take years to pay off. The market seems willing to tolerate these investments as long as Meta’s core profits are strong – which they have been.
Analysts' Opinions
Meta stock price target maintained at $900 by BofA on strong ad outlook
BofA Securities has reiterated its Buy rating on Meta Platforms Inc., currently trading at $732.17 with a market cap of $1.84 trillion, with a price target of $900.00, citing potential revenue upside driven by improving macroeconomic conditions and accelerating AI benefits.
Meta Platforms price target raised to $837 from $811 at Wells Fargo
Wells Fargo raised the firm’s price target on Meta Platforms (META) to $837 from $811 and keeps an Overweight rating on the shares. The firm is raising estimates on continued ads strength on steady macro augmented by investments driving impression growth and conversion improvement. Wells expects Q4 guide ahead and sees 20%-plus growth necessary to stave off concerns on emerging competition for engagement.
Mizuho analyst calls Meta Platforms stock a top pick with a price target of $925
Mizuho analyst Lloyd Walmsley initiated coverage of Meta Platforms and Google parent Alphabet with a Buy rating, reflecting his optimism about the growth potential of these tech stocks. In fact, Walmsley assigned social media giant Meta Platforms a “Top Pick” status with a price target of $925, saying that it is Mizuho’s “favorite long-term holding in Internet.”
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.