


Earnings Preview | Analysts Bullish on Coca-Cola, Expect Coca-Cola Zero Sugar to Continue Leading Core Carbonated Category in Q3


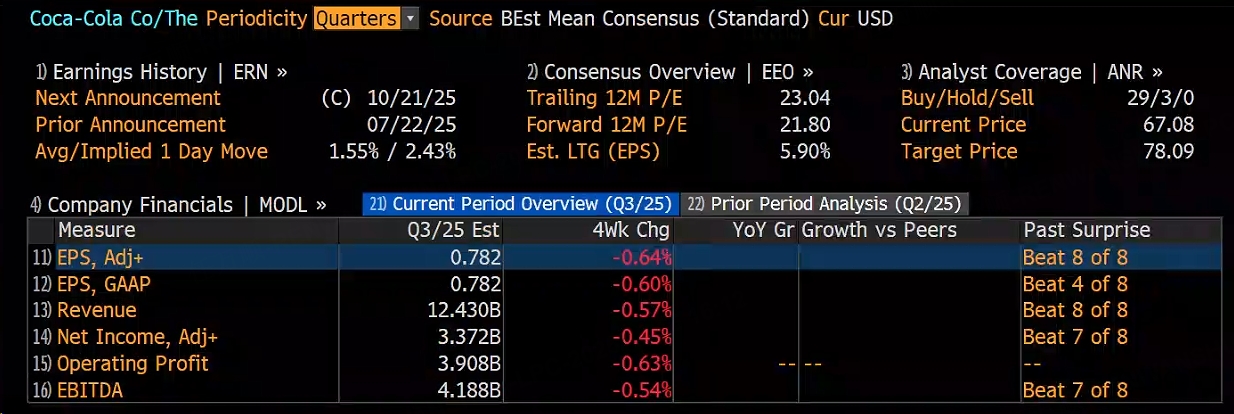
Coca-Cola is set to release its 2025 third-quarter earnings on October 21. According to Bloomberg analysts, Coca-Cola's third-quarter revenue is expected to be $12.43 billion, down 0.57% year-on-year; adjusted net profit is estimated at $3.372 billion, down 0.45% year-on-year.
Last Quarter Review
In the second quarter, Coca-Cola’s net revenue (GAAP) grew 1% year-on-year to $12.54 billion; adjusted revenue reached $12.62 billion, exceeding the market expectation of $12.54 billion, up 2.5% year-on-year; adjusted earnings per share (EPS) were $0.87, beating the expectation of $0.83, up 4% year-on-year; operating profit increased significantly by 63%, with the operating profit margin rising to 34.1%, the highest in recent years; Coca-Cola Zero Sugar sales grew 14%, marking a continuous double-digit growth since Q4; the North American market saw Diet Coke sales grow for the fourth consecutive quarter; the performance of the protein shake brand in the US was strong, following the trend of healthy beverage consumption.

The guidance for organic revenue growth of 5%-6% for the full year remains unchanged.
This Quarter Outlook
Channel and price-volume balance restoration
North America's price-volume rebalancing is the key focus for the third quarter. After contributing approximately +6 percentage points from price/mixture and -1% in unit case volume in Q2, institutions generally expect the price/mixture in Q3 to maintain positive growth (around +4%-5%), with unit case volume likely to be flat or slightly positive. At the end of Q2, management disclosed the brand relationship restoration with Hispanic consumers, combined with targeted promotions and marketing efficiency enhancements in fast-food services and outdoor consumption scenarios, expected to support volume recovery. On the channel side, the company will continue revenue growth management (RGM) and segmented packaging, launching new products in convenience, dining, and out-of-home consumption scenarios, and deploying cold drink equipment to improve sales density and shelf speed. According to multiple institutional forecasts, Q3 promotion elasticity in major US channels will focus more on maintaining price stickiness rather than simply reducing prices, aiming to preserve structured profits and brand positioning, which will have a positive impact on gross margin stability.
"Affordability + Premiumization" dual strategies in Latin America
After being affected by adverse weather and market fluctuations in Q2, the strategy in Latin America for Q3 will emphasize affordability through reusable packaging, value packs, and connected packaging, while advancing single-serve packaging, digital platforms, and premiumization sequences in Brazil and Mexico to stabilize structured profits. Institutions' judgments on the Latin American region in Q3 anticipate sales recovery and price stickiness, extending organic growth. Notable is the company's deepening digitalization of channels and penetration into small store systems in Latin America, driving refill frequency and category mix optimization. Combined with localized flavors and seasonal marketing rhythms, this supports quarter-over-quarter sales improvement. If local currency fluctuations remain controllable, Q3 contributions to this region will likely manifest in volume recovery and structural balance, buffering the overall company's price-volume recovery.
EMEA resilience continues, Asia Pacific differentiation subsides
EMEA's resilience stems from the continued momentum of Coca-Cola Zero Sugar and the active performance of Sprite and Fanta categories, expected to maintain steady performance in Q3. Eurasia and the Middle East emphasize localized flavors and pricing strategies, while Africa focuses on channel development and cold drink equipment deployment, significantly improving end-point availability. Earlier, ASEAN's weakness and India’s pressure from monsoon and geopolitical factors impacted the Asia Pacific region. Nevertheless, Coca-Cola's brand and dining channel in the Chinese market continue to improve, with the company advancing channel refinement and equipment placement expected to gradually stabilize in Q3. Under the institutional consensus framework, the core dependence of subsiding differentiation in Asia Pacific lies in the recovery of dining channels, implementation of scenario marketing, and maintaining price/mixture contributions. Favorable coordination of weather and seasonal factors in Southeast Asia will mitigate negative disturbances, providing smoother support for the company's organic growth overall.
Category and innovation drive
Structural upgrades in Coca-Cola Zero Sugar and fizzy drinks will grasp profit quality in Q3. Coca-Cola Zero Sugar has achieved double-digit growth for four consecutive quarters, expected to continue leading the core carbonated categories in Q3, boosting unit contribution and strengthening price/mixture advantages structurally. Sprite's recipe and flavor innovations (like Sprite Tea) in the US have become new traffic drivers, enhancing the sequence and reaching younger demographics. Institutions anticipate Q3 overall fizzy drink sales will be flat to slightly positive, continuing price/mixture contributions to sustain gross margin improvement by carbonated drink mainstays. In terms of dairy and functional beverages, Fairlife maintains double-digit growth but faces capacity constraints, with management clarifying the new factory's production in early 2026 to alleviate constraints, focusing on channel deepening and category expansion for quality growth in Q3. Sports drinks were under pressure in Q2, while Q3 will see seasonal recovery and traffic from major events, combining optimized channel displays and restocking rhythms to marginally improve sales. In pricing and packaging strategies, RGM continues layered pricing and packaging optimization, combining affordability schemes with premiumization, and more markets deploying intelligent channel/packaging price optimization tools to increase price resilience and shelf speed, effectively supporting terminal conversion rates.
Analyst Views
From the Q3 preview public angle, bullish views dominate.
Multiple international and local institutions maintain positive ratings, with core support from price/mixture and cost productivity supporting margins, sustained EMEA stability, North American sales recovery, and subsiding differentiation in Asia Pacific. The consensus expectation centers around "revenue of approximately $12 billion, adjusted EPS of about $0.72", with year-on-year improvements in gross margins.
Representative viewpoints show institutions predict Q3 organic revenue to remain within the 4%-6% range, year-on-year improvements in gross margin of about 50-100 basis points, adjusted EPS of approximately $0.72, and favoring Zero Sugar and energy/functional beverages' momentum. This suggests profitability improvement sustainability driven by product structure and cost efficiency.
Moreover, institutions highlight stabilization and recovery in Mexico and India markets, expecting flat to +1% sales, price/mixture contributions of +4%-5%, combined with Latin America’s push for affordability and premiumization, and implementation of channel and franchise adjustments in India, volume recovery likely to offset price slowdowns. Investment banks also caution FX's negative impact on EPS by about 4-5 percentage points, identifying exchange rate as Q3’s primary non-operational headwind, recommending attention to cost productivity and structural optimization's counter-effects, and Latin American sales recovery and Asia Pacific stability supporting the full-year guidance.
This content is generated based on Tiger AI and Bloomberg data, and is intended for reference only.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.