


 Discount


Broadcom Inc Stock (AVGO) Moved Down by 6.24% on Nov 20: Drivers Behind the Movement


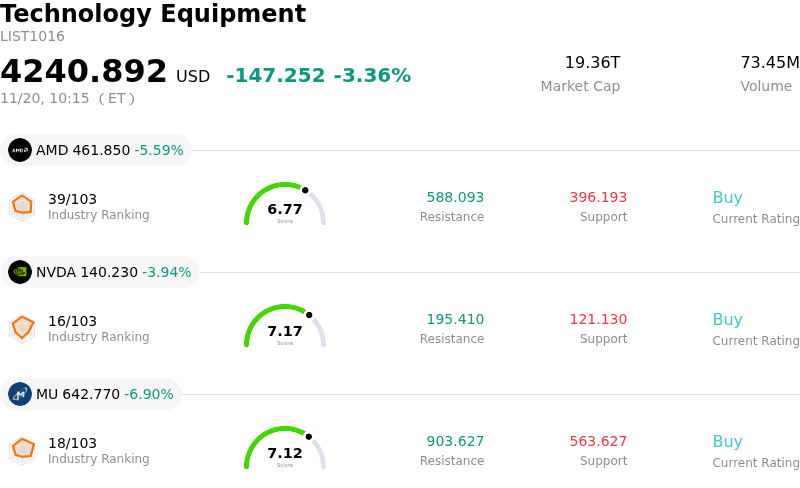
Broadcom Inc (AVGO) moved down by 6.24%. The Technology Equipment sector is down by 3.36%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Advanced Micro Devices Inc (AMD) down 5.29%; NVIDIA Corp (NVDA) down 3.75%; Micron Technology Inc (MU) down 6.63%.
What is driving Broadcom Inc (AVGO)’s stock price down today?
Broadcom is experiencing notable downward pressure as broad-based profit-taking across semiconductor bellwethers converges with micro-level scrutiny over the pacing of artificial intelligence infrastructure spending. Following an extended run-up in mega-cap technology equities, institutional investors are rotating capital out of high-multiple semiconductor holdings amid renewed macro uncertainty and shifting interest rate expectations. Because Broadcom has served as a primary vehicle for exposure to custom application-specific integrated circuits and advanced networking silicon, it remains particularly sensitive to systematic de-risking and multiple compression across the broader technology sector.
At the industry and operational level, market participants are reassessing the near-term trajectory of custom AI accelerator deployments across key hyperscale cloud service providers. While long-term demand for custom compute solutions and high-bandwidth networking switches remains structurally intact, concerns regarding potential production transition windows, lumpy order cadence from key hyperscale customers, and capacity allocation constraints at leading foundries have introduced near-term caution. Furthermore, persistent cyclical softness in legacy non-AI semiconductor end markets, including broadband access, enterprise storage, and traditional carrier wireless infrastructure, continues to mute the consolidated growth profile, preventing a faster rebound in enterprise-oriented hardware revenue.
Simultaneously, institutional sentiment is digesting the intermediate financial impact of the VMware software integration. While the transition of the virtualization portfolio toward high-value annual subscription models provides long-term recurring cash flow predictability, short-term friction surrounding licensing restructuring and customer renewals has prompted some institutional models to adjust their margin expansion curves. Heightened sensitivity to operating expense management and cash conversion efficiency has led certain sell-side analysts to trim near-term target multiples.
From a portfolio flow perspective, systematic funds and institutional desks appear to be rebalancing risk exposure ahead of upcoming calendar milestones, generating elevated selling volume. With short-term momentum indicators triggering automated unwinds, the current decline reflects a confluence of sector-wide valuation recalibration, cyclical headwinds in legacy merchant silicon, and tactical repositioning, rather than a fundamental impairment of Broadcom's dominant long-term enterprise software and AI connectivity franchises.
Technical Analysis of Broadcom Inc (AVGO)
Technically, Broadcom Inc (AVGO) shows a MACD (12,26,9) value of 3.931, indicating a neutral signal. The RSI at 45.811 suggests neutral condition and the Williams %R at 56.050 suggests sell condition. Please monitor closely.
Media Coverage of Broadcom Inc (AVGO)
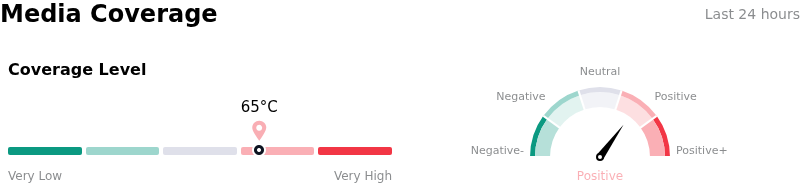
In terms of media coverage, Broadcom Inc (AVGO) shows a coverage score of 65, indicating a high level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Broadcom Inc (AVGO)
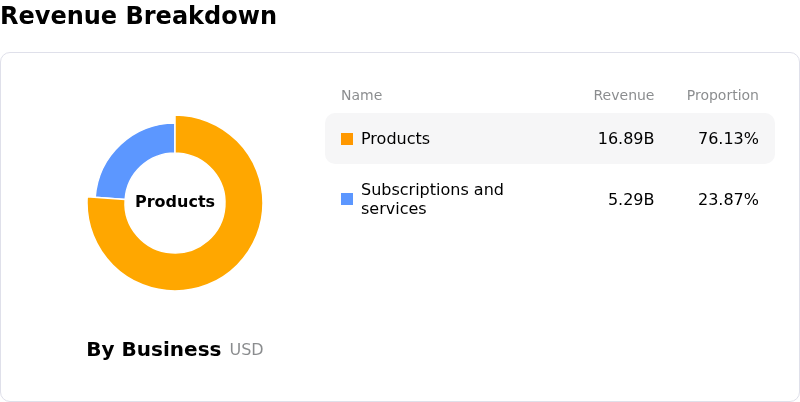
Broadcom Inc (AVGO) is in the Technology Equipment industry. Its latest annual revenue is $63.89B, ranking 5 in the industry. The net profit is $23.13B, ranking 5 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $516.73, a high of $663.00, and a low of $215.88.
More details about Broadcom Inc (AVGO)
Company Specific Risks:
- Contingent Financing Exposure to AI Customers: Institutional analysts have flagged mounting credit vulnerabilities tied to approximately $72 billion in contingent debt support and residual value guarantees provided to key AI lab customers, posing significant cash flow and balance sheet risks if customer monetization and capital expansion lag expectations.
- Customer Concentration and ASIC Sourcing Disintermediation: Heightened exposure to a highly concentrated customer base—with the top five hyperscalers driving the majority of demand—faces structural risks as major partners like Alphabet actively explore alternative suppliers and in-house silicon tooling, threatening Broadcom's long-term custom accelerator pipeline.
- Analyst Price Target Reductions and Margin Dilution: Multiple Wall Street firms, including Goldman Sachs and TD Cowen, have lowered price targets due to margin compression worries, citing the lower gross margin profile of custom ASIC systems compared to legacy networking silicon and falling unit inference economics.
- High Leverage and VMware Execution Overhang: Broadcom continues to shoulder substantial acquisition-related debt of approximately $44 billion, which limits capital allocation flexibility and magnifies earnings downside ahead of the upcoming fiscal Q4 earnings report as enterprise software integration complexities persist.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.