


 Discount


Applied Materials Inc Stock (AMAT) Moved Down by 3.55% on Nov 19: Facts Behind the Movement


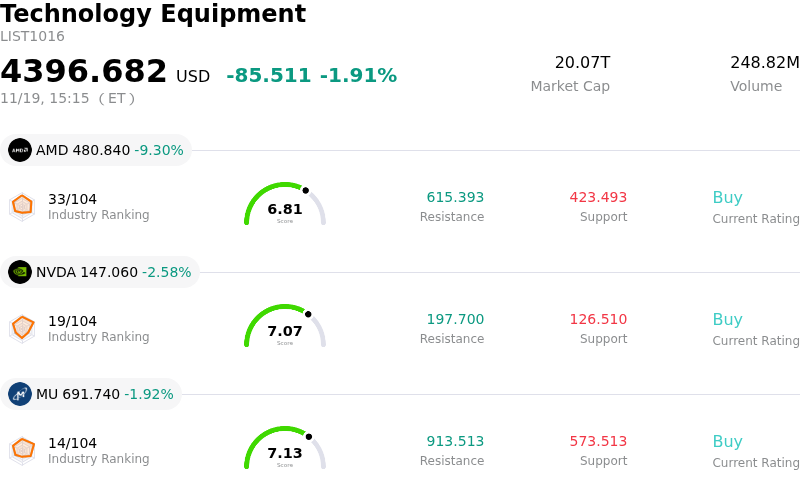
Applied Materials Inc (AMAT) moved down by 3.55%. The Technology Equipment sector is down by 1.91%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Advanced Micro Devices Inc (AMD) down 9.38%; NVIDIA Corp (NVDA) down 2.69%; Micron Technology Inc (MU) down 1.92%.
What is driving Applied Materials Inc (AMAT)’s stock price down today?
Applied Materials is facing downward pressure as institutional investors recalibrate expectations around near-term wafer fabrication equipment spending, particularly in mature technology nodes. While artificial intelligence infrastructure continues to drive solid demand for advanced packaging and leading-edge logic, cyclical weakness across broader consumer electronics, automotive, and industrial end markets has led chipmakers to maintain disciplined capital expenditures. This divergence creates uneven order momentum, prompting portfolio managers to adopt a more cautious stance toward front-end semiconductor equipment suppliers.
Geopolitical developments and regulatory overhang regarding semiconductor manufacturing equipment sales continue to act as a primary headwind for the stock. China has historically represented an outsized portion of revenue for wafer fab equipment vendors due to aggressive domestic capacity expansion. Concerns that tighter export controls and localized supply-chain initiatives will constrain high-margin equipment shipments, coupled with signs that previous inventory front-loading by regional customers is normalizing, have heightened operational uncertainty and weighed on medium-term revenue visibility.
Broader macroeconomic conditions and capital market dynamics have amplified the pullback. Firm benchmark interest rates and cautious enterprise spending commentary across the semiconductor ecosystem have encouraged profit-taking in high-valuation technology names. When cyclical recovery timelines for memory and general-purpose logic are extended, institutional capital typically rotates into more defensive assets or direct beneficiaries of immediate artificial intelligence deployments rather than capital equipment providers with longer lead times.
Analyst sentiment has mirrored this cautious backdrop, with several sell-side desks adjusting margin projections and price targets to reflect potential deceleration in equipment billings over the coming quarters. While Applied Materials maintains an industry-leading position in materials engineering solutions and benefits from structural tailwinds such as gate-all-around transitions and backside power delivery, prevailing market sentiment remains focused on near-term demand digestion and geopolitical risks. Until broader customer capital budgets show decisive acceleration outside of isolated high-bandwidth memory and advanced logic categories, the shares are likely to encounter ongoing valuation compression.
Technical Analysis of Applied Materials Inc (AMAT)
Technically, Applied Materials Inc (AMAT) shows a MACD (12,26,9) value of 1.333, indicating a neutral signal. The RSI at 36.966 suggests neutral condition and the Williams %R at 74.441 suggests sell condition. Please monitor closely.
Media Coverage of Applied Materials Inc (AMAT)
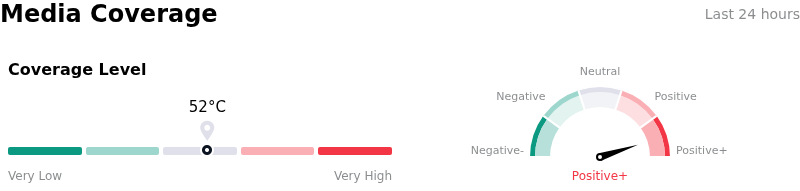
In terms of media coverage, Applied Materials Inc (AMAT) shows a coverage score of 52, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Applied Materials Inc (AMAT)
Applied Materials Inc (AMAT) is in the Technology Equipment industry. Its latest annual revenue is $34.45B, ranking 10 in the industry. The net profit is $10.09B, ranking 8 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $625.37, a high of $900.00, and a low of $308.00.
More details about Applied Materials Inc (AMAT)
Company Specific Risks:
- Guidance Disconnection and Cleanroom Bottlenecks: Despite top-line figures beating prior-year baselines, near-term revenue guidance failed to satisfy elevated institutional whisper consensus, as customer facility delays and cleanroom readiness bottlenecks continue to stall equipment delivery and installation schedules, prompting price target cuts across major brokerages.
- China Revenue Contraction and Regulatory Exposure: High-margin shipments to China are projected to decelerate below 25% of the overall revenue mix, creating an acute margin headwind that leading-edge domestic orders have yet to offset amid persistent threats of tighter U.S. semiconductor export controls.
- Wafer Fab Capex Rotation Headwinds: Sell-side analysts warn of an adverse reallocation of wafer fabrication equipment (WFE) budgets away from deposition and etch segments toward lithography tools, placing Applied Materials' highest-margin Semiconductor Systems product lines at direct competitive and market-share risk.
- Hyperscaler Cyclicality and Capex Plateau Vulnerability: Institutional investors are increasingly scrutinizing the durability of artificial intelligence capital expenditure beyond the current buildout phase, creating valuation compression for equipment providers whose earnings are heavily geared to new capacity additions rather than recurring silicon production.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.