


 Discount


Lam Research Corp Stock (LRCX) Moved Down by 3.39% on Nov 19: A Full Analysis


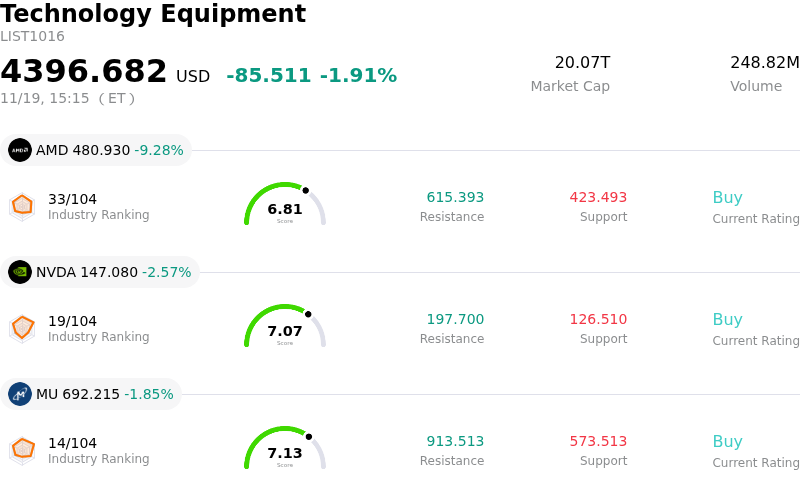
Lam Research Corp (LRCX) moved down by 3.39%. The Technology Equipment sector is down by 1.91%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Advanced Micro Devices Inc (AMD) down 9.38%; NVIDIA Corp (NVDA) down 2.69%; Micron Technology Inc (MU) down 1.92%.
What is driving Lam Research Corp (LRCX)’s stock price down today?
Lam Research came under notable selling pressure as broader sentiment across the semiconductor capital equipment sector turned defensive, driven by a confluence of cyclical reassessments and geopolitical headwinds. As a leading supplier of critical etch and deposition systems, the company is directly tied to global wafer fabrication spending, leaving its valuation sensitive to shifts in institutional risk appetite and near-term capital expenditure visibility across the semiconductor supply chain.
A key catalyst weighing on the stock is ongoing market digestion of management guidance regarding regional demand and shipment timing. While recent quarterly revenue and profitability demonstrated solid operational execution, forward outlooks were tempered by component supply constraints that pushed select tool deliveries into future quarters. More critically, institutional investors remain concerned about an anticipated contraction in revenue contribution from China. With export restrictions tightening and domestic Chinese fab purchasing normalizing after elevated spending levels, this impending regional top-line headwind has prompted Wall Street analysts to reset growth expectations for the coming quarters.
Industry dynamics also contributed to the downward pressure as market participants re-evaluate the near-term capital intensity of memory manufacturers. Lam Research maintains outsized exposure to DRAM and NAND production lines. Although long-term secular demand for high-bandwidth memory tied to artificial intelligence accelerators remains structural, traditional memory producers continue to practice capital discipline, focusing on selective technology node migrations rather than aggressive greenfield capacity expansion. This measured capex posture limits near-term tool order acceleration and creates lingering visibility concerns for wafer fab equipment suppliers.
Broader macroeconomic and sector-wide sentiment compounded the decline, as technology-focused portfolios rotated away from high-beta semiconductor capital equipment names in sympathy with peers. Lingering debates over the return on investment for hyperscale artificial intelligence infrastructure have sparked valuation compression across the entire semiconductor value chain. Despite solid balance sheet strength and active capital return initiatives, institutional desks adopted a cautious stance, favoring risk reduction over bottom-fishing until clear catalysts emerge regarding supply-chain normalization and memory spending reacceleration.
Technical Analysis of Lam Research Corp (LRCX)
Technically, Lam Research Corp (LRCX) shows a MACD (12,26,9) value of 2.042, indicating a neutral signal. The RSI at 35.854 suggests neutral condition and the Williams %R at 66.352 suggests sell condition. Please monitor closely.
Media Coverage of Lam Research Corp (LRCX)
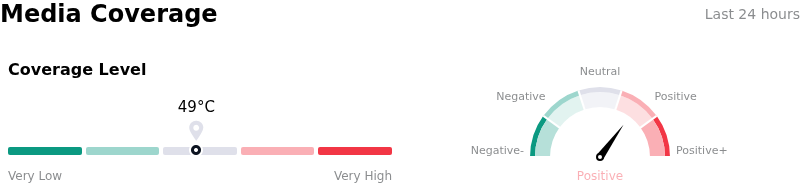
In terms of media coverage, Lam Research Corp (LRCX) shows a coverage score of 49, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Lam Research Corp (LRCX)
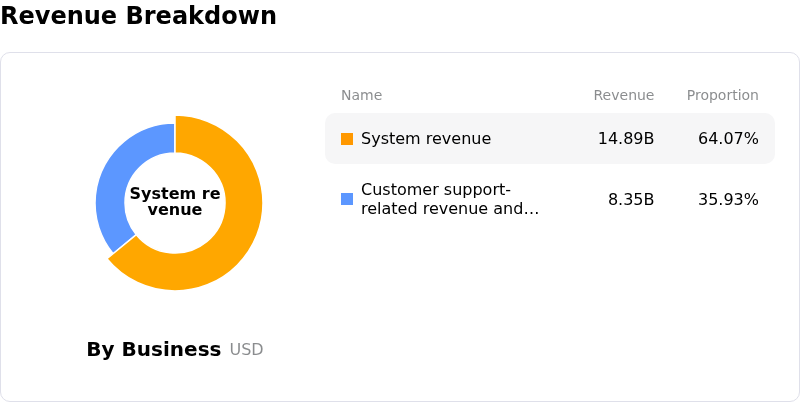
Lam Research Corp (LRCX) is in the Technology Equipment industry. Its latest annual revenue is $23.23B, ranking 12 in the industry. The net profit is $7.27B, ranking 9 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $358.02, a high of $500.00, and a low of $213.00.
More details about Lam Research Corp (LRCX)
Company Specific Risks:
- Memory Capex Retrenchment: Heightened institutional concern over disciplined, selective capital spending by key DRAM and NAND customers threatens tool shipment timelines, elevating revenue visibility risks for Lam's core etch and deposition systems.
- China Revenue Contraction and Regulatory Headwinds: With China accounting for approximately 35% of Lam's quarterly revenue, approaching geopolitical export restriction deadlines and projected sequential contractions in regional fab shipments are actively compressing valuation multiples across the equipment peer group.
- Assembly and Cleanroom Capacity Constraints: Component bottlenecks and facility space limitations continue to hinder tool integration and delay system deliveries, leaving near-term revenue conversion strictly supply-constrained despite high order backlogs.
- Defensive Options Skew and Insider Disinvestment: A sharp rise in implied volatility to the upper quartile alongside a steepening put-call skew reflects elevated institutional hedging against near-term drawdowns, exacerbated by cumulative insider sales exceeding $169 million without offsetting insider purchases.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.