


 Discount


Shopify Inc Stock (SHOP) Moved Down by 5.25% on Nov 19: A Full Analysis


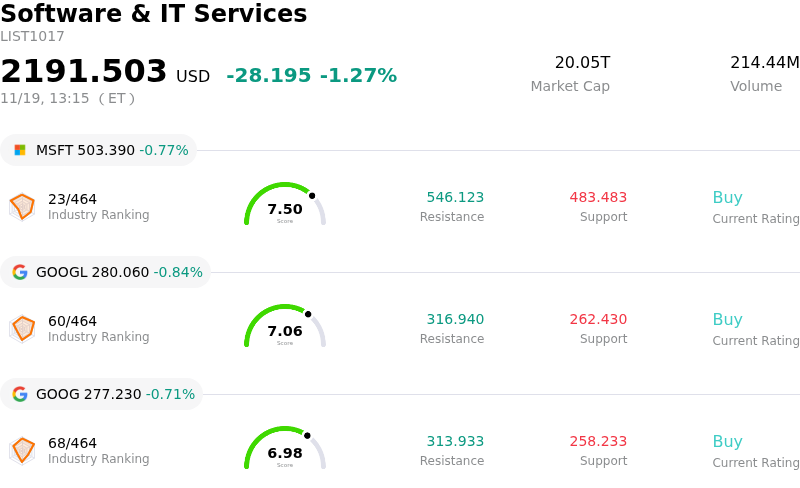
Shopify Inc (SHOP) moved down by 5.25%. The Software & IT Services sector is down by 1.27%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) down 0.82%; Alphabet Inc Class A (GOOGL) down 0.90%; Alphabet Inc Class C (GOOG) down 0.71%.
What is driving Shopify Inc (SHOP)’s stock price down today?
Shopify is experiencing notable downward pressure as a confluence of macroeconomic crosscurrents, sector-wide valuation compression, and pre-holiday retail caution weigh heavily on investor sentiment. High-growth, premium-multiple software and e-commerce platforms are particularly sensitive to shifts in benchmark bond yields and broader equity market risk appetite. As macroeconomic indicators keep interest rate expectations elevated, institutional capital has engaged in tactical de-risking away from long-duration digital retail assets, prompting broad-based multiple contractions across the cloud and software-as-a-service landscape.
Beyond broader tech market rotation, industry-specific concerns regarding underlying consumer spending trends are tempering near-term enthusiasm. With peak holiday shopping season events directly ahead, market participants are scrutinizing merchant gross merchandise volume momentum and discretionary purchasing power. Lingering consumer softness, elevated household credit burdens, and promotional fatigue among small and medium-sized businesses threaten to constrain transaction volume growth. In addition, intensifying competition across social commerce and alternative direct-to-consumer fulfillment networks has renewed scrutiny over take-rate sustainability and merchant acquisition costs.
Institutional portfolio repositioning has amplified the magnitude of the pullback. Following extended momentum runs, asset managers often utilize periods of heightened market volatility to lock in gains and trim aggressive exposures. Elevated options activity and dynamic hedging around high-beta retail tech have compounded intraday swings, leading to accelerated technical selling as key support thresholds were challenged. A relatively robust dollar further poses mild currency translation headwinds for international merchant volumes, adding another layer of fundamental caution.
Despite the near-term drawdown, Shopify maintains robust structural tailwinds, anchored by enterprise merchant tier adoption, recurring subscription software revenues, and disciplined operational expense execution. However, until broader interest rate volatility subsides and early holiday sales data confirm resilient merchant order activity, the stock is likely to remain subject to heightened sensitivity and sentiment-driven repositioning. Institutional investors should monitor fourth-quarter payment penetration metrics and international merchant retention for signs of fundamental stabilization.
Technical Analysis of Shopify Inc (SHOP)
Technically, Shopify Inc (SHOP) shows a MACD (12,26,9) value of -4.290, indicating a sell signal. The RSI at 32.634 suggests neutral condition and the Williams %R at 99.827 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Shopify Inc (SHOP)
Shopify Inc (SHOP) is in the Software & IT Services industry. Its latest annual revenue is $11.56B, ranking 33 in the industry. The net profit is $1.23B, ranking 41 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $176.65, a high of $220.00, and a low of $120.00.
More details about Shopify Inc (SHOP)
Company Specific Risks:
- Gross Margin Deceleration and Escalating Compute Costs: Fourth-quarter forward guidance indicates gross profit growth in the high-twenties percentage range will lag behind total revenue growth in the low-thirties, compressed by an ongoing mix shift toward lower-margin Merchant Solutions and rising infrastructure expenses required to support AI and large language model workloads.
- Core GMV and Subscription Revenue Shortfall: Recent financial disclosures showing Gross Merchandise Volume of $119.1 billion and Subscription Solutions revenue missing institutional consensus expectations continue to trigger selling pressure, amplifying concerns over decelerating platform transaction velocity ahead of the critical holiday shopping window.
- Valuation Multiples Vulnerability and Analyst Downgrades: Operating at an elevated valuation exceeding 60x forward earnings, the stock has drawn fresh analyst downgrades citing an unfavorable risk-reward profile and elevated expectations, leaving shares hypersensitive to multiple compression during broader software sector de-risking.
- Monetization Lag and Acquisition Headwinds in Agentic Commerce: Aggressive developmental expenditures directed toward agentic commerce partnerships and automated checkout integrations are outpacing immediate bottom-line realization, while institutional research cautions that shifts toward AI agents and search changes pose near-term customer acquisition friction for small-to-medium merchants.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.