


 Discount


Accenture PLC Stock (ACN) Moved Down by 4.35% on Nov 19: A Full Analysis


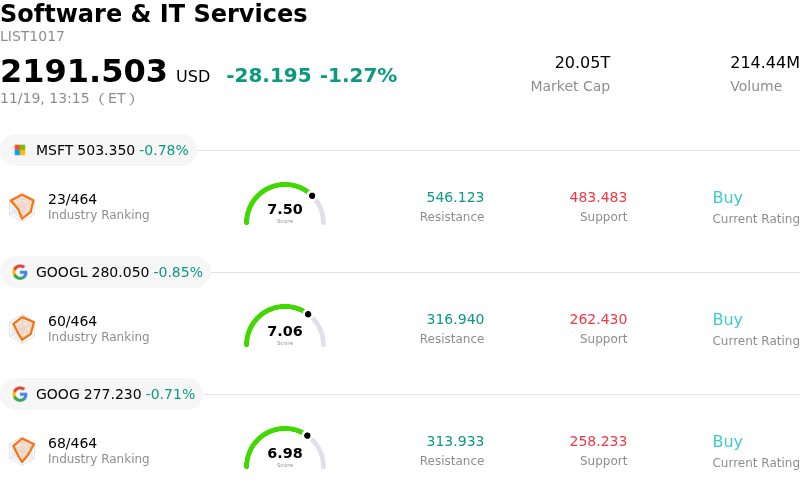
Accenture PLC (ACN) moved down by 4.35%. The Software & IT Services sector is down by 1.27%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) down 0.82%; Alphabet Inc Class A (GOOGL) down 0.90%; Alphabet Inc Class C (GOOG) down 0.71%.
What is driving Accenture PLC (ACN)’s stock price down today?
Accenture came under selling pressure as heightened caution surrounding enterprise IT budgets and consulting demand weighed on institutional sentiment. Investors are growing increasingly sensitive to signs of prolonged procurement cycles and hesitation among Fortune 500 decision-makers regarding discretionary technology investments. While demand for long-term managed services and cloud migration remains foundational, conversion rates for shorter-cycle advisory and strategic transformation projects appear subdued. This dynamic creates near-term margin friction, as high-value consulting engagements typically carry superior profitability compared to routine operational outsourcing.
Compounding this headwind is an ongoing capital allocation shift within corporate technology spend. Rather than accelerating broad-based systems integration and enterprise-wide workflows, many corporate clients are directing a disproportionate share of their tech budgets toward foundational artificial intelligence infrastructure, compute capacity, and proprietary data preparation. Although Accenture has positioned itself aggressively as a primary implementation partner for enterprise artificial intelligence deployment, the monetization timeline for scalable, billable execution continues to face market scrutiny. Institutional investors appear cautious regarding how quickly early-stage proof-of-concept engagements will convert into high-volume, recurring top-line revenue, prompting some fund managers to trim exposure in favor of direct infrastructure providers.
From a macroeconomic perspective, broader uncertainty regarding global economic growth and corporate earnings visibility has reinforced a disciplined, cost-conscious posture among chief financial officers. Discretionary consulting contracts remain among the easiest operational expenditures to defer, downsize, or pause during periods of strategic reassessment. In addition, cautious read-throughs from peer IT services providers and the broader enterprise software ecosystem have amplified concerns that competitive bidding and billing rate pressures could compress operating margins over the near term. While Accenture maintains an industry-leading market position, healthy balance sheet strength, and deep multi-year client relationships, current trading reflects a valuation reassessment as investors await tangible evidence of a broader reacceleration in discretionary corporate spending.
Technical Analysis of Accenture PLC (ACN)
Technically, Accenture PLC (ACN) shows a MACD (12,26,9) value of -12.383, indicating a neutral signal. The RSI at 36.888 suggests neutral condition and the Williams %R at 97.340 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Accenture PLC (ACN)
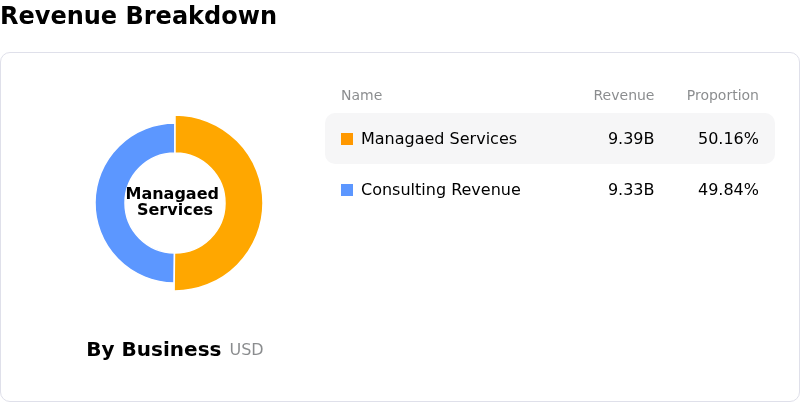
Accenture PLC (ACN) is in the Software & IT Services industry. Its latest annual revenue is $74.18B, ranking 6 in the industry. The net profit is $8.37B, ranking 13 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $237.59, a high of $329.00, and a low of $185.71.
More details about Accenture PLC (ACN)
Company Specific Risks:
- Enterprise Discretionary Budget Curtailment and Extended Sales Cycles: Corporate clients are actively deferring non-essential consulting engagements and fragmenting large-scale digital transformation programs into smaller, milestone-driven phases, resulting in elongated procurement cycles and a slower conversion of contracted bookings into billable revenue.
- Major Client Contract Restructuring and Workforce Reductions: Operational risks have materialized following disclosures that the company is eliminating approximately 950 client-linked roles in Portugal tied to key customer accounts such as Meta, signaling reduced scope and expenditure across specialized managed services and content operations contracts.
- Generative AI Billing Deflation and Pricing Concessions: Rapid enterprise deployment of automated AI tooling is exerting deflationary pressure on conventional time-and-materials billing models, as smaller-value AI advisory engagements fail to immediately offset billable hour erosion and competitive discounting in legacy systems integration.
- Near-Term Margin Compression Ahead of Fiscal Q1 Earnings: Consensus estimates projecting a year-over-year earnings-per-share contraction for the upcoming quarterly disclosure reflect persistent margin friction driven by recent pricing concessions across core segments, restructuring charges, and elevated operational overhead.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.