


 Discount


Marathon Petroleum Corp Stock (MPC) Closed Down by 5.23% on Nov 18: A Full Analysis


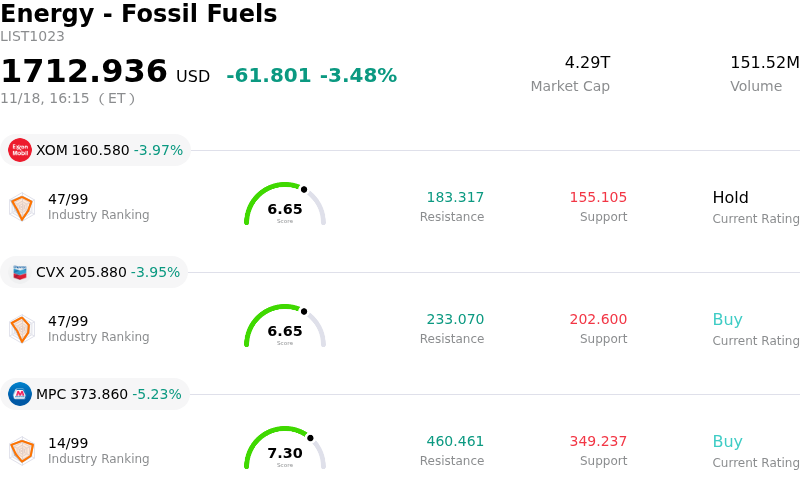
Marathon Petroleum Corp (MPC) closed down by 5.23%. The Energy - Fossil Fuels sector is down by 3.48%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Exxon Mobil Corp (XOM) down 3.97%; Chevron Corp (CVX) down 3.95%; Marathon Petroleum Corp (MPC) down 5.23%.
What is driving Marathon Petroleum Corp (MPC)’s stock price down today?
Marathon Petroleum experienced notable downward pressure during the trading session, driven primarily by a sharp contraction in benchmark refining margins and emerging headwinds across the downstream energy complex. Refining crack spreads, particularly the 3-2-1 indicator, faced substantial compression as refined product supply outpaced near-term consumption patterns. For a merchant refiner of Marathon Petroleum's scale, profitability remains acutely sensitive to shifts in product cracks, prompting institutional desks to recalibrate near-term margin realization models and trim cyclical downstream exposure.
Compounding this margin squeeze, broader market sentiment was dampened by inventory data highlighting unseasonal builds in finished gasoline and distillate stockpiles. Elevated inventories point to softening domestic freight activity and more cautious consumer driving trends, raising concerns about product off-take during the transitional demand period. In addition, firming feedstock costs placed incremental pressure on gross refining margins, narrowing the sweet-sour crude differentials that typically provide structural cost advantages to complex Gulf Coast and Mid-Continent refining networks.
From an institutional portfolio standpoint, broader energy sector weakness and risk-off sentiment accelerated the pullback. Investors frequently utilize large-cap refiners as liquid tactical vehicles to express views on cyclical demand and crack spread momentum. When crack spreads deteriorate alongside persistent crude input costs, downstream equities often face concentrated de-risking flows. Institutional profit-taking and rotational adjustments toward less margin-sensitive energy segments added to the selling momentum.
Operational and capital allocation considerations also factored into investor positioning. While Marathon Petroleum continues to support shareholder value through substantial share repurchases and stable distributions from its midstream partnership, the market remains sensitive to operating costs and planned turnaround schedules. Higher refinery maintenance expenses or lower throughput guidance during margin downturns can compress free cash flow generation, dampening immediate return expectations.
Looking ahead, share price stabilization will hinge largely on the trajectory of crack spreads, refinery utilization discipline across the domestic fleet, and broader macroeconomic indicators. While the company retains an industry-leading operational footprint and substantial balance sheet flexibility, sustained multiple expansion and equity recovery will require inventory normalization and clearer evidence of resilient consumer and industrial fuel demand.
Technical Analysis of Marathon Petroleum Corp (MPC)
Technically, Marathon Petroleum Corp (MPC) shows a MACD (12,26,9) value of -6.837, indicating a sell signal. The RSI at 35.773 suggests neutral condition and the Williams %R at 90.826 suggests oversold condition. Please monitor closely.
Media Coverage of Marathon Petroleum Corp (MPC)
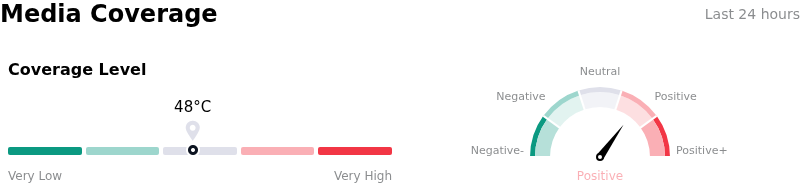
In terms of media coverage, Marathon Petroleum Corp (MPC) shows a coverage score of 48, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Marathon Petroleum Corp (MPC)
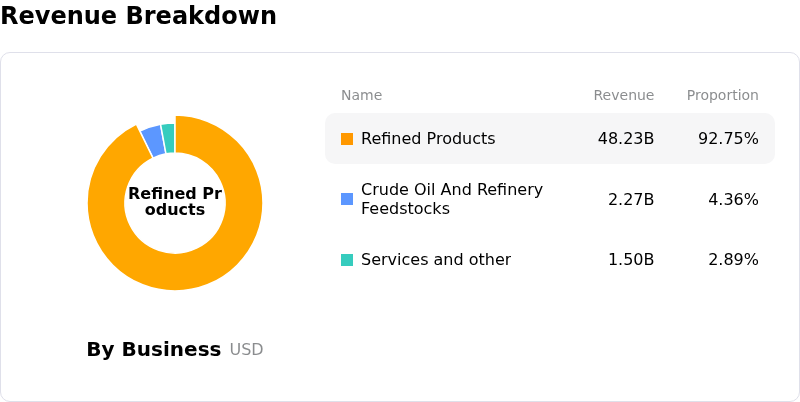
Marathon Petroleum Corp (MPC) is in the Energy - Fossil Fuels industry. Its latest annual revenue is $133.43B, ranking 6 in the industry. The net profit is $4.04B, ranking 13 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $443.27, a high of $564.00, and a low of $186.93.
More details about Marathon Petroleum Corp (MPC)
Company Specific Risks:
- Crack Spread Normalization and Peak Margin Reversal: Following third-quarter refining margins reaching $45.70 per barrel, institutional analysts caution that downstream profitability is confronting immediate mean-reversion pressure as product crack spreads decline and favorable light-heavy crude differentials exhaust their margin benefit.
- Sequential Throughput Contraction and Planned Turnaround Expenses: Fourth-quarter guidance projects a utilization drop to 95% and throughput deceleration to approximately 2.8 million barrels per day alongside $230 million in scheduled turnaround expenses, triggering immediate compression in sequential operating leverage and free cash flow generation.
- Geographic Concentration Risk from Mid-Continent Divestitures: The pending $4.2 billion asset divestiture of the Mandan and St. Paul Park refineries redeploys capital almost exclusively toward Gulf Coast operations, removing steady Mid-Continent inland crude advantages and exposing refining cash flows to regional weather disruptions and Gulf Coast export volatility.
- Capital Return Sustainability Under Mid-Cycle Valuation: Institutional commentary notes growing downside risk regarding the sustainability of the company's aggressive $8.1 billion share repurchase authorization and dividend payout run rate if refining cash generation slows toward normalized mid-cycle levels, highlighting vulnerability against discounted historical fair-value assessments.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.