


 Discount


Novo Nordisk A/S Stock (NVO) Moved Down by 3.12% on Nov 18: What Investors Need To Know


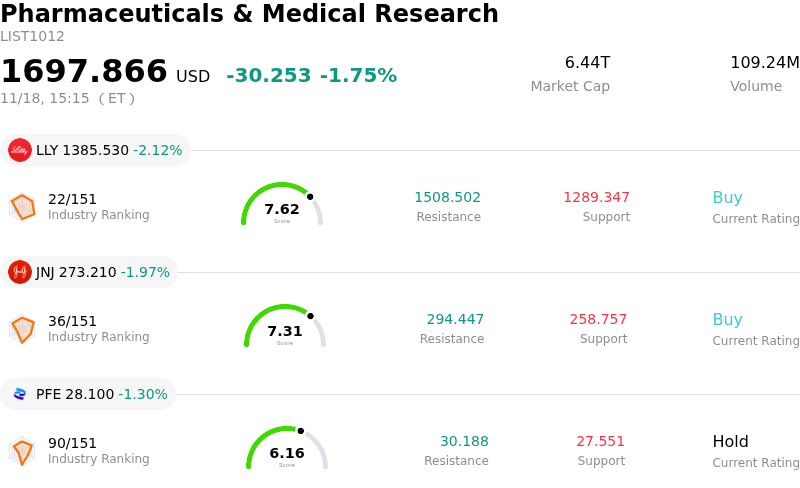
Novo Nordisk A/S (NVO) moved down by 3.12%. The Pharmaceuticals & Medical Research sector is down by 1.75%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Eli Lilly and Co (LLY) down 2.12%; Johnson & Johnson (JNJ) down 1.97%; Pfizer Inc (PFE) down 1.32%.
What is driving Novo Nordisk A/S (NVO)’s stock price down today?
Novo Nordisk experienced notable downward pressure during today's trading session, driven by a confluence of intensifying competitive dynamics in the obesity and cardiometabolic space, heightened pricing scrutiny, and broader defensive sector rebalancing. Institutional sentiment across the biopharmaceutical complex has grown increasingly discerning, with investors closely scrutinizing the sustainability of long-term volume and net pricing trajectories for core GLP-1 therapies.
A primary catalyst weighing on the stock centers on escalating competitive threats within the obesity landscape. Market participants are recalibrating long-term market share expectations as key rivals advance next-generation multi-agonist and oral metabolic candidates through pivotal clinical milestones. The potential entry of competing oral formulations and novel mechanisms such as dual amylin and calcitonin receptor agonists introduces medium-term risks to semaglutide's premium pricing power and volume dominance. Any incremental pipeline update from competitors highlighting superior tolerability profiles or more convenient administration routes prompts rapid multiple compression in existing market leaders.
Simultaneously, persistent structural scrutiny surrounding net realized drug prices continues to overhang the narrative. While demand for blockbuster weight-loss and diabetes treatments remains robust, pharmacy benefit manager negotiations and government payer programs in major markets, particularly the United States, are applying downward pressure on gross-to-net spreads. Investor anxiety regarding long-term formulary access, aggressive price concessions required to maintain preferred tier placement, and regulatory oversight regarding metabolic drug reimbursement schedules have dampened near-term earnings revision momentum.
Operational factors and manufacturing execution risks also remain top of mind for institutional allocators. While Novo Nordisk continues heavy capital deployment to scale global manufacturing infrastructure and integrate recent supply chain acquisitions, the normalization of capacity across the broader industry is beginning to narrow the supply deficits that previously protected incumbent market share. Additionally, the proliferation and regulatory oversight of compounding alternatives continue to present marginal headwinds to commercial momentum until broader distribution friction is entirely resolved.
From a portfolio allocation standpoint, broader equity market conditions contributed to the weakness. Macroeconomic cross-currents and rotation away from high-multiple healthcare leaders into cyclical assets or value-oriented segments created sector-wide headwinds. For institutional investors, Novo Nordisk's elevated valuation multiple leaves limited margin for execution slippage, magnifying pullbacks when clinical readouts, competitor advancements, or pricing debates introduce short-term uncertainty into the commercial thesis.
Technical Analysis of Novo Nordisk A/S (NVO)
Technically, Novo Nordisk A/S (NVO) shows a MACD (12,26,9) value of 0.029, indicating a buy signal. The RSI at 45.266 suggests neutral condition and the Williams %R at 97.063 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Novo Nordisk A/S (NVO)
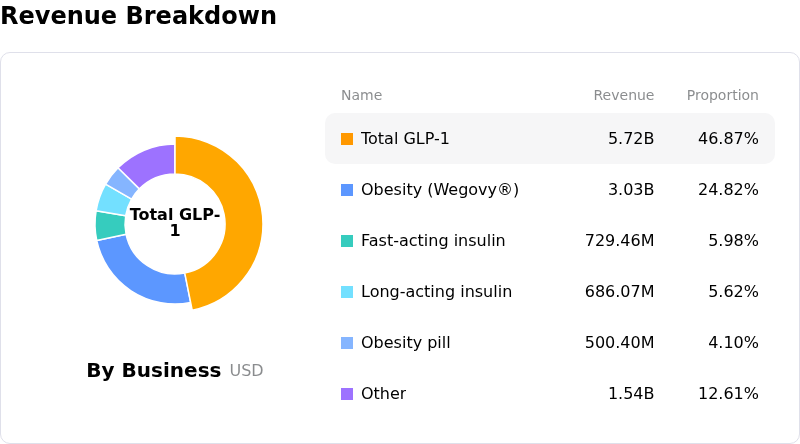
Novo Nordisk A/S (NVO) is in the Pharmaceuticals & Medical Research industry. Its latest annual revenue is $46.70B, ranking 12 in the industry. The net profit is $15.48B, ranking 4 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $48.19, a high of $65.00, and a low of $40.00.
More details about Novo Nordisk A/S (NVO)
Company Specific Risks:
- CagriSema Tolerability and Exploratory Trial Limitations: Following late-stage REDEFINE 1 sub-analyses presented at ObesityWeek, investor scrutiny intensified over elevated gastrointestinal tolerability issues, with digestive side effects reported in 79.6% of CagriSema recipients compared to 39.9% on placebo; furthermore, market concerns remain that the reported 25% weight loss figures stem from exploratory post-hoc responder evaluations rather than definitive primary efficacy end-points ahead of upcoming regulatory decisions.
- Surge in Bearish Institutional Derivatives Positioning: Market flow in recent sessions was characterized by an aggressive expansion of directional downside bets, with put options volume rising to over 41,000 contracts—roughly four times expected volume—and 30-day implied volatility climbing from 28.7% to 31.6%, underscoring institutional hedging against further downward share price momentum.
- Margin Erosion from Direct-to-Consumer Discounting: Novo Nordisk's expanded Novocare program introducing prescription home delivery and expanded self-pay/bridge coverage reflects intensifying commercial concessions required to counter Eli Lilly’s accelerating GLP-1 competition, exacerbating net realized price degradation in the core U.S. semaglutide market and pressuring near-term operating margins.
- Technical Channel Breakdown and Growth Guidance Overhang: Quantitative evaluations downgraded the stock to a Sell Candidate following heavy-volume rejection near overhead resistance ($41.11–$41.84), reinforcing persistent institutional analyst reluctance and Hold-heavy consensus ratings driven by long-term patent concentration concerns and unquantified near-term revenue stabilization timelines.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.