


Medline Ord Shs Class A Stock (MDLN) Closed Down by 5.17% on Nov 12: What Signal Does It Send?


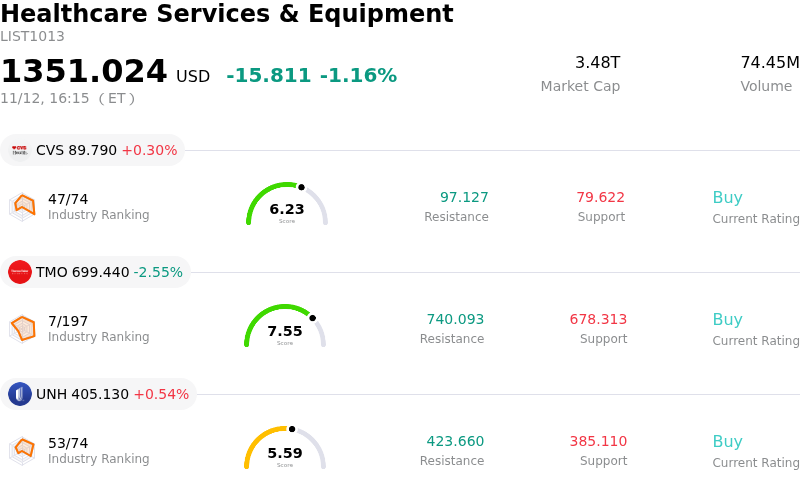
Medline Ord Shs Class A (MDLN) closed down by 5.17%. The Healthcare Services & Equipment sector is down by 1.16%. The company underperformed the industry. Top 3 stocks by turnover in the sector: CVS Health Corp (CVS) up 0.30%; Thermo Fisher Scientific Inc (TMO) down 2.55%; Unitedhealth Group Inc (UNH) up 0.54%.
What is driving Medline Ord Shs Class A (MDLN)’s stock price down today?
Following an aggressive post-earnings rally earlier in the month that pushed Medline Inc. shares sharply higher, the stock faced notable downward pressure driven primarily by institutional profit-taking and technical mean reversion. After a multi-session surge fueled by an upward revision to full-year organic revenue guidance and the authorization of a substantial share repurchase program, the equity reached overbought technical territory. Institutional desks capitalized on the rapid liquidity expansion to lock in short-term gains, sparking an intraday retrenchment.
The pullback was further amplified as market participants refocused on lingering fundamental and regulatory overhangs that had been temporarily eclipsed by headline revenue growth. Investors remain cautious regarding the operational and cash flow implications of the company's voluntary exit from its branded bed product line, which was prompted by regulatory safety notices. The remediation expenses associated with manufacturing compliance, alongside ongoing securities and product quality legal investigations, continue to cast a cloud over Medline's forward operational expenditure trajectory.
Underlying margin dynamics also weighed on sentiment. Despite solid volume execution across primary distribution channels, recent operating figures underscored gross margin contraction stemming from persistent inventory inflation, elevated distribution network expenses, and an adverse customer mix. Management's reliance on upcoming contract price adjustments to counteract structural cost inflation introduces execution risk, particularly given the cost-containment pressures currently faced by major health system clients.
Broader sector-wide positioning within healthcare supply chain and medical equipment equities added an additional layer of friction. With defensive sectors facing portfolio reallocation and capital rotating toward broader market benchmarks, institutional sponsorship softened during the session.
From an institutional standpoint, the pullback represents a sharp valuation consolidation following an overheated technical run. While Medline retains strong top-line scale and durable prime vendor relationships across healthcare networks, sustained upside will likely require demonstrable margin stabilization, successful pricing realization, and definitive closure on outstanding manufacturing quality and regulatory issues.
Technical Analysis of Medline Ord Shs Class A (MDLN)
Technically, Medline Ord Shs Class A (MDLN) shows a MACD (12,26,9) value of 1.475, indicating a buy signal. The RSI at 62.858 suggests neutral condition and the Williams %R at 22.642 suggests buy condition. Please monitor closely.
Fundamental Analysis of Medline Ord Shs Class A (MDLN)
Medline Ord Shs Class A (MDLN) is in the Healthcare Services & Equipment industry. Its latest annual revenue is $28.43B, ranking 5 in the industry. The net profit is $1.16B, ranking 13 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Medline Ord Shs Class A (MDLN)
Company Specific Risks:
- Severe Gross Margin Compression and Back-Half Cost Influx: Post-earnings analyst evaluations highlight mounting profitability pressure as gross margins compressed 190 basis points to 24.5% alongside a $122 million quarterly LIFO inventory inflation charge. Institutional analysts, including Evercore ISI and Mizuho, slashed price targets as management flagged that two-thirds of an estimated $200 million operational cost increase—worsened by approximately $80 million in elevated fuel and freight expenses—will impact Q4 2026, dampening full-year operating earnings and muting preliminary 2027 EBITDA growth.
- Product Recalls, FDA Remediation Drag, and Market Exit Expenses: Disclosures reveal that persistent quality control issues have forced a voluntary market exit of all Medline-branded hospital beds, which is projected to incur up to $220 million in exit and recall expenses over 2026–2027. In addition, the company is absorbing recurring multi-million-dollar remediation charges to address three unresolved FDA warning letters regarding finished-pharmaceutical manufacturing violations, curtailing product availability and suppressing higher-margin proprietary brand conversion.
- Prolonged Operational Inefficiencies from Tracy Facility Fire: The company continues to face severe logistics headwinds and financial drag from the fire that destroyed its Tracy, California distribution center, which generated an estimated $416 million in losses through nine months and caused an $80 million direct net income reduction in Q3. Elevated carrying costs, emergency distribution center leases across Northern California, and delayed timing of remaining insurance reimbursements continue to depress core distribution operating margins, which slipped to 4.4%.
- Securities Fraud Litigation and Institutional Divestment Overhang: A wave of class-action investigations launched by securities litigation firms regarding alleged misrepresentations of manufacturing quality and product compliance continues to weigh heavily on trading sentiment. Compounding this intraday pressure, the stock faces substantial overhead from large-scale shareholder divestments, including multi-million-share liquidations by sovereign wealth fund GIC and private-equity sponsors unwinding pre-IPO holdings.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.