


Super Micro Computer Inc Stock (SMCI) Moved Down by 11.54% on Nov 12: Facts Behind the Movement


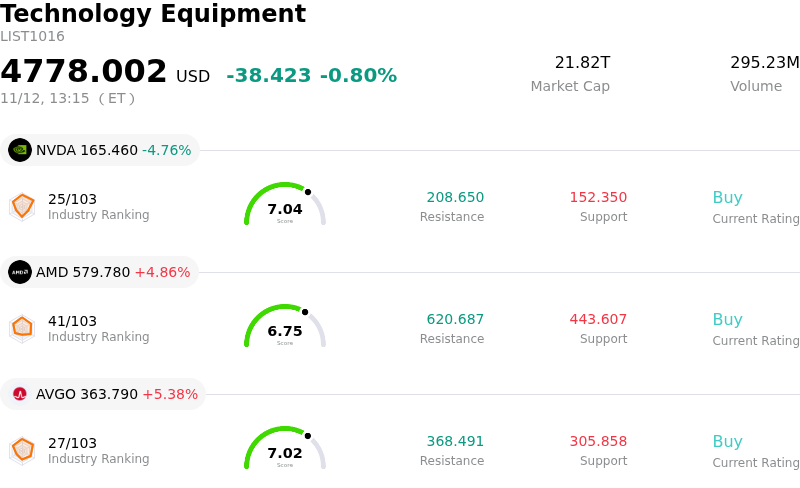
Super Micro Computer Inc (SMCI) moved down by 11.54%. The Technology Equipment sector is down by 0.80%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 4.74%; Advanced Micro Devices Inc (AMD) up 4.80%; Broadcom Inc (AVGO) up 5.38%.
What is driving Super Micro Computer Inc (SMCI)’s stock price down today?
Super Micro Computer experienced severe downward pressure during the session, driven by a confluence of margin concerns, broader weakness across the artificial intelligence hardware supply chain, and renewed investor scrutiny regarding operating cash flow sustainability. Despite robust long-term enterprise demand for high-density compute clusters and advanced liquid-cooling server architectures, market participants reacted negatively to signs of ongoing gross margin compression and heavy working capital requirements needed to support high-cost component inventories.
From a fundamental perspective, institutional investors are increasingly cautious about the divergence between top-line revenue volume and bottom-line profitability. Elevated bill-of-materials costs tied to leading-edge graphics processors, combined with aggressive pricing and market-share competition from traditional enterprise original equipment manufacturers such as Dell Technologies and Hewlett Packard Enterprise, continue to weigh on unit margins. In addition, extended cash-conversion cycles and inventory accumulation have kept operating cash flows constrained, elevating balance sheet scrutiny among risk-sensitive asset managers.
Broader sector sentiment also amplified the pullback. A broader risk-off posture across high-beta technology equities prompted systematic fund rebalancing and institutional de-risking out of hardware assemblers. Cautious analyst commentary regarding customer concentration risks and potential delivery timing shifts among tier-one cloud service providers further dampened speculative momentum. As implied volatility climbed, quantitative and algorithmic strategies accelerated selling pressure across the stock.
Looking forward, the company's near-term equity performance will likely hinge on its ability to demonstrate sustainable gross margin defense and tangible progress toward positive free cash flow generation. While secular growth trends in generative artificial intelligence infrastructure remain intact, institutional capital is expected to maintain a cautious stance until clear evidence emerges of improved pricing power and capital efficiency.
Technical Analysis of Super Micro Computer Inc (SMCI)
Technically, Super Micro Computer Inc (SMCI) shows a MACD (12,26,9) value of -0.549, indicating a sell signal. The RSI at 36.239 suggests neutral condition and the Williams %R at 88.827 suggests oversold condition. Please monitor closely.
Media Coverage of Super Micro Computer Inc (SMCI)
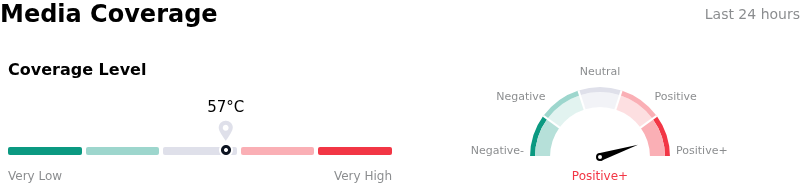
In terms of media coverage, Super Micro Computer Inc (SMCI) shows a coverage score of 57, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Super Micro Computer Inc (SMCI)
Super Micro Computer Inc (SMCI) is in the Technology Equipment industry. Its latest annual revenue is $39.06B, ranking 6 in the industry. The net profit is $2.20B, ranking 7 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $44.63, a high of $65.00, and a low of $15.00.
More details about Super Micro Computer Inc (SMCI)
Company Specific Risks:
- Severe Working Capital Drain and Negative Cash Flow: Recent analyst commentary highlights ongoing liquidity pressure as the company burned $434 million in operating cash flow and reported negative free cash flow of $481 million, exacerbated by surging inventory build-ups that climbed to $15.1 billion.
- Extreme Customer Concentration Vulnerability: Wall Street research flagged that a single customer accounted for 44% of total revenue, leaving revenue streams exceptionally fragile to procurement delays, price concessions, or order diversion by this anchor client.
- Component Supply Constraints and Delivery Bottlenecks: Institutional updates note that near-term guidance continues to be gated by component availability and high-performance hardware procurement rather than end demand, creating severe shipment and fulfillment execution risks.
- Export Control Scrutiny and Legal Overhang: Ongoing federal litigation and investigations involving previous GPU system shipments to China remain an active regulatory overhang, suppressing institutional valuation multiples despite top-line expansion.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.