


Qualcomm Inc Stock (QCOM) Moved Up by 3.20% on Nov 12: Facts Behind the Movement


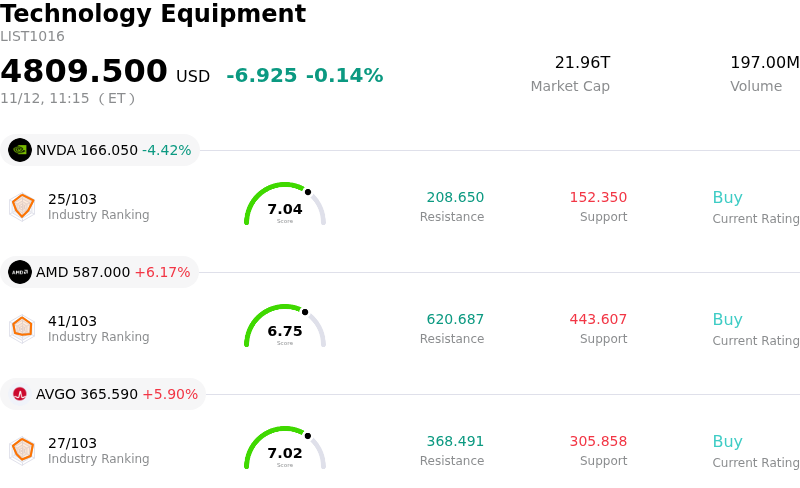
Qualcomm Inc (QCOM) moved up by 3.20%. The Technology Equipment sector is down by 0.14%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 4.40%; Advanced Micro Devices Inc (AMD) up 6.21%; Broadcom Inc (AVGO) up 5.93%.
What is driving Qualcomm Inc (QCOM)’s stock price up today?
Qualcomm demonstrated resilient upward momentum during the trading session, reflecting renewed institutional confidence in the company's operational restructuring and its strategic pivot beyond the mature smartphone landscape. Investors responded favorably to management's disciplined execution of cost-optimization measures, including targeted workforce rationalization, which is expected to structurally lower operating expenses and protect operating margins amid ongoing headwinds in mobile handset demand.
From an industry and strategic perspective, institutional capital is increasingly valuing Qualcomm's long-term revenue diversification into automotive and edge artificial intelligence computing. The continued expansion of the Snapdragon Digital Chassis platform across global automakers and the accelerating adoption of next-generation processors in connected devices and enterprise IoT are providing crucial operational offsets to softness in traditional handset sales. Market participants view the reallocation of capital and engineering bandwidth toward high-growth, higher-margin compute architectures as an essential catalyst for multi-year multiple expansion.
Macroeconomic stability across the broader semiconductor complex and stabilizing customer inventory levels have also provided a supportive backdrop for high-beta chipmakers. With the market actively pricing in cost-structure efficiencies and the bottoming of client-side hardware supply chains, institutional sentiment has shifted toward accumulation, particularly among value-oriented technology funds seeking solid free cash flow generation and defensive capital returns through dividends and share repurchases.
Looking ahead, while the gradual attrition of legacy baseband modem supply agreements with key Tier-1 original equipment manufacturers remains a known operational headwind, Qualcomm's improving earnings quality, aggressive operational streamlining, and expanding automotive backlog reinforce an attractive risk-reward profile for medium-to-long-term investors. Continued progress in design win conversions within industrial edge computing and sustained expense discipline will remain the critical benchmarks for extending this upward trajectory.
Technical Analysis of Qualcomm Inc (QCOM)
Technically, Qualcomm Inc (QCOM) shows a MACD (12,26,9) value of 2.038, indicating a neutral signal. The RSI at 55.577 suggests neutral condition and the Williams %R at 9.159 suggests overbought condition. Please monitor closely.
Media Coverage of Qualcomm Inc (QCOM)
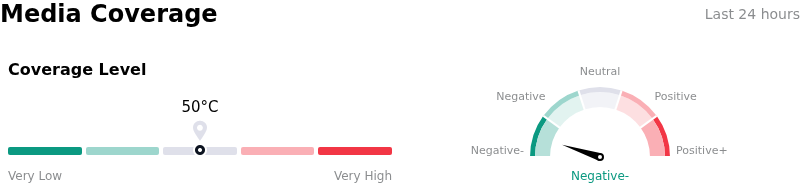
In terms of media coverage, Qualcomm Inc (QCOM) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bearish zone.
Fundamental Analysis of Qualcomm Inc (QCOM)
Qualcomm Inc (QCOM) is in the Technology Equipment industry. Its latest annual revenue is $43.12B, ranking 7 in the industry. The net profit is $13.63B, ranking 6 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Qualcomm Inc (QCOM)
Company Specific Risks:
- Analyst Downgrades and Prolonged Margin Compression: Freedom Broker downgraded Qualcomm from Buy to Hold and lowered its price target to $185, pointing to a fourth consecutive quarter of gross margin contraction to 52.4% and cautioning that input-cost inflation in memory and fabrication alongside elevated R&D for data center custom silicon will suppress operating margins longer than consensus forecast.
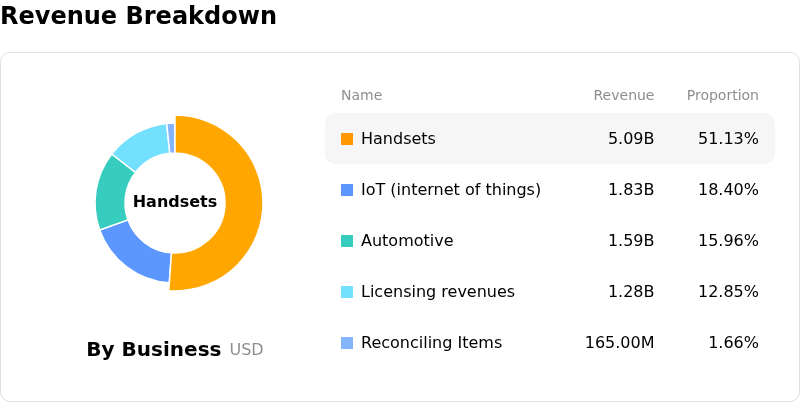
- Severe Contraction in Core Smartphone Chip Revenue: Trading volatility continues to reflect fallout from a 26% year-over-year collapse in handset revenue down to $5.14 billion, leading to a 30% decline in handset pretax earnings as rising component prices and extended consumer upgrade cycles depress volumes in Qualcomm's primary revenue driver.
- Accelerating Revenue Loss from Apple Modem Disintermediation: Multiple research desks reduced forward earnings estimates due to acute customer concentration risk, warning that Apple's accelerated transition to proprietary modems will strip out high-margin 5G socket revenue faster than automotive and enterprise AI expansions can backfill the multi-billion-dollar gap.
- Elevated Leverage and Rising Financing Costs from Debt Issuance: Regulatory disclosures confirming Qualcomm's pricing of a $4.0 billion multi-tranche senior notes offering—featuring coupons up to 5.80%—have raised analyst scrutiny over expanding balance sheet leverage and increased ongoing annual debt-service costs during an operational transition.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.