


ASE Technology Holding Co Ltd Stock (ASX) Moved Up by 6.65% on Nov 11: What Signal Does It Send?


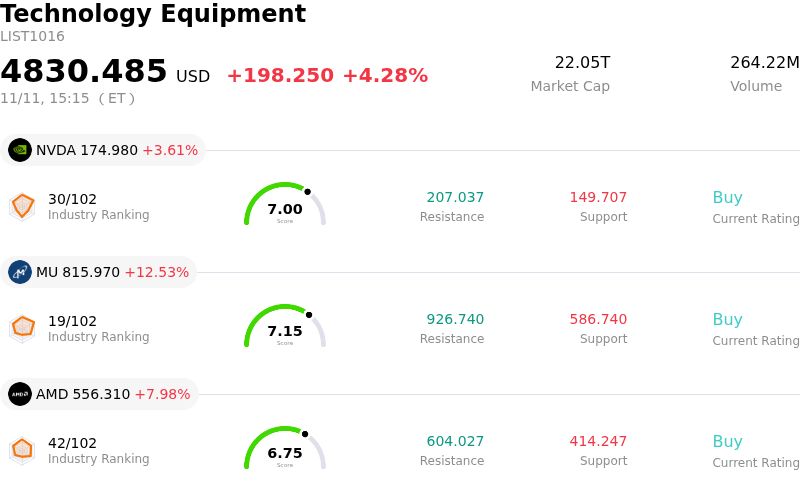
ASE Technology Holding Co Ltd (ASX) moved up by 6.65%. The Technology Equipment sector is up by 4.28%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 3.61%; Micron Technology Inc (MU) up 12.45%; Advanced Micro Devices Inc (AMD) up 7.98%.
What is driving ASE Technology Holding Co Ltd (ASX)’s stock price up today?
ASE Technology experienced significant upside momentum primarily driven by robust monthly revenue performance and strengthening demand visibility across its core operations. The company reported substantial year-over-year expansion in consolidated revenue, highlighted by an impressive acceleration in its Assembly, Testing, and Material business. Surging demand for high-performance computing and artificial intelligence applications continues to drive higher packaging complexity and greater testing value per unit, reinforcing market confidence in the company's operating leverage.
Market sentiment was further bolstered by an optimistic growth outlook surrounding advanced packaging capabilities. With demand for complex chip packaging and high-density integration exceeding initial industry estimates, upward revisions to advanced packaging revenue targets have underscored sustained structural tailwinds. Institutional investors have increasingly viewed the company as a critical downstream beneficiary of the ongoing hardware infrastructure buildout, benefiting from outsourced demand from major foundries and leading fabless chip designers.
The upward price trajectory was also amplified by favorable technical dynamics and elevated derivative positioning. A notable surge in bullish call option volume reflected heightened institutional and retail interest, facilitating a sharp rebound following previous consolidation. This aggressive options activity, combined with a broader sector-wide rally in semiconductor hardware suppliers, provided strong intraday tailwinds that accelerated the stock's advance.
Despite the positive momentum, institutional investors continue to balance near-term optimism against longer-term structural risks. Aggressive capital expenditures aimed at expanding high-end packaging facilities risk compressing near-term free cash flow and increasing depreciation burdens. Furthermore, while the packaging and testing divisions demonstrate robust performance, performance in secondary segments such as electronic manufacturing services remains more tempered. Sustained upside will largely depend on the company's ability to maintain high capacity utilization in advanced lines and protect operating margins amid heavy capacity investments.
Technical Analysis of ASE Technology Holding Co Ltd (ASX)
Technically, ASE Technology Holding Co Ltd (ASX) shows a MACD (12,26,9) value of -0.917, indicating a sell signal. The RSI at 47.276 suggests neutral condition and the Williams %R at 45.710 suggests neutral condition. Please monitor closely.
Fundamental Analysis of ASE Technology Holding Co Ltd (ASX)
ASE Technology Holding Co Ltd (ASX) is in the Technology Equipment industry. Its latest annual revenue is $20.71B, ranking 13 in the industry. The net profit is $1.30B, ranking 17 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Strong Buy, with an average price target of $54.94, a high of $58.00, and a low of $51.88.
More details about ASE Technology Holding Co Ltd (ASX)
Company Specific Risks:
- Sequential Top-Line Deceleration and EMS Drag: The unaudited monthly net revenue report filed on November 10, 2026, showed consolidated net sales of NT$88.62 billion, representing a flat sequential increase of just 0.6% (and 0.1% in U.S. dollar terms), underscoring persistent demand stagnation and margin dilution in the Electronic Manufacturing Services division that dampens overall core growth.
- Capital Expenditure Inflation and Fixed-Cost Depreciation Risk: The ongoing expansion of capital investment into advanced packaging and testing infrastructure exposes operating cash flows to elevated execution risks, leaving gross margins highly sensitive to near-term depreciation burdens if high-performance computing chip packaging volume fluctuates.
- Multiple Expansion Overhang and Insider Divestment: Market evaluations over the past 48 to 72 hours noted that the stock trades at an elevated trailing valuation multiple well above its multi-year median, compounded by over $369 million in cumulative insider share selling with no insider purchases, leaving the equity structurally vulnerable to intraday multiple contraction.
- Exposure to Hyperscaler AI Regulatory Restrictions: Recent semiconductor supply chain volatility tied to prospective regulatory curbs on data-center AI hardware buildouts directly threatens forward order flow for high-density advanced packaging, creating downside exposure for outsourced assembly and test volume commitments.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.