


Analog Devices Inc Stock (ADI) Moved Up by 5.08% on Nov 11: What Investors Need To Know


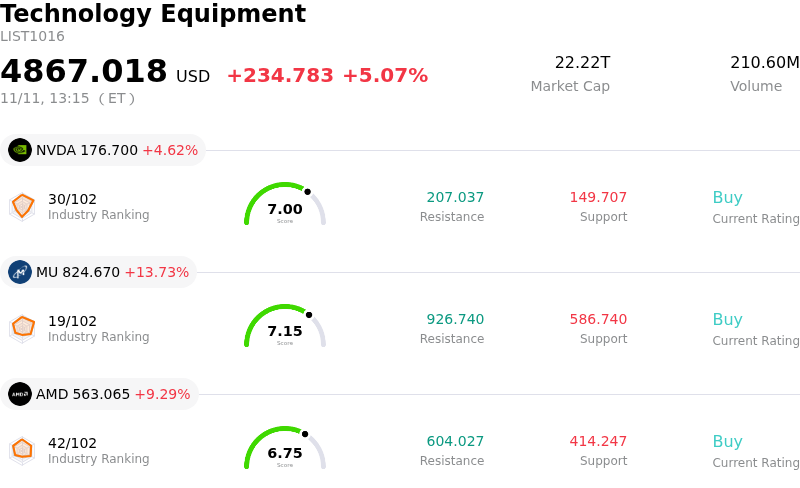
Analog Devices Inc (ADI) moved up by 5.08%. The Technology Equipment sector is up by 5.07%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 4.60%; Micron Technology Inc (MU) up 13.73%; Advanced Micro Devices Inc (AMD) up 9.29%.
What is driving Analog Devices Inc (ADI)’s stock price up today?
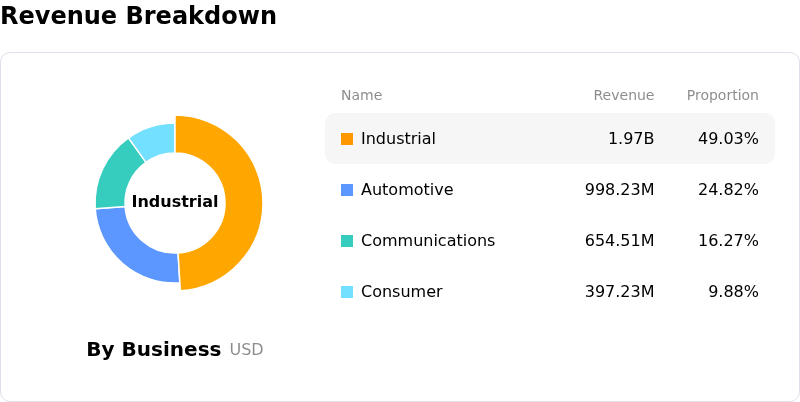
Analog Devices recorded a robust advance during the session, driven by strengthening market confidence in the broader cyclical recovery across analog semiconductors. Investors responded favorably to indicators of stabilizing end-market demand, particularly within the industrial and automotive segments, which represent the core pillars of the company’s revenue base. As channel inventory adjustments across major global customers approach completion, order patterns have begun to normalize, reinforcing expectations that the cyclical trough is firmly in the rearview mirror and setting the stage for steady margin expansion.
Compounding this cyclical momentum is accelerating demand tied to high-performance computing and artificial intelligence infrastructure. While historically characterized by its diversified exposure to mature industrial applications, the company has increasingly captured institutional interest through its mission-critical power management, precision analog, and optical connectivity solutions utilized in next-generation data centers. As hyperscalers and enterprise hardware providers intensify their investments in power-dense computing architectures, the addressable content per server rack and optical module continues to expand, serving as a powerful structural growth catalyst alongside traditional volume recovery.
Positive sentiment across the broader semiconductor peer group also provided constructive momentum. Favorable commentary from related industrial component suppliers and upbeat channel checks across enterprise supply chains have prompted sell-side analysts to reiterate constructive outlooks on high-quality analog chipmakers. Market participants have increasingly favored companies with resilient pricing power, high barriers to entry, and disciplined capacity management, attributes where Analog Devices consistently stands out relative to peers.
From a macro and portfolio allocation perspective, expectations of an accommodating monetary backdrop have renewed institutional appetite for high-cash-flow, capital-efficient technology leaders. With corporate capital expenditure plans gradually firming up and key secular trends in factory automation, clean energy, and vehicle electrification remaining intact, Analog Devices continues to benefit from an attractive risk-reward profile. Sustained operating leverage and disciplined expense execution further bolster investor confidence in the company’s ability to deliver robust free cash flow through the next phase of the industry cycle.
Technical Analysis of Analog Devices Inc (ADI)
Technically, Analog Devices Inc (ADI) shows a MACD (12,26,9) value of -4.111, indicating a neutral signal. The RSI at 54.448 suggests neutral condition and the Williams %R at 25.994 suggests buy condition. Please monitor closely.
Fundamental Analysis of Analog Devices Inc (ADI)
Analog Devices Inc (ADI) is in the Technology Equipment industry. Its latest annual revenue is $11.02B, ranking 18 in the industry. The net profit is $2.27B, ranking 14 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $470.13, a high of $675.00, and a low of $315.00.
More details about Analog Devices Inc (ADI)
Company Specific Risks:
- Analyst Downgrades and Stretched Valuation Multiples: Equities analysts have recently downgraded the stock to Hold from Buy, highlighting that trading multiples well above 40x earnings leave the shares heavily exposed to multiple compression and momentum sell-offs during broader semiconductor pullbacks.
- Industrial and Automotive Cyclical Demand Weakness: Heavy operational exposure to automotive and industrial end-markets exposes the business to synchronized cyclical slowdowns, where deceleration in industrial capex and softer EV production lead to extended customer inventory digestion.
- Intensifying Pricing Pressure from 300mm Fab Expansion: Direct competitor Texas Instruments is actively ramping low-cost 300mm wafer manufacturing capacity, creating aggressive price competition across mid-range industrial and analog power-management sockets that threatens to compress ADI's gross margins.
- Pre-Earnings Guidance Vulnerability: Approaching the fiscal fourth-quarter earnings release, institutional expectations remain priced for aggressive beats in AI data center power products, creating acute intraday downside risk if distributor demand normalization leads to conservative forward guidance.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.