


On Holding AG Stock (ONON) Moved Down by 7.03% on Nov 10: Drivers Behind the Movement


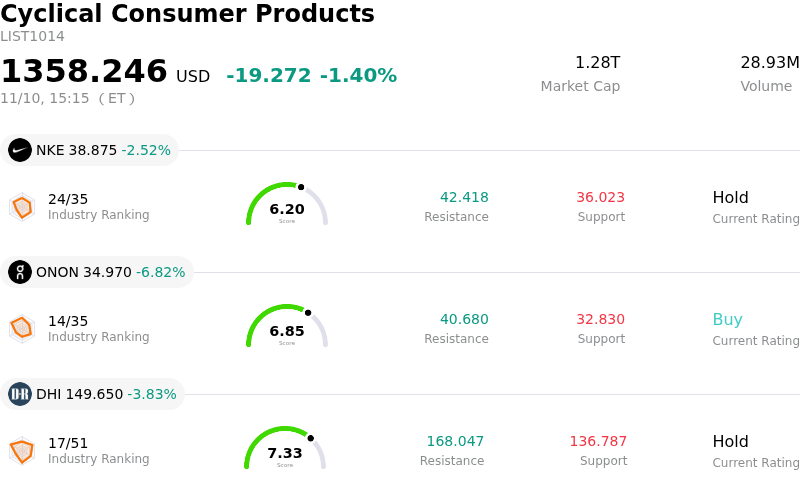
On Holding AG (ONON) moved down by 7.03%. The Cyclical Consumer Products sector is down by 1.40%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Nike Inc (NKE) down 2.52%; On Holding AG (ONON) down 6.82%; DR Horton Inc (DHI) down 3.83%.
What is driving On Holding AG (ONON)’s stock price down today?
On Holding shares experienced notable downward pressure following the release of its third-quarter financial results. Despite delivering a bottom-line beat on earnings per share and generating record quarterly net sales, the market reaction turned decisively negative as investors zeroed in on top-line performance that merely matched consensus forecasts rather than providing the substantial upside typically required to sustain high-multiple growth equities.
The primary catalyst behind the retreat centers on the company's forward guidance and the underlying cadence of sales expansion. While management raised its full-year gross margin target, it chose to leave its constant-currency net sales growth projection unchanged for the full year. For institutional market participants anticipating an upward revision heading into the peak holiday season, the maintained outlook implies a potential sequential moderation in top-line trajectory, pointing to lingering caution within the wholesale channel and a competitive, promotional retail backdrop in key footwear markets.
Quality of earnings and balance sheet metrics also attracted heightened scrutiny. Although reported gross margins exhibited sharp expansion, a meaningful component of this profitability enhancement was aided by non-recurring tariff refunds rather than purely structural operational efficiency. At the same time, an elevated year-over-year increase in inventory levels stoked concerns about working capital management and the potential need for promotional activity if holiday sell-through fails to match optimistic direct-to-consumer targets.
Finally, the intraday weakness reflects valuation readjustment and position de-risking. Carrying a premium valuation relative to broader apparel and athletic footwear peers leaves little margin for error on top-line metrics. The combination of an in-line revenue delivery, an unrevised top-line outlook, and inventory overhang prompted fast-money and growth-focused funds to trim exposure, driving multiple compression despite robust underlying brand demand.
Technical Analysis of On Holding AG (ONON)
Technically, On Holding AG (ONON) shows a MACD (12,26,9) value of 0.207, indicating a buy signal. The RSI at 52.226 suggests neutral condition and the Williams %R at 53.248 suggests neutral condition. Please monitor closely.
Fundamental Analysis of On Holding AG (ONON)
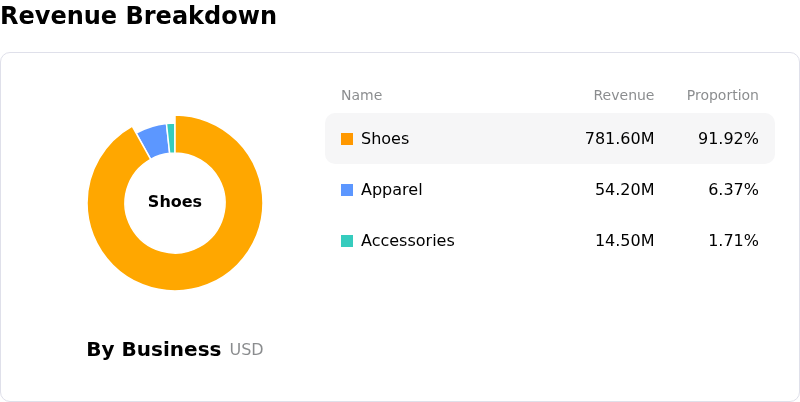
On Holding AG (ONON) is in the Cyclical Consumer Products industry. Its latest annual revenue is $3.86B, ranking 12 in the industry. The net profit is $260.65M, ranking 10 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $45.29, a high of $73.00, and a low of $24.69.
More details about On Holding AG (ONON)
Company Specific Risks:
- Unchanged Full-Year Revenue Guidance Despite Q3 Beat: Despite delivering record third-quarter net sales of CHF 931.4 million ($1.14 billion), management merely reiterated its full-year constant-currency revenue growth target in the low-20% range rather than raising it, sparking intraday selling among growth investors who expected upward guidance revisions to justify the stock's premium valuation.
- Margin Quality Distorted by Non-Recurring Tariff Refunds: Headline Q3 gross margin surged to a record 72.6%, but approximately 570 basis points of that expansion was driven by a temporary $64 million U.S. tariff refund; excluding this one-time windfall, normalized gross margin stood at 66.9% and underlying adjusted EBITDA margin guidance remained unchanged at 19.5%–20.0%, masking stagnant core operational leverage.
- Channel Imbalance and Lingering Wholesale Softness: Revenue growth is increasingly skewed toward direct-to-consumer channels (up 25.0%), while wholesale distribution faces ongoing deceleration and conservative ordering patterns from North American retailers, limiting broader market penetration and exposing the business to direct marketing and store-fleet overheads.
- High Valuation Multiple Vulnerability: Because the stock commands an aggressive growth multiple relative to legacy sportswear incumbents, any sustained top-line slowdown toward high-teens growth leaves equity valuation highly susceptible to sharp multiple compression amid an increasingly promotional footwear backdrop.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.