


Wheaton Precious Metals Corp Stock (WPM) Moved Down by 5.11% on Nov 10: Drivers Behind the Movement


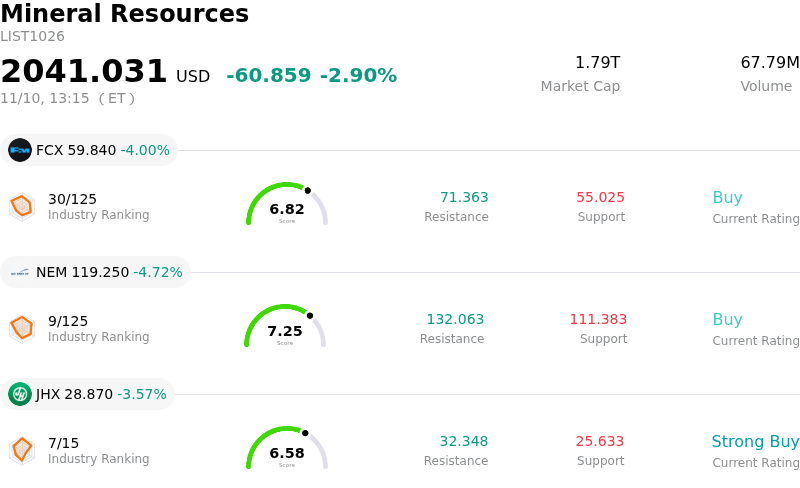
Wheaton Precious Metals Corp (WPM) moved down by 5.11%. The Mineral Resources sector is down by 2.90%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Freeport-McMoRan Inc (FCX) down 4.00%; Newmont Corporation (NEM) down 4.72%; James Hardie Industries PLC (JHX) down 3.57%.
What is driving Wheaton Precious Metals Corp (WPM)’s stock price down today?
Wheaton Precious Metals experienced sharp downward pressure, primarily tracking broad declines across the precious metals complex. Spot gold and silver prices retreated as a strengthening U.S. dollar and elevated benchmark Treasury yields heightened the opportunity cost of holding non-yielding assets. Given Wheaton's direct leverage to underlying commodity prices through its streaming agreements, softening bullion markets triggered immediate defensive positioning and broad-based selling across precious metal equities.
Compounding the macroeconomic headwinds, investors continued to digest the company's third-quarter financial and operational results. Although top-line revenue expanded significantly alongside higher realized metal prices, adjusted earnings per share narrowly missed consensus projections. Market participants also scrutinized asset-level production metrics, noting softer attributable gold production stemming from grade sequencing at the Salobo mine and the cessation of mining at the higher-grade Pampacancha pit within Constancia. These mine-specific transitions underscored near-term volume headwinds, tempering enthusiasm surrounding immediate operational momentum.
Institutional sentiment was further dampened by tactical profit-taking following an extended advance across the streaming and royalty segment. As safe-haven demand cooled and macroeconomic crosscurrents drove capital toward yield-bearing assets, portfolio managers trimmed exposure to cyclical resource equities. Because Wheaton trades at a valuation premium relative to conventional mining operators due to its superior operating margin profile, the stock remains particularly vulnerable to multiple compression whenever underlying commodity prices undergo consolidation.
Despite the intraday contraction, Wheaton retains sound long-term fundamentals anchored by its low-cost streaming business model, absence of direct mine operating cost inflation, and robust free cash flow generation. While near-term share price behavior will remain closely tethered to U.S. dollar trajectory and precious metal pricing dynamics, the medium-term thesis remains supported by a fully funded portfolio and prospective volume expansion as newly acquired and development-stage streaming assets advance toward commercial production.
Technical Analysis of Wheaton Precious Metals Corp (WPM)
Technically, Wheaton Precious Metals Corp (WPM) shows a MACD (12,26,9) value of 4.786, indicating a neutral signal. The RSI at 54.443 suggests neutral condition and the Williams %R at 28.058 suggests buy condition. Please monitor closely.
Fundamental Analysis of Wheaton Precious Metals Corp (WPM)
Wheaton Precious Metals Corp (WPM) is in the Mineral Resources industry. Its latest annual revenue is $2.31B, ranking 39 in the industry. The net profit is $1.47B, ranking 15 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $176.58, a high of $250.00, and a low of $150.00.
More details about Wheaton Precious Metals Corp (WPM)
Company Specific Risks:
- Earnings and Revenue Consensus Miss: Third-quarter financial results revealed that adjusted earnings per share of $0.90 fell short of the $0.91 consensus estimate, while quarterly revenue of $772 million missed consensus projections of $806 million, prompting institutional target revisions including UBS trimming its price target to $155.
- Asset-Level Operational Headwinds and Grade Compression: Attributable gold production at the flagship Salobo stream declined 2% year-over-year after operational delays forced mining into lower-grade pit sequencing, leaving full-year production targets heavily dependent on an aggressive fourth-quarter rebound, alongside management's confirmation of sharp silver output reductions at Peñasquito continuing into 2027.
- Leverage Burden and Cash Outflow from Upfront Stream Acquisitions: Heavy upfront capital commitments—led by the $4.3 billion Antamina silver stream agreement—pushed the company into a $1.5 billion net debt position with $1.6 billion in debt obligations, depleting cash and cash equivalents to $146 million and temporarily pressuring free cash flow generation.
- Narrowing Pipeline for Accretive Streaming Transactions: Disclosures from executive management highlighted that the active transaction pipeline has compressed from roughly twenty viable streaming targets to just over a dozen, stoking institutional concern that opportunities for accretive, long-life asset additions are diminishing amid elevated valuation benchmarks.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.