


Arm Holdings PLC Stock (ARM) Moved Down by 4.50% on Nov 10: What Investors Need To Know


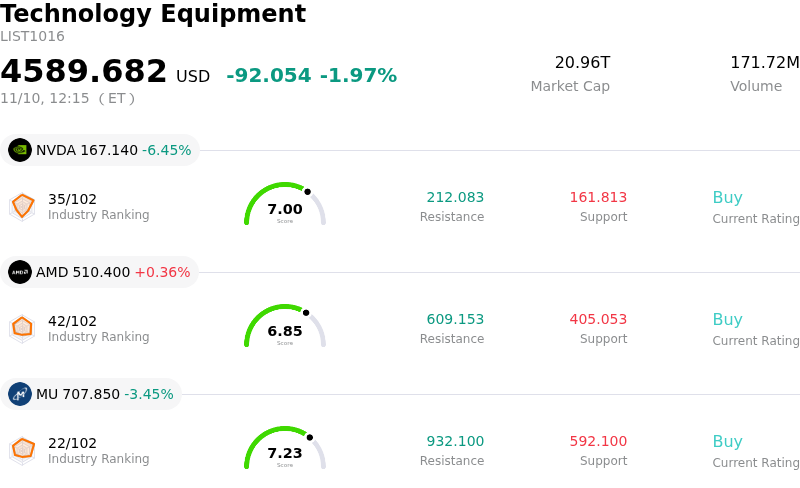
Arm Holdings PLC (ARM) moved down by 4.50%. The Technology Equipment sector is down by 1.97%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 6.39%; Advanced Micro Devices Inc (AMD) up 0.36%; Micron Technology Inc (MU) down 3.45%.
What is driving Arm Holdings PLC (ARM)’s stock price down today?
Arm Holdings experienced notable downward pressure as institutional investors continued to digest the underlying composition of the company's recent quarterly financial results and conservative near-term guidance. While headline revenue and adjusted earnings initially surpassed Wall Street consensus, a deeper look into the revenue streams triggered a repricing of the stock's growth trajectory.
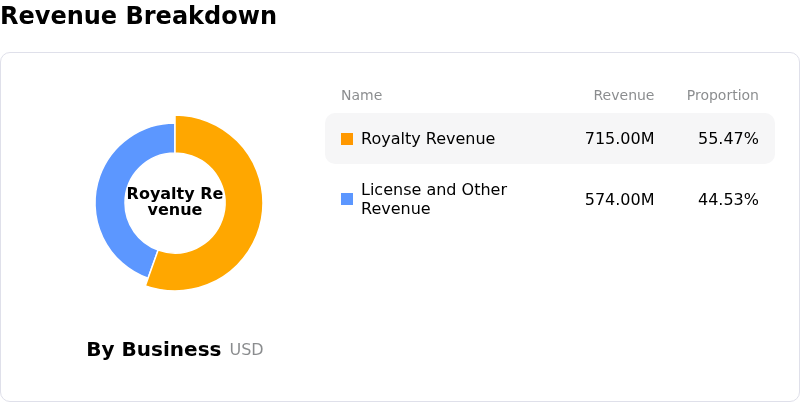
The primary catalyst behind the selling pressure is the pronounced divergence between licensing fees and royalty revenue. While licensing outperformed expectations, it is historically lumpy, unpredictable, and dependent on the timing of large customer agreements. In contrast, royalty revenue, which reflects recurring revenue from actual end-market chip shipments and serves as a vital barometer of high-margin recurring cash flows, missed analyst forecasts. This shortfall underscored ongoing volume stagnation in the broader consumer electronics and smartphone sectors, where elevated memory costs and cautious OEM inventory strategies have constrained device build rates.
Investor sentiment was further dampened by forward guidance that merely met or slightly edged past consensus projections. Given that Arm trades at a substantial valuation premium relative to semiconductor and intellectual property peers, institutional market participants required a more decisive beat-and-raise trajectory to support its multiples. The absence of an upward revision for royalty growth raised questions regarding the pace at which next-generation architectural transitions and artificial intelligence edge adoption can offset sluggish legacy handset demand.
Wall Street response has reflected this increased caution, with several investment banks adjusting price targets downward and pointing to cyclical vulnerability in non-cloud end markets. Analysts also flagged potential concentration risks in licensing agreements, especially those involving related parties. In parallel, lingering legal overhangs surrounding key architecture licensing disputes have kept risk premiums elevated.
Finally, broader macroeconomic dynamics and sector-wide profit-taking across high-multiple semiconductor assets added to intraday volatility. Elevated market sensitivity to interest rate expectations and tech sector rotations exacerbated the sell-off as institutional funds trimmed exposure to high-beta, premium-multiple hardware names in favor of more defensively valued assets. Together, the deceleration in recurring royalty momentum and an unforgiving valuation backdrop drove the stock lower on the session.
Technical Analysis of Arm Holdings PLC (ARM)
Technically, Arm Holdings PLC (ARM) shows a MACD (12,26,9) value of -5.620, indicating a sell signal. The RSI at 34.351 suggests neutral condition and the Williams %R at 80.495 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Arm Holdings PLC (ARM)
Arm Holdings PLC (ARM) is in the Technology Equipment industry. Its latest annual revenue is $4.92B, ranking 24 in the industry. The net profit is $904.00M, ranking 18 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $0.00, a high of $0.00, and a low of $0.00.
More details about Arm Holdings PLC (ARM)
Company Specific Risks:
- Royalty Revenue Deceleration and Smartphone Exposure: Recent quarterly royalty revenue expanded by only 8% year-over-year to $670 million, missing institutional consensus estimates of roughly $721 million as elevated memory component costs and broader smartphone demand softness triggered sequential contractions in mobile royalties.
- Subdued Forward Guidance and Operating Margin Squeeze: Fiscal third-quarter revenue guidance ($1.54 billion) and adjusted EPS forecasts ($0.56) failed to clear elevated growth hurdles, while projected adjusted operating expenses jumped to $825 million, prompting institutional analysts to trim price targets over expected near-term margin compression.
- High-Stakes Qualcomm Architectural Litigation: The ongoing legal battle regarding Qualcomm's architectural licensing rights represents a severe legal overhang, posing direct threats of contract cancellation, reduced royalty collection rates, or disrupted commercial relationships with a key customer.
- Multiple Contraction Exposure and SoftBank Collateral Risk: The company's elevated valuation multiple leaves shares acutely sensitive to broad semiconductor de-risking, compounded by majority shareholder SoftBank's billions in margin loans collateralized against its Arm equity stake.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.