


Intel Corp Stock (INTC) Moved Down by 3.31% on Nov 10: Facts Behind the Movement


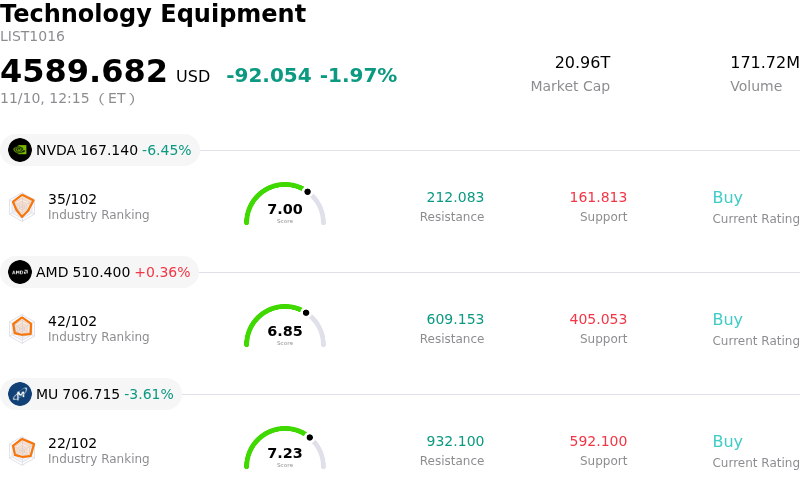
Intel Corp (INTC) moved down by 3.31%. The Technology Equipment sector is down by 1.97%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 6.40%; Advanced Micro Devices Inc (AMD) up 0.36%; Micron Technology Inc (MU) down 3.61%.
What is driving Intel Corp (INTC)’s stock price down today?
Intel experienced pronounced downward pressure and elevated intraday volatility as market sentiment turned cautious following recent relief gains across the semiconductor sector. Investors continue to digest structural headwinds highlighted in the company’s forward guidance, particularly prolonged weakness across the personal computer market. Management’s outlook suggests client computing revenue faces ongoing contraction through early next year as original equipment manufacturers work through existing inventory, directly depressing factory utilization rates and diluting gross margins.
Compounding top-line concerns, operational disruptions have created near-term supply frictions. A manufacturing setback at the Fab 28 facility in Israel has restricted production output, introducing multi-hundred-million-dollar headwinds to current-quarter revenue and exerting additional downward pressure on operating margins. While enterprise and cloud demand for Xeon server processors remains healthy, these localized fab constraints have prevented the company from fully capitalizing on data center momentum.
Institutional investors also remain acutely focused on the heavy capital requirements and ongoing operating deficits within the Intel Foundry segment. Despite technical milestones in advancing leading-edge process nodes and bringing advanced packaging solutions to market, the foundry business continues to absorb substantial quarterly losses. Market skepticism persists regarding the timeline for commercial monetization, as large institutional allocators seek concrete commercial commitments and high-volume design wins from external tier-one customers before fully underwriting the multi-year manufacturing roadmap.
Broader sector dynamics further accelerated intraday selling. Following a sharp rebound in broader chipmaker valuations in preceding sessions, fast-money participants engaged in profit-taking amid rising macroeconomic scrutiny over hyperscaler capital expenditure and intensifying competition from rival x86 and custom silicon architectures. Until operational execution stabilizes and external customer adoption provides visibility into foundry profitability, Intel’s valuation remains highly vulnerable to heightened volatility and cautious institutional positioning.
Technical Analysis of Intel Corp (INTC)
Technically, Intel Corp (INTC) shows a MACD (12,26,9) value of -4.682, indicating a sell signal. The RSI at 28.469 suggests sell condition and the Williams %R at 86.778 suggests oversold condition. Please monitor closely.
Media Coverage of Intel Corp (INTC)
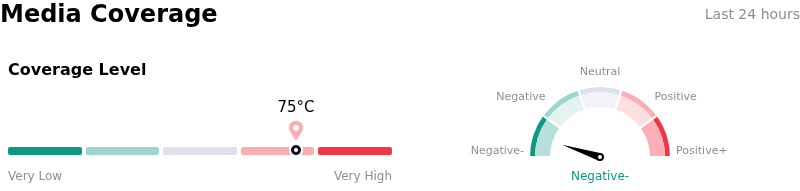
In terms of media coverage, Intel Corp (INTC) shows a coverage score of 75, indicating a high level of media attention. The overall market sentiment index is currently in extremely bearish zone.
Fundamental Analysis of Intel Corp (INTC)
Intel Corp (INTC) is in the Technology Equipment industry. Its latest annual revenue is $52.85B, ranking 6 in the industry. The net profit is $-267.00M, ranking 111 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $91.99, a high of $160.00, and a low of $63.00.
More details about Intel Corp (INTC)
Company Specific Risks:
- Heightened Political and Regulatory Scrutiny: Following recent U.S. election developments, scrutiny over federal equity stakes and CHIPS Act capital distributions has intensified, exposing Intel to potential congressional hearings and regulatory reviews concerning its state-backed subsidies and foundry timelines.
- Operational Disruptions at Kiryat Gat Fab 28: Production fallout from an operational accident at the Fab 28 facility in Israel continues to impair output, creating an estimated $300 million top-line headwind and an immediate 200-basis-point drag on gross margins that is projected to linger into 2027.
- Severe Gross Margin Compression and Guidance Cuts: Fourth-quarter forward guidance projects gross margins deteriorating to 38%—down from 44.1% in the prior quarter—and EPS plunging to $0.25 (well below the $0.43 consensus) due to persistent client PC market weakness and elevated component costs.
- Emerging Securities Class Actions and Disclosure Probes: Multiple legal firms have formally initiated shareholder investigations and class-action inquiries into whether prior disclosures adequately represented severe foundry operational losses, persistent supply constraints, and multi-year negative free cash flow risks.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.