


Southern Copper Corp Stock (SCCO) Moved Down by 3.23% on Nov 10: Drivers Behind the Movement


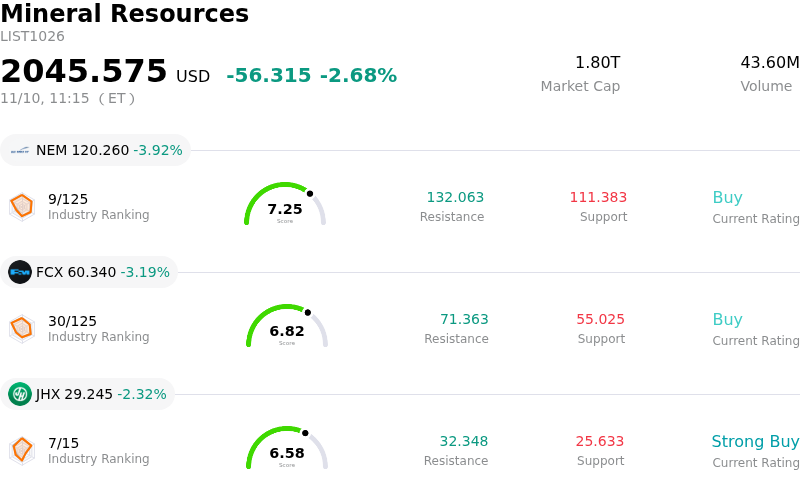
Southern Copper Corp (SCCO) moved down by 3.23%. The Mineral Resources sector is down by 2.68%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Newmont Corporation (NEM) down 4.08%; Freeport-McMoRan Inc (FCX) down 3.37%; James Hardie Industries PLC (JHX) down 2.32%.
What is driving Southern Copper Corp (SCCO)’s stock price down today?
Southern Copper Corporation is facing downward pressure primarily driven by weakness across the global base metals complex. As an integrated pure-play copper producer with vast reserves in Mexico and Peru, the company's valuation remains exceptionally sensitive to front-month copper contracts on the London Metal Exchange and COMEX. A broader retrenchment in industrial metal pricing, compounded by persistent uncertainty surrounding manufacturing momentum and property sector stabilization in China, has weighed heavily on global demand expectations. When benchmark copper prices retreat, high-beta equities in the materials space invariably experience pronounced institutional selling pressure.
Macroeconomic headwinds are further exacerbated by currency and rates dynamics. A resilient U.S. dollar elevates the effective cost of dollar-denominated commodities for overseas buyers, dampening physical demand and reinforcing a risk-off posture across cyclical assets. Simultaneously, sustained yields on global sovereign debt continue to raise the discount rates applied to long-duration resource projects. This macro backdrop has prompted multi-asset funds and commodity-focused strategies to trim exposure to cyclical industrial equities, reducing portfolio allocations to major miners.
Operational and jurisdiction-specific realities also amplify intraday volatility for the company. While Southern Copper maintains an industry-leading position on the global cash cost curve, market participants remain mindful of inflationary pressures on mining inputs, including labor, energy, and maintenance capital expenditures. Furthermore, operating assets in Latin America inherently carry exposure to shifting regulatory frameworks, permitting scrutiny, and local community negotiations. Any perceived friction regarding production expansion timelines or capital allocation updates encourages investors to de-risk.
From an institutional perspective, the current retreat reflects a broader sector-wide recalibration rather than structural deterioration in long-term fundamentals. While the secular tailwinds tied to grid modernization, renewable infrastructure, and electric mobility continue to underpin the multi-year structural thesis for refined copper, near-term capital flows remain tightly tethered to physical spot market sentiment and macroeconomic indicators. Institutional investors will likely remain cautious until tangible evidence of inventory drawdowns and clearer demand catalysts emerge across key consumer markets.
Technical Analysis of Southern Copper Corp (SCCO)
Technically, Southern Copper Corp (SCCO) shows a MACD (12,26,9) value of -3.224, indicating a sell signal. The RSI at 37.809 suggests neutral condition and the Williams %R at 73.800 suggests sell condition. Please monitor closely.
Fundamental Analysis of Southern Copper Corp (SCCO)
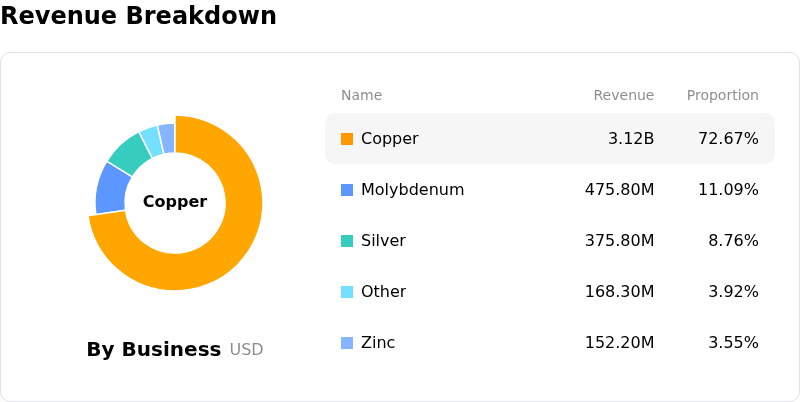
Southern Copper Corp (SCCO) is in the Mineral Resources industry. Its latest annual revenue is $13.42B, ranking 16 in the industry. The net profit is $4.33B, ranking 6 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $173.06, a high of $272.12, and a low of $136.60.
More details about Southern Copper Corp (SCCO)
Company Specific Risks:
- Execution Delays at Tía María Project: Commercial startup of the flagship Tía María copper project has officially slipped into the first half of 2028, with management postponing updated capital expenditure budgets and comprehensive 2027 output guidance until early next year, curbing near-term volume catalysts and prolonging capital deployment uncertainty.
- Declining Ore Grades and Peruvian Output Contraction: Deteriorating ore grades across key Peruvian mining assets have driven a steep quarterly contraction exceeding 6% in regional copper output, raising extraction costs and dampening overall volume throughput despite favorable baseline commodity spot pricing.
- Stretched Valuation Premium Amid Widespread Analyst Downgrades: Trading at roughly 14x forward EV/EBITDA and over 22x P/E, the stock commands a significant valuation premium over diversified mining peers, sustaining a consensus "Reduce" rating across institutional sell-side desks that warn high copper realization assumptions leave negligible room for execution error.
- Heightened Exposure to Peruvian Sovereign and Regulatory Uncertainty: Heavy revenue and reserve concentration in Peru exposes operations to intensifying political volatility and community scrutiny ahead of upcoming elections, creating recurring overhangs around mining concessions, royalty structures, and environmental permits.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.