


Dell Technologies Inc Stock (DELL) Moved Down by 3.56% on Nov 10: What Investors Need To Know


Dell Technologies Inc (DELL) moved down by 3.56%. The Technology Equipment sector is down by 1.17%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 5.00%; Advanced Micro Devices Inc (AMD) up 3.92%; Micron Technology Inc (MU) down 2.10%.
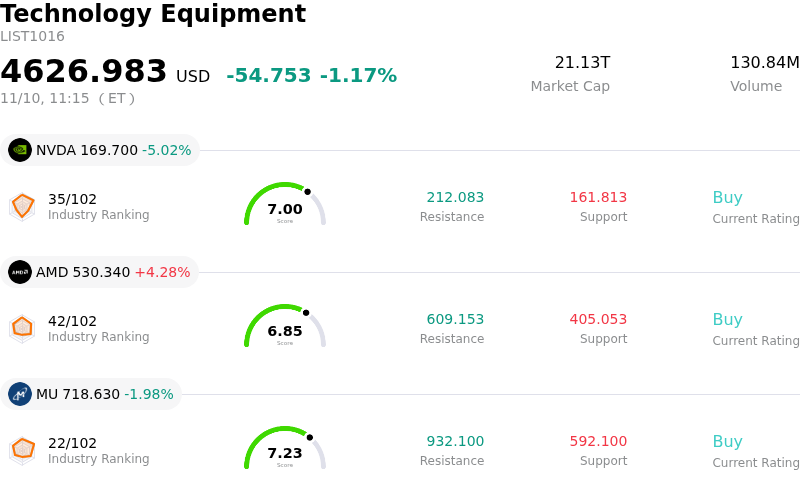
What is driving Dell Technologies Inc (DELL)’s stock price down today?
Dell Technologies experienced noticeable downward pressure during the session, driven by broad-based retrenchment across the artificial intelligence hardware ecosystem and mounting investor sensitivity toward data center capital expenditure sustainability. The broader technology sector faced selling pressure as institutional investors trimmed exposure to high-multiple infrastructure names, weighing on enterprise server and storage suppliers across the board.
A primary catalyst dampening sentiment stems from emerging regulatory and political scrutiny surrounding rapid data center expansion. Reports of potential construction pauses and increased utility oversight in key regional hubs have raised questions regarding the execution timeline for hyperscaler capacity buildouts. Given that Dell’s recent growth narrative and valuation re-rating have been heavily tied to accelerating AI server shipments, any perceived friction in data center deployment pipelines prompts swift institutional de-risking.
Compounding these sector-level concerns is ongoing margin anxiety ahead of the company’s upcoming quarterly financial report. While order velocity for specialized compute servers remains elevated, the market continues to scrutinize the profitability profile of AI racks relative to traditional enterprise storage and general-purpose servers. Tight supplies and elevated costs for high-bandwidth memory and associated advanced components have heightened fears of gross margin dilution and working capital strain, leaving investors cautious about how efficiently top-line backlog translates into free cash flow.
Simultaneously, lingering headwinds in the personal computing segment continue to cap near-term optimism. Subdued enterprise refresh activity and persistent cost pressures across the commercial PC supply chain have delayed the anticipated recovery in the Client Solutions Group. With client computing still representing a meaningful portion of operating earnings, softness in traditional hardware amplifies the stock's vulnerability during broader market pullbacks, keeping market participants defensive until management delivers clearer updates on margin trajectory and cash conversion.
Technical Analysis of Dell Technologies Inc (DELL)
Technically, Dell Technologies Inc (DELL) shows a MACD (12,26,9) value of -25.418, indicating a sell signal. The RSI at 31.410 suggests neutral condition and the Williams %R at 90.431 suggests oversold condition. Please monitor closely.
Media Coverage of Dell Technologies Inc (DELL)
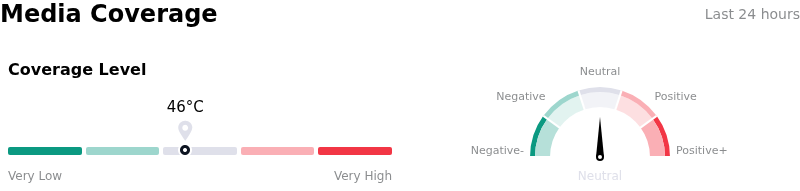
In terms of media coverage, Dell Technologies Inc (DELL) shows a coverage score of 46, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Dell Technologies Inc (DELL)
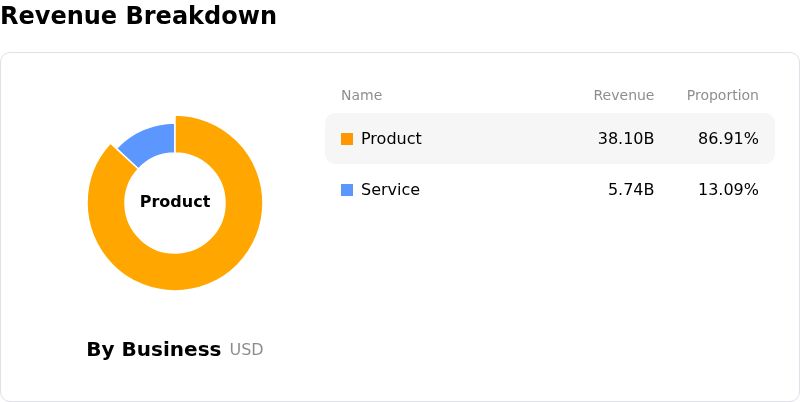
Dell Technologies Inc (DELL) is in the Technology Equipment industry. Its latest annual revenue is $113.54B, ranking 2 in the industry. The net profit is $5.94B, ranking 4 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $588.12, a high of $700.00, and a low of $499.80.
More details about Dell Technologies Inc (DELL)
Company Specific Risks:
- AI Server Revenue Quality and Margin Compression: Institutional downgrades and recent analyst scrutiny emphasize that top-line growth in Dell's Infrastructure Solutions Group is disproportionately driven by pass-through cost inflation from rising memory and component prices rather than organic enterprise AI adoption, leaving operating margins vulnerable to contraction as component costs normalize.
- Neocloud Customer Concentration and Backlog Conversion Risk: A heavy concentration of Dell's AI server order backlog relies on debt-reliant neoclouds and specialized cloud service providers, where rising capital costs and credit strain among key buyers introduce elevated default, deferral, and cancellation risks on contracted deliveries.
- Working Capital Strain and Cash Flow Conversion Pressure: Massive capital absorption required to procure high-cost GPU inventory and carry customer financing receivables for enterprise server deployments has severely constrained quarterly free cash flow, threatening debt reduction commitments and liquidity flexibility.
- Client Solutions Group Hardware Softness: Cautious forecasts across semiconductor partners and enterprise IT hardware peers indicate prolonged sluggishness in corporate PC refresh cycles, dampening commercial shipment recovery and threatening revenue targets in Dell's core Client Solutions Group.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.