


ASE Technology Holding Co Ltd Stock (ASX) Moved Up by 6.32% on Nov 10: What Signal Does It Send?


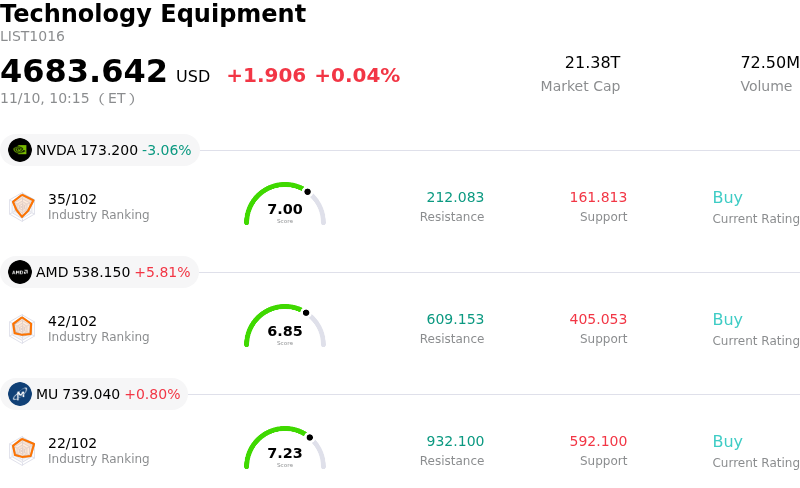
ASE Technology Holding Co Ltd (ASX) moved up by 6.32%. The Technology Equipment sector is up by 0.04%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 2.96%; Advanced Micro Devices Inc (AMD) up 5.58%; Micron Technology Inc (MU) up 0.94%.
What is driving ASE Technology Holding Co Ltd (ASX)’s stock price up today?
ASE Technology Holding experienced solid upward momentum following the release of its robust unaudited monthly revenue report for October. The disclosure confirmed accelerating operational momentum, underscored by substantial year-over-year top-line expansion and sustained sequential growth. Investors reacted favorably to clear evidence that the company's high-volume semiconductor assembly and test operations are maintaining elevated utilization rates, offering concrete proof that fourth-quarter operational momentum remains firmly on track.
The primary engine behind this outperformance was the Assembly, Testing, and Material business segment, which delivered notable expansion. Surging demand across artificial intelligence accelerators, high-performance computing platforms, and heterogeneous chip integration has created sustained tightness in advanced packaging capacity across the semiconductor supply chain. As premier foundries and fabless semiconductor designers increasingly leverage leading outsourced semiconductor assembly and test partners to mitigate packaging bottlenecks, ASE Technology continues to benefit from an improved product mix and favorable blended pricing power. The revenue figures reinforced market confidence in management's upwardly revised targets for advanced packaging and testing solutions.
Institutional sentiment was further bolstered by broader thematic positioning within global semiconductor equities. Portfolio managers seeking direct beneficiaries of artificial intelligence infrastructure spending at attractive relative valuations viewed the company as a key beneficiary of structural back-end capex and outsourcing trends. Positive order flow and supportive analyst expectations around margin defense and operational leverage helped drive intraday accumulation, reflecting conviction that packaging and testing providers are capturing an expanding share of total semiconductor value.
Looking ahead, institutional investors will closely track execution against raised capital expenditure budgets, capacity deployment timelines for next-generation packaging lines, and fourth-quarter margin metrics. Potential upside catalysts include continued volume spillover from leading-edge foundries and high-bandwidth memory integration. Conversely, key downside risks to monitor encompass broader macroeconomic cyclicality in mature consumer electronics, foreign exchange volatility, and geopolitical developments impacting cross-border semiconductor supply chains. Overall, the day's advance underscores market validation of the company's critical role and expanding earnings leverage within the advanced packaging ecosystem.
Technical Analysis of ASE Technology Holding Co Ltd (ASX)
Technically, ASE Technology Holding Co Ltd (ASX) shows a MACD (12,26,9) value of -1.483, indicating a sell signal. The RSI at 44.520 suggests neutral condition and the Williams %R at 54.257 suggests neutral condition. Please monitor closely.
Fundamental Analysis of ASE Technology Holding Co Ltd (ASX)
ASE Technology Holding Co Ltd (ASX) is in the Technology Equipment industry. Its latest annual revenue is $20.71B, ranking 13 in the industry. The net profit is $1.30B, ranking 17 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Strong Buy, with an average price target of $54.94, a high of $58.00, and a low of $51.88.
More details about ASE Technology Holding Co Ltd (ASX)
Company Specific Risks:
- Sequential Revenue Stagnation Across Core Divisions: The unaudited monthly revenue disclosure filed on November 10, 2026, revealed that consolidated October revenue increased just 0.6% sequentially (0.1% in U.S. dollar terms), reflecting significant top-line stagnation and margin drag in the Electronic Manufacturing Services (EMS) division that offset gains in the packaging unit.
- Cash Flow Squeeze from Surging Capital Expenditures: Management's raised 2026 capital expenditure target of $11.5 billion to fund 22 building projects has pushed equipment spending beyond quarterly EBITDA, significantly compressing free cash flow margins and elevating financial risk if advanced packaging adoption slows.
- Physical Space and Tooling Bottlenecks Restricting LEAP Ramp: Recent institutional reviews of the company's manufacturing pipeline emphasize that physical facility space and specialized equipment lead times have become critical operational bottlenecks, constraining the company's ability to fulfill backlogged demand for Large-Area Enhanced Advanced Packaging (LEAP).
- Valuation Multiples and Substantial Insider Divestment: Market analysts highlighted a pronounced valuation overhang as the stock trades at elevated trailing multiples and high beta, amplified by disclosures indicating $369.7 million in cumulative insider share liquidations over the past twelve months with zero recorded insider purchases.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.