


Newmont Corporation Stock (NEM) Opened Down by 4.06% on Nov 10: What Investors Need To Know


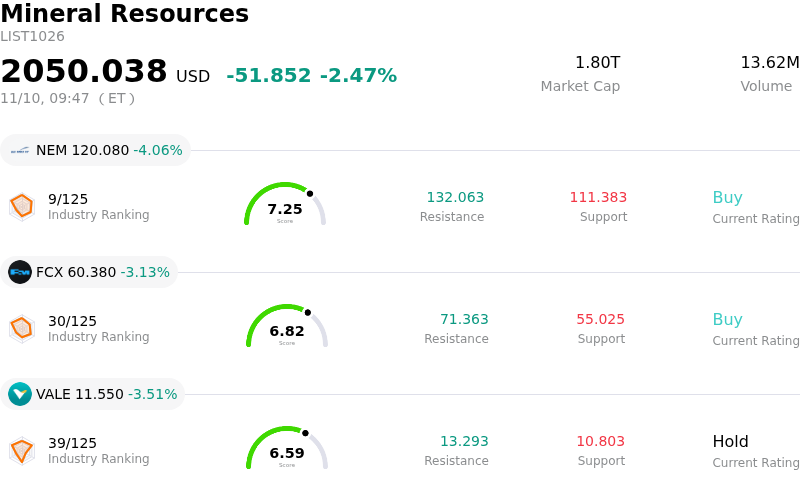
Newmont Corporation (NEM) opened down by 4.06%. The Mineral Resources sector is down by 2.47%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Newmont Corporation (NEM) down 4.06%; Freeport-McMoRan Inc (FCX) down 3.13%; Vale SA (VALE) down 3.51%.
What is driving Newmont Corporation (NEM)’s stock price down today?
Newmont Corporation experienced downward pressure during today's trading session, driven primarily by a confluence of softening underlying bullion prices, macroeconomic headwinds, and investor reassessments of mining cost structures. As the world's largest gold producer, Newmont maintains high operational beta to the price of physical gold, making its equity particularly vulnerable to shifts in precious metal market sentiment and broader interest rate expectations.
A primary catalyst for the decline stems from macroeconomic pressure on commodity markets. Renewed strength in the U.S. dollar, alongside an uptick in benchmark U.S. Treasury yields, has dampened investor appetite for non-yielding bullion. Because gold trades inversely to real yields and the greenback, the intraday retreat in physical gold contracts triggered direct selling across the senior gold mining cohort. Mining equities typically magnify movements in the underlying metal due to operating leverage, causing Newmont to trade lower as bullion prices lost momentum.
Beyond the immediate macroeconomic landscape, persistent market sensitivity toward operational expenditure continues to weigh on investor sentiment. Gold miners remain under scrutiny regarding all-in sustaining costs, where inflationary pressures across labor, energy, and consumables have historically squeezed free cash flow conversion. While Newmont continues to execute on its portfolio optimization and post-acquisition integration initiatives, institutional investors remain cautious about execution risks, production targets across tier-one jurisdictions, and capital allocation discipline. Any perceived pause in margin expansion prompts immediate profit-taking from market participants.
Institutional positioning and sector-wide asset allocation shifts have further amplified the stock's retreat. Following periods of heightened defensive demand, systematic funds and discretionary managers frequently trim precious metal allocations in favor of broader risk assets or cash equivalents when currency headwinds accelerate. This systematic rebalancing has created an unfavorable liquidity backdrop for large-cap materials names.
Looking forward, Newmont's near-term performance remains closely tied to the trajectory of physical gold and global monetary policy expectations. Until yields stabilize and clarity emerges around the pace of cost containment and asset divestiture proceeds, the shares are likely to remain susceptible to heightened volatility. Institutional investors will closely monitor upcoming production updates and cost guidance to evaluate whether cash flow generation can withstand commodity price fluctuations.
Technical Analysis of Newmont Corporation (NEM)
Technically, Newmont Corporation (NEM) shows a MACD (12,26,9) value of 2.944, indicating a neutral signal. The RSI at 55.047 suggests neutral condition and the Williams %R at 31.313 suggests buy condition. Please monitor closely.
Fundamental Analysis of Newmont Corporation (NEM)
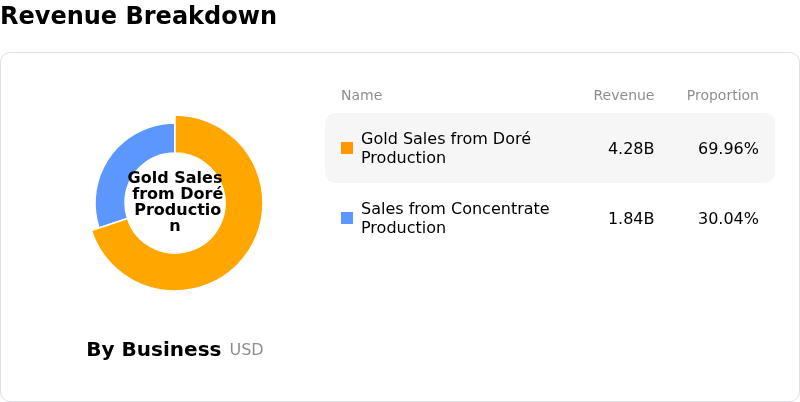
Newmont Corporation (NEM) is in the Mineral Resources industry. Its latest annual revenue is $22.67B, ranking 10 in the industry. The net profit is $7.08B, ranking 3 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $139.25, a high of $205.00, and a low of $79.00.
More details about Newmont Corporation (NEM)
Company Specific Risks:
- Projected Surge in Fourth-Quarter All-In Sustaining Costs: Management's outlook indicates that fourth-quarter All-In Sustaining Costs (AISC) will jump sharply to approximately $1,900 per ounce compared to $1,454 per ounce in the third quarter, driven by the timing of sustaining capital expenditures, input cost inflation, and higher fuel expenses, threatening steep near-term operating margin compression.
- Co-Product Volume Deterioration at Peñasquito: Silver output at the Peñasquito mine is projected to drop by roughly 30% to 50% relative to prior-quarter levels, significantly reducing essential co-product credits that previously offset cash costs and creating immediate upward pressure on unit cost structures.
- Imminent $1.95 Billion Nevada Joint Venture Cash Drain: Newmont faces a designated fourth-quarter cash outflow of approximately $1.95 billion to Barrick under the amended Nevada Gold Mines joint venture agreement, which will substantially reduce immediate liquid cash reserves ahead of planned development ramps.
- Capital Escalation Across Long-Horizon Growth Assets: Development capital expenditures are projected to increase by approximately $500 million, driven by heavy commitments to long-cycle projects including the $4.2 billion to $4.8 billion Red Chris block cave project—which is not slated for commercial production until 2033—heightening prolonged capital-intensity and execution risks.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.