


Oracle Corp Stock (ORCL) Moved Down by 8.05% on Nov 5: Key Drivers Unveiled


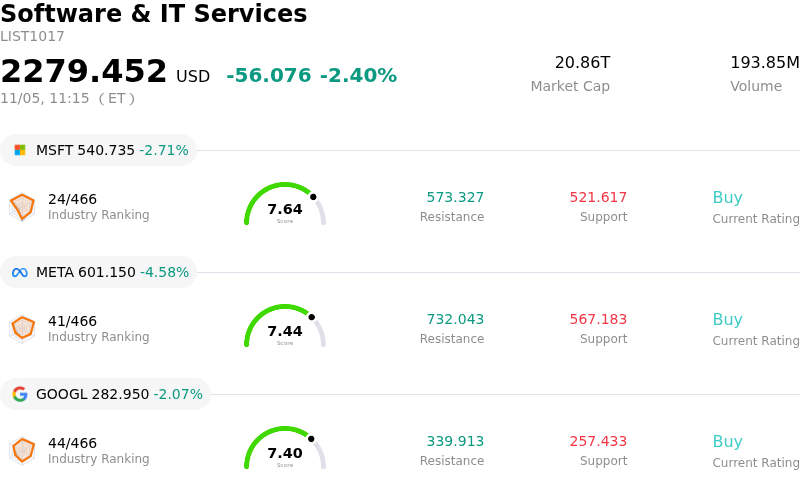
Oracle Corp (ORCL) moved down by 8.05%. The Software & IT Services sector is down by 2.40%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) down 2.71%; Meta Platforms Inc (META) down 4.49%; Alphabet Inc Class A (GOOGL) down 1.96%.
What is driving Oracle Corp (ORCL)’s stock price down today?
Oracle shares faced severe selling pressure during the session, driven by intensifying market scrutiny over enterprise software demand and the capital intensity required to scale its cloud infrastructure business. Institutional investors appear to be de-risking positions following growing apprehension that cloud revenue expansion and backlog conversion are pacing below elevated market expectations. As market participants reassess corporate software budgets and the timetable for enterprise artificial intelligence monetization, high-valuation software and cloud providers have experienced broad-based multiple compression.
A central contributor to the downward repricing stems from operational margin dynamics and aggressive capital spending. Oracle has committed substantial resources to expanding its data center footprint and high-performance computing clusters to accommodate advanced workloads. While this expansion supports contracted pipeline growth, it simultaneously strains free cash flow generation and dilutes near-term operating margins due to the heavy infrastructure depreciation and power procurement costs associated with operating dense compute clusters. Coupled with a balance sheet carrying notable leverage from prior infrastructure buildouts, institutional allocators are increasingly sensitive to return on invested capital metrics in an environment characterized by disciplined corporate capital allocation.
Competitive friction within the public cloud and database ecosystem has further dampened institutional sentiment. Hyperscalers continue to leverage scale advantages, aggressively discounting bundled enterprise productivity suites and specialized data management solutions, thereby pressuring Oracle's traditional licensing renewals and migration velocities. Concurrently, several research desks have moderated forward revenue growth assumptions for Oracle Cloud Infrastructure, prompting momentum funds and systematic strategies to trim overweight exposures. Until management demonstrates an acceleration in high-margin cloud consumption alongside stabilized capital intensity, the equity is likely to face ongoing valuation headwinds and heightened sensitivity to broader macroeconomic developments.
Technical Analysis of Oracle Corp (ORCL)
Technically, Oracle Corp (ORCL) shows a MACD (12,26,9) value of -2.308, indicating a sell signal. The RSI at 36.843 suggests neutral condition and the Williams %R at 99.046 suggests oversold condition. Please monitor closely.
Media Coverage of Oracle Corp (ORCL)
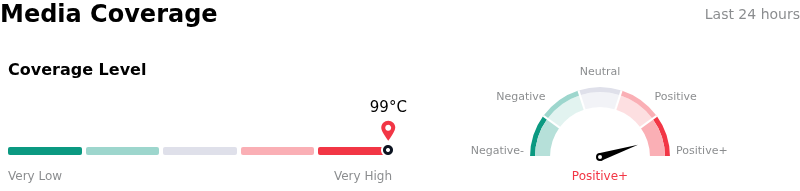
In terms of media coverage, Oracle Corp (ORCL) shows a coverage score of 99, indicating a very high level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Oracle Corp (ORCL)
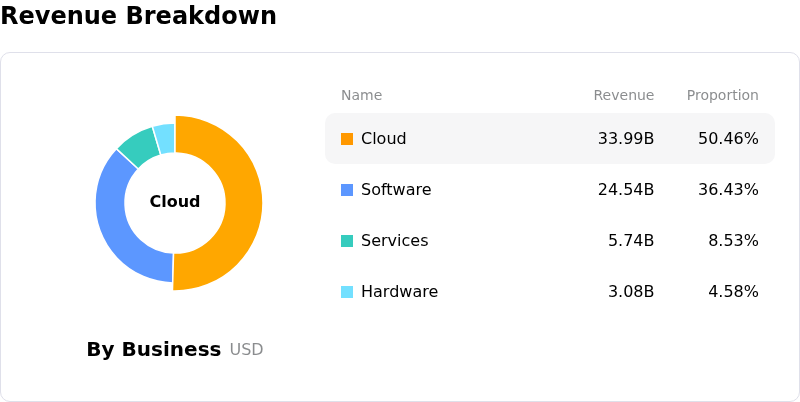
Oracle Corp (ORCL) is in the Software & IT Services industry. Its latest annual revenue is $67.36B, ranking 8 in the industry. The net profit is $16.98B, ranking 6 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $238.51, a high of $330.00, and a low of $110.00.
More details about Oracle Corp (ORCL)
Company Specific Risks:
- Termination of Tencent AI Chip Leasing Deal: Oracle was forced to cancel a high-profile $7 billion AI chip leasing contract with Tencent following heightened U.S. regulatory and geopolitical pressure, abruptly removing a major international cloud revenue stream and intensifying regulatory overhang across its global data center operations.
- Severe Shareholder Dilution and Expensive Debt Financing: The execution of a $20 billion capital raise created immediate intraday selling pressure due to an 11.2% discount on its $10 billion equity issuance ($116 per share), while its concurrent $10 billion bond offering carries steep coupon rates up to 8.65%, substantially elevating corporate interest burdens.
- Balance Sheet Deterioration and Junk-Status Downgrade Risk: Mounting leverage has expanded Oracle's total debt load toward $125 billion amid multi-year negative free cash flow forecasts driven by AI capital expenditures, leaving its BBB- credit rating vulnerable to further downgrades into speculative-grade status.
- Excessive Backlog Concentration in High-Risk AI Clients: Massive infrastructure commitments create structural exposure because a substantial portion of Oracle's cloud backlog remains concentrated in a single anchor client, OpenAI, heightening downside risks of idle capacity and stranded capital if leading AI developers curb capex or re-architect deployments.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.