


CrowdStrike Holdings Inc Stock (CRWD) Moved Down by 3.14% on Nov 2: Key Drivers Unveiled


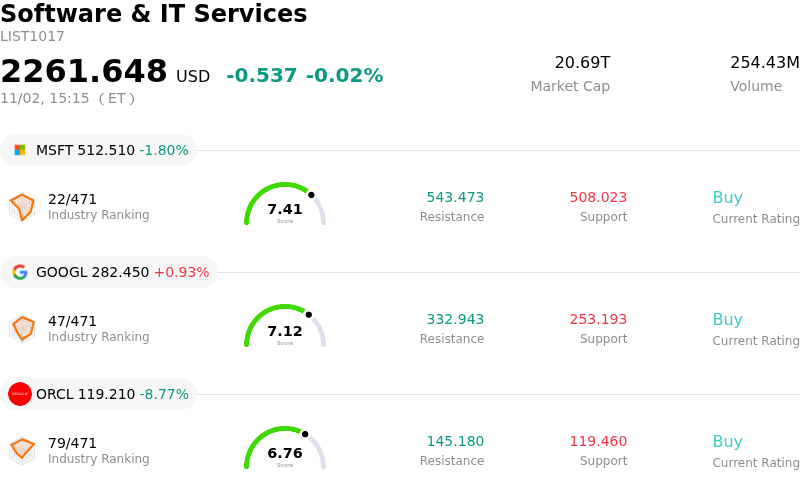
CrowdStrike Holdings Inc (CRWD) moved down by 3.14%. The Software & IT Services sector is down by 0.02%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) down 1.77%; Alphabet Inc Class A (GOOGL) up 0.92%; Oracle Corp (ORCL) down 8.77%.
What is driving CrowdStrike Holdings Inc (CRWD)’s stock price down today?
CrowdStrike experienced downward pressure and heightened intraday volatility as broader software sector headwinds and profit-taking outweighed positive company-specific catalysts. The software and cybersecurity landscape faced a re-rating as investor concerns mounted regarding heavy artificial intelligence capital expenditures and cash burn across tech majors. Sector sentiment was further dampened by cautious forward guidance and soft bookings reported by peer security vendors, reinforcing market worries that enterprise cybersecurity spending could face tighter corporate budget scrutiny. Following a strong year-to-date rally, CrowdStrike's premium valuation left the equity vulnerable to sector-wide multiple compression.
The stock exhibited notable intraday swings as positive fundamentals clashed with sector headwinds. Bullish sentiment was initially bolstered by sell-side actions after Deutsche Bank upgraded the equity to a Buy rating and increased its price target, citing expanding long-term addressable market opportunities driven by corporate artificial intelligence adoption. Supporting this outlook, CrowdStrike announced strategic partnership expansions with CoreWeave to secure production AI workloads, Dynatrace for integrated observability, and Deloitte for AI risk advisory services.
Despite these positive strategic initiatives and analyst commentary, the broader selloff in software equities dominated price action through the close. Market participants appear to be prioritizing concrete near-term cash flow metrics and recurring revenue execution over long-term market expansion models. Institutional focus remains on the company's upcoming earnings report, where key indicators will include annual recurring revenue growth, platform adoption rates, and free cash flow conversion amid a tight corporate IT spending environment.
Technical Analysis of CrowdStrike Holdings Inc (CRWD)
Technically, CrowdStrike Holdings Inc (CRWD) shows a MACD (12,26,9) value of -1.729, indicating a neutral signal. The RSI at 45.806 suggests neutral condition and the Williams %R at 58.747 suggests sell condition. Please monitor closely.
Media Coverage of CrowdStrike Holdings Inc (CRWD)
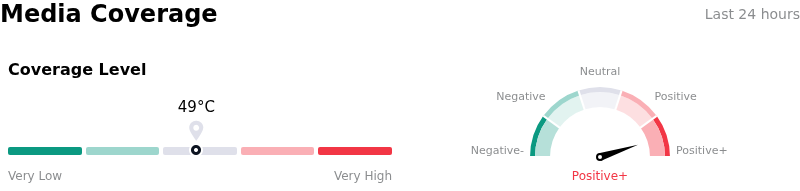
In terms of media coverage, CrowdStrike Holdings Inc (CRWD) shows a coverage score of 49, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of CrowdStrike Holdings Inc (CRWD)
CrowdStrike Holdings Inc (CRWD) is in the Software & IT Services industry. Its latest annual revenue is $4.81B, ranking 67 in the industry. The net profit is $-162.50M, ranking 555 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $245.44, a high of $325.00, and a low of $119.00.
More details about CrowdStrike Holdings Inc (CRWD)
Company Specific Risks:
- Valuation Multiples and Profit-Taking Sensitivity: Trading near 50 times sales after doubling year-to-date, CrowdStrike faces extreme vulnerability to intraday profit-taking and valuation repricing during tech sector drawdowns, leaving zero margin for execution missteps ahead of upcoming quarterly results.
- Enterprise Security Spending and Peer Spillover Drag: Weak earnings reports and delayed contract activations from cybersecurity peers like Fortinet and Check Point reflect enterprise security budget caution, threatening near-term billings momentum and deal conversion rates.
- Competitive Threats from Native AI Platforms: Expanding security offerings by hyperscalers and potential market entry by foundational AI developers threaten to squeeze software margins and challenge Falcon platform subscription expansions over time.
- Ongoing Debacle Liabilities and Contract Friction: Overhanging legal litigation, potential enterprise compensation costs, and extended sales cycles stemming from previous Falcon sensor update outages continue to pose structural headwinds to operating profit margin expansion.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.