


Visa Inc Stock (V) Moved Up by 3.14% on Nov 2: What Investors Need To Know


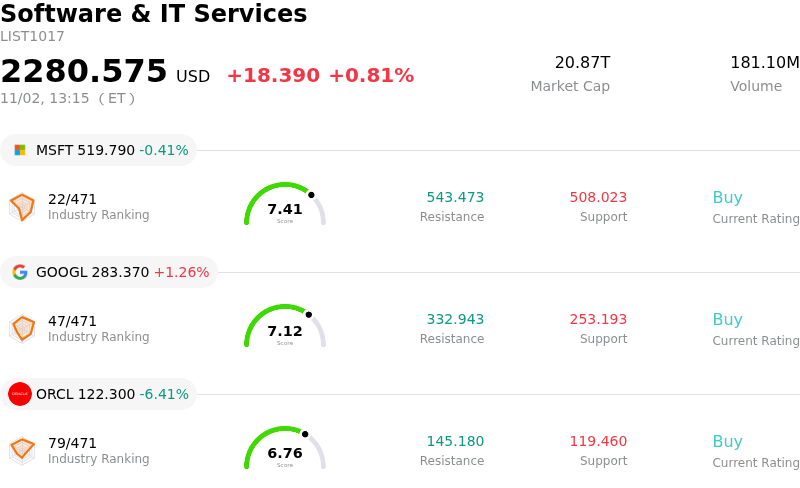
Visa Inc (V) moved up by 3.14%. The Software & IT Services sector is up by 0.81%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) down 0.38%; Alphabet Inc Class A (GOOGL) up 1.25%; Oracle Corp (ORCL) down 6.42%.
What is driving Visa Inc (V)’s stock price up today?
Visa experienced upward momentum accompanied by heightened intraday volatility as bullish Wall Street sentiment gathered speed. A key catalyst driving the rally was a notable price target increase from Cantor Fitzgerald, which raised its price objective to $500 per share while reiterating an Overweight rating. This vote of confidence follows a wave of target upward revisions from other prominent sell-side firms in the wake of the company's latest quarterly performance. Investors reacted positively to analyst commentary highlighting Visa's ability to drive revenue growth at a pace faster than total payment volume, supported by favorable transaction mix, international cross-border expansion, and value-added service adoption.
The underlying foundation for this positive repricing remains Visa's robust fiscal fourth-quarter financial report. The payments network delivered solid top- and bottom-line beats, fueled by double-digit growth in cross-border transaction volume, persistent resilience in international travel, and steady domestic consumer spending. Beyond headline earnings, management's decision to raise the quarterly cash dividend by 16% and maintain aggressive share repurchases reinforced institutional confidence in the firm's long-term cash flow generation and capital allocation discipline. Additionally, expanding high-margin value-added services and commercial payment solutions provided investors with clear visibility into multi-year earnings durability.
Despite initial post-earnings profit-taking and broader macroeconomic discussions regarding consumer trends, buying pressure accelerated as institutional investors digested the durable nature of Visa's network monetization model. Intraday volatility reflected short-term repositioning as the market weighed upcoming contract renewal cycles and client incentive structures against long-term structural tailwinds in global digital transactions. Overall, the combination of strong operating leverage, solid balance sheet strength, and favorable broker upgrades reignited buyer interest, positioning the stock as a preferred high-quality defensive holding in the financial technology sector.
Technical Analysis of Visa Inc (V)
Technically, Visa Inc (V) shows a MACD (12,26,9) value of 2.670, indicating a buy signal. The RSI at 75.488 suggests buy condition and the Williams %R at 0.565 suggests overbought condition. Please monitor closely.
Media Coverage of Visa Inc (V)
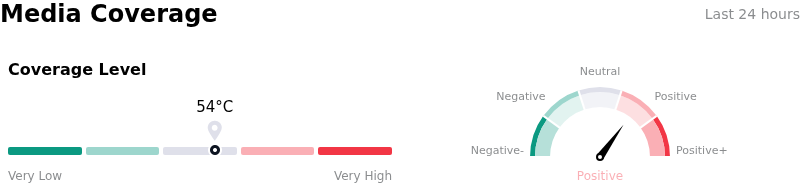
In terms of media coverage, Visa Inc (V) shows a coverage score of 54, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Visa Inc (V)
Visa Inc (V) is in the Software & IT Services industry. Its latest annual revenue is $45.90B, ranking 12 in the industry. The net profit is $23.50B, ranking 5 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $439.84, a high of $500.00, and a low of $336.60.
More details about Visa Inc (V)
Company Specific Risks:
- Antitrust Litigation and Regulatory Fee Caps: Visa faces an ongoing £5 billion multilateral interchange fee class action at the UK Competition Appeal Tribunal representing over one million claimants, intensifying global regulatory scrutiny that threatens card processing fee structures and fee revenue.
- Decelerating Growth Guidance: Management's fiscal 2027 outlook projects a slowdown to low double-digit net revenue growth and low-teens EPS growth—stepping down from fiscal 2026's 15% revenue expansion—triggering investor concern over growth durability at current valuation multiples.
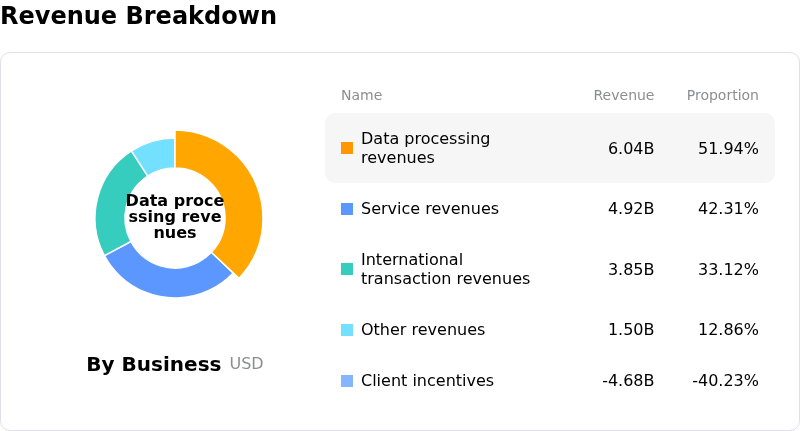
- Margin Erosion via Rising Client Incentives: Client incentive expenses paid to bank partners to secure card issuance increased 21% year-over-year to $5.12 billion, continuing to grow faster than net revenue and compressing underlying operating margins.
- Structural Disintermediation from Alternative Payment Rails: The accelerating push by international regulators for domestic account-to-account (A2A) systems, open-banking infrastructure, and non-card rails threatens to bypass traditional card networks and erode high-margin transaction volumes.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.