


Mastercard Inc Stock (MA) Moved Up by 3.42% on Nov 2: Facts Behind the Movement


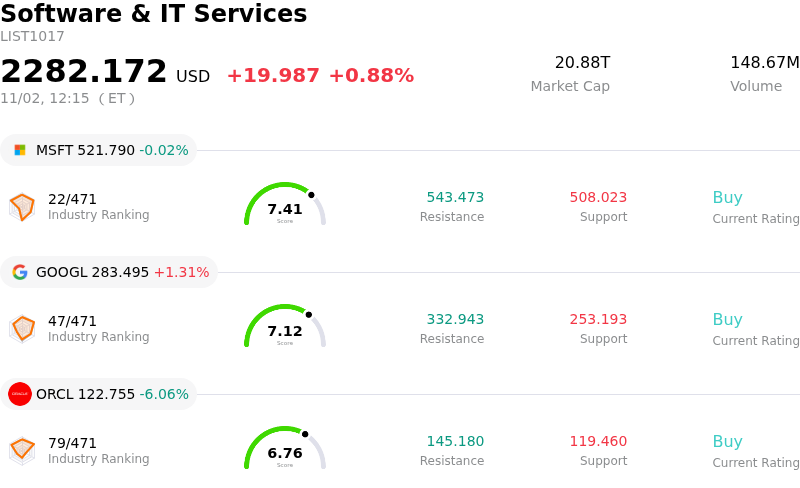
Mastercard Inc (MA) moved up by 3.42%. The Software & IT Services sector is up by 0.88%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) down 0.03%; Alphabet Inc Class A (GOOGL) up 1.27%; Oracle Corp (ORCL) down 6.06%.
What is driving Mastercard Inc (MA)’s stock price up today?
Mastercard experienced strong upward momentum accompanied by heightened intraday volatility, driven primarily by sustained investor enthusiasm following its robust quarterly earnings report. The payment network provider delivered better-than-expected top- and bottom-line results, extending its multi-quarter streak of outperforming Wall Street expectations. Solid underlying transaction metrics, resilient consumer balance sheets, and steady gross dollar volume growth continue to reinforce investor confidence in the company's core payment processing business.
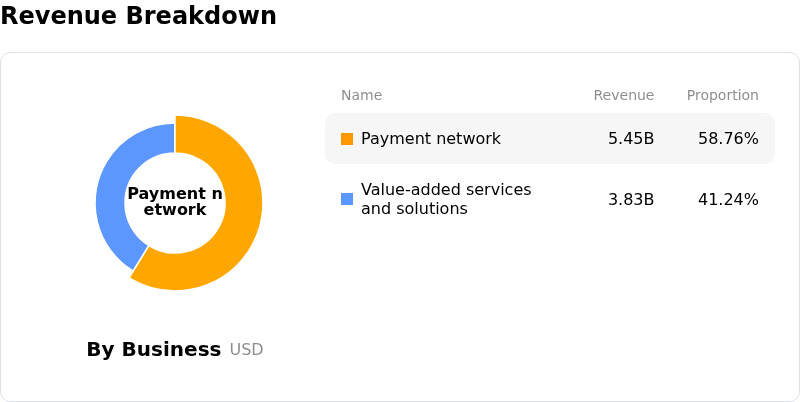
A key catalyst behind the positive price action is the rapid expansion of Mastercard's high-margin value-added services and solutions. Revenue from cybersecurity, fraud mitigation, data analytics, and commercial payment technologies surged year over year, effectively outpacing core network growth. This favorable revenue mix shift has expanded operating margins and demonstrated significant operating leverage, successfully absorbing higher customer rebates and operational expenditures. Additionally, persistent strength in cross-border volume trends points to sustained international travel and cross-currency commerce demand.
Institutional sentiment remains firmly supported by aggressive capital return strategies, including ongoing multi-billion-dollar share buybacks that bolster per-share earnings. Management's confident full-year guidance and strategic expansions into digital wallets, stablecoin partnerships, and agentic commerce reinforce the company's long-term competitive moat. While intraday trading reflected broader macroeconomic noise and sector rotation, Mastercard's underlying operational tailwinds and strong earnings trajectory continue to drive robust buying interest.
Technical Analysis of Mastercard Inc (MA)
Technically, Mastercard Inc (MA) shows a MACD (12,26,9) value of 6.000, indicating a buy signal. The RSI at 76.557 suggests buy condition and the Williams %R at 1.956 suggests overbought condition. Please monitor closely.
Media Coverage of Mastercard Inc (MA)
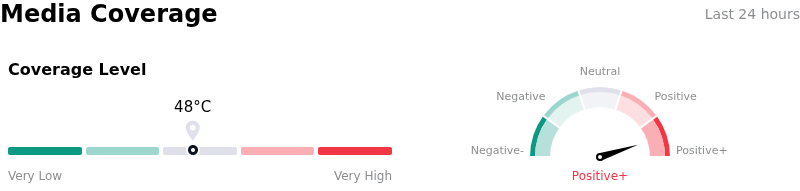
In terms of media coverage, Mastercard Inc (MA) shows a coverage score of 48, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Mastercard Inc (MA)
Mastercard Inc (MA) is in the Software & IT Services industry. Its latest annual revenue is $32.79B, ranking 16 in the industry. The net profit is $14.97B, ranking 7 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $697.52, a high of $775.00, and a low of $547.32.
More details about Mastercard Inc (MA)
Company Specific Risks:
- Escalating U.K. and U.S. Legal Contingencies: In recent legal disclosures, Mastercard revealed two new proposed U.K. merchant collective action lawsuits seeking approximately £1.5 billion and £0.4 billion in damages. These join over £0.5 billion in existing unresolved U.K. claims and an unquantifiable potential overall exposure in ongoing U.S. multidistrict litigation.
- Margin Compression from Rising Network Incentives: Payment network rebates and incentives expanded 18% year-over-year, growing faster than overall net revenue. Management guidance anticipates that rebates and incentives as a share of gross revenues will rise further, posing downside risk to core net fee realization.
- Stagnant U.S. Debit Volume Growth: U.S. debit growth decelerated to just 1% in recent performance metrics, driven by ongoing issuer card portfolio migration headwinds that continue to suppress near-term domestic transaction volume expansion.
- Softness in High-Margin Cross-Border Segments: Growth in high-fee cross-border revenues is being restrained by slowing intra-Europe e-commerce volumes, alongside geopolitical travel disruptions in the Middle East and cooling momentum across online travel agency booking channels.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.