


Arm Holdings PLC Stock (ARM) Moved Up by 3.06% on Oct 28: What Signal Does It Send?



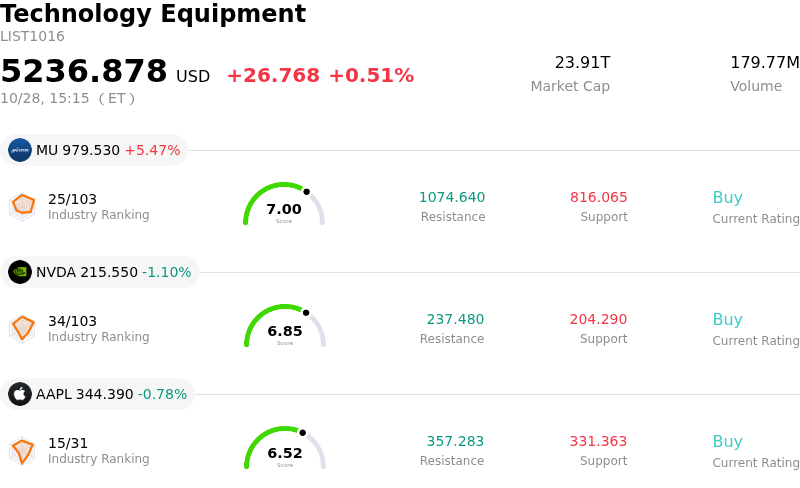
Arm Holdings PLC (ARM) moved up by 3.06%. The Technology Equipment sector is up by 0.51%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) up 5.47%; NVIDIA Corp (NVDA) down 1.12%; Apple Inc (AAPL) down 0.78%.
What is driving Arm Holdings PLC (ARM)’s stock price up today?
Arm Holdings experienced positive price momentum during the session, supported by a significant reduction in legal uncertainty and renewed institutional accumulation. A primary driver behind the bullish intraday action was the resolution of the long-running legal dispute with Qualcomm over architectural licensing terms. The favorable outcome effectively removes a persistent legal overhang that had previously capped upside potential, reinforcing the integrity of Arm's core licensing model and reassuring investors regarding future royalty revenue streams from custom silicon implementations.
Fundamental tailwinds in artificial intelligence and server architecture continue to bolster investor enthusiasm. The company is benefiting from accelerating adoption of its high-efficiency instruction set architecture across cloud data centers, driven by rising demand for compute subsystems tailored to agentic artificial intelligence workloads. As partners transition to higher-tier architecture versions, royalty growth has outpaced traditional licensing revenue, highlighting the expanding high-margin potential of its intellectual property. Ahead of its upcoming quarterly financial results in early November, market participants are actively positioning for continued strength in server royalty momentum.
Institutional portfolio adjustments and positive analyst sentiment provided an additional layer of market support. Recent institutional filing data indicates that multiple asset managers have expanded their holdings in Arm, viewing recent pullback levels as an attractive entry point to capture long-term AI hardware tailwinds. Wall Street analysts maintain a predominantly favorable outlook on the stock, pointing to its structural competitive advantages and expanding market share in high-performance computing. While the stock exhibited notable intraday volatility reflecting pre-earnings options positioning and broader semiconductor sector rebalancing, buyers ultimately maintained control as the broader outlook remains anchored by secular growth in data center silicon demand.
Technical Analysis of Arm Holdings PLC (ARM)
Technically, Arm Holdings PLC (ARM) shows a MACD (12,26,9) value of -4.394, indicating a sell signal. The RSI at 43.467 suggests neutral condition and the Williams %R at 64.590 suggests sell condition. Please monitor closely.
Fundamental Analysis of Arm Holdings PLC (ARM)
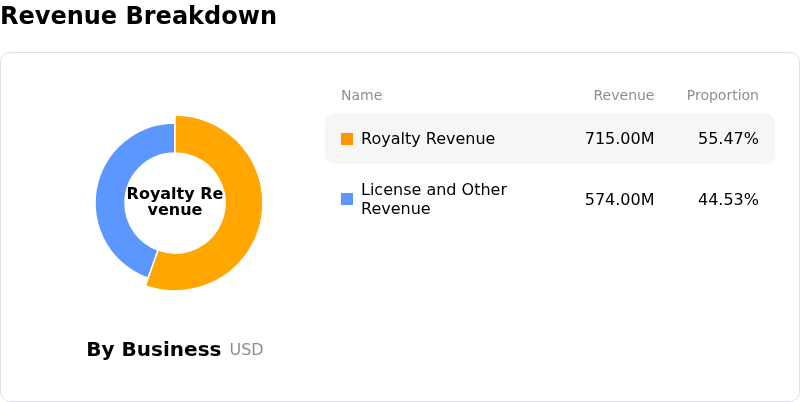
Arm Holdings PLC (ARM) is in the Technology Equipment industry. Its latest annual revenue is $4.92B, ranking 24 in the industry. The net profit is $904.00M, ranking 18 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $286.95, a high of $480.00, and a low of $125.00.
More details about Arm Holdings PLC (ARM)
Company Specific Risks:
- Adverse Qualcomm Litigation Verdict and Royalty Exposure: Following a Delaware federal jury ruling that Arm breached its Architectural License Agreement with Qualcomm by withholding software tools and interfering with commercial dealings, the court is evaluating Qualcomm's request to pause royalty payments for up to five years, creating significant downside exposure to core licensing revenue.
- FTC Antitrust Investigation into Anti-Competitive Practices: U.S. Federal Trade Commission scrutiny regarding whether Arm is leveraging its architecture market power to illegally monopolize semiconductor segments as it moves further down the supply chain creates ongoing regulatory, legal, and operational headwinds.
- Ecosystem Friction and Hardware Execution Risks: Arm's strategic expansion into direct processor designs and production silicon puts the company into direct competition with its own architectural licensees, threatening long-standing customer partnerships while exposing operations to foundry capacity bottlenecks.
- Pre-Earnings Implied Volatility and Valuation Decompression: Market pricing reflects anticipated post-earnings swings of nearly 9% to 13% ahead of the upcoming November quarterly report, leaving the stock susceptible to intraday sell-offs given its high valuation multiple and history of sharp post-earnings drawdowns.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.