


ASE Technology Holding Co Ltd Stock (ASX) Moved Up by 3.26% on Oct 28: A Full Analysis



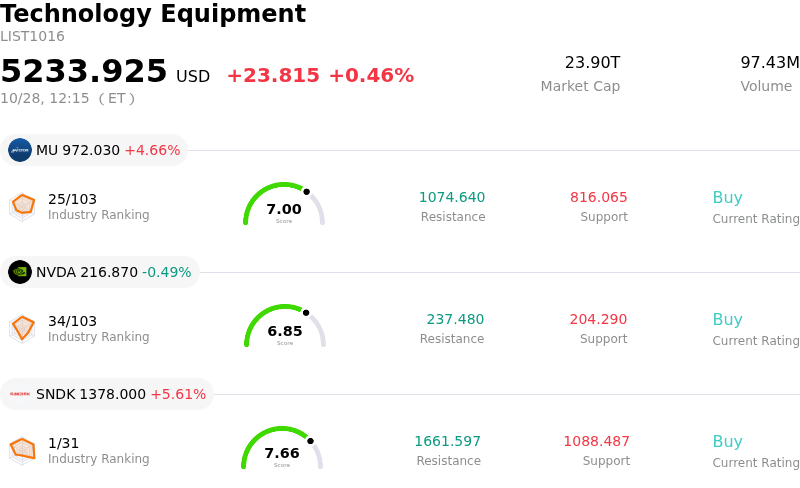
ASE Technology Holding Co Ltd (ASX) moved up by 3.26%. The Technology Equipment sector is up by 0.46%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) up 4.67%; NVIDIA Corp (NVDA) down 0.47%; SanDisk Corporation (SNDK) up 5.61%.
What is driving ASE Technology Holding Co Ltd (ASX)’s stock price up today?
ASE Technology Holding experienced notable upward momentum accompanied by heightened intraday volatility as market participants positioned themselves ahead of the company's scheduled third-quarter earnings announcement. Investor optimism is primarily anchored in expectations of robust quarterly performance, supported by accelerating demand for outsourced semiconductor assembly and testing services. As a critical partner in the global semiconductor supply chain, the company continues to benefit from expanding artificial intelligence hardware deployment and high-performance computing workload expansion.
Underlying sentiment remains reinforced by previously released revenue updates that highlighted significant year-over-year top-line expansion and sequential acceleration throughout the third quarter. Management's constructive long-term growth outlook, particularly concerning leading-edge advanced packaging solutions and elevated capital expenditures to meet capacity requirements, has bolstered confidence among institutional investors. Additionally, positive momentum across broader semiconductor equities and AI hardware supply chain peers provided sector-wide tailwinds, offsetting ongoing debates around valuation multiples and macroeconomic conditions.
The observed intraday volatility reflects active positioning and options market activity typical ahead of a key corporate earnings catalyst. While elevated market expectations leave the equity sensitive to short-term profit-taking, strong structural demand for advanced packaging technology continues to serve as a primary growth driver. Institutional investors are closely scrutinizing the upcoming financial release for management guidance on forward margins, capacity utilization, and capital expenditure targets.
Technical Analysis of ASE Technology Holding Co Ltd (ASX)
Technically, ASE Technology Holding Co Ltd (ASX) shows a MACD (12,26,9) value of -0.691, indicating a sell signal. The RSI at 53.143 suggests neutral condition and the Williams %R at 41.592 suggests buy condition. Please monitor closely.
Fundamental Analysis of ASE Technology Holding Co Ltd (ASX)
ASE Technology Holding Co Ltd (ASX) is in the Technology Equipment industry. Its latest annual revenue is $20.71B, ranking 13 in the industry. The net profit is $1.30B, ranking 17 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Strong Buy, with an average price target of $50.02, a high of $58.00, and a low of $42.04.
More details about ASE Technology Holding Co Ltd (ASX)
Company Specific Risks:
- Capacity Bottlenecks and Surging Capital Expenditures: Operational updates highlight that assembly, packaging, and testing facilities are running near full capacity (80%–85% blended utilization), restricting near-term volume growth. To resolve these operational constraints, management escalated its 2026 capital expenditure budget to $10.5 billion, introducing significant cash flow drag and execution risks linked to facility expansion.
- Severe Valuation Compression Vulnerability: Following a rapid stock surge exceeding 150% year-to-date, key valuation indicators signal that shares are substantially overvalued. Trading at a price-to-earnings ratio near 49—well above broad technology market benchmarks—the stock faces heightened downside risk if top-line performance fails to justify current pricing levels.
- Substantial Insider Capital Divestment: Corporate filing and tracking metrics reveal over $360 million in insider stock sales over the trailing 12-month period with zero insider purchases, signaling institutional concern regarding management's internal confidence in sustaining peak trading multiples.
- Impending Earnings Execution and Margin Risks: Ahead of its Q3 earnings release on October 29, aggressive analyst consensus estimates ($7.25 billion revenue) create heightened positioning risk. Any commentary indicating margin erosion from elevated equipment installation costs or wafer probing bottlenecks could spark sharp intraday sell-offs.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.