


Garmin Ltd Stock (GRMN) Moved Down by 6.78% on Oct 28: What Signal Does It Send?



Garmin Ltd (GRMN) moved down by 6.78%. The Technology Equipment sector is up by 0.49%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) up 4.94%; NVIDIA Corp (NVDA) down 0.01%; SanDisk Corporation (SNDK) up 5.44%.
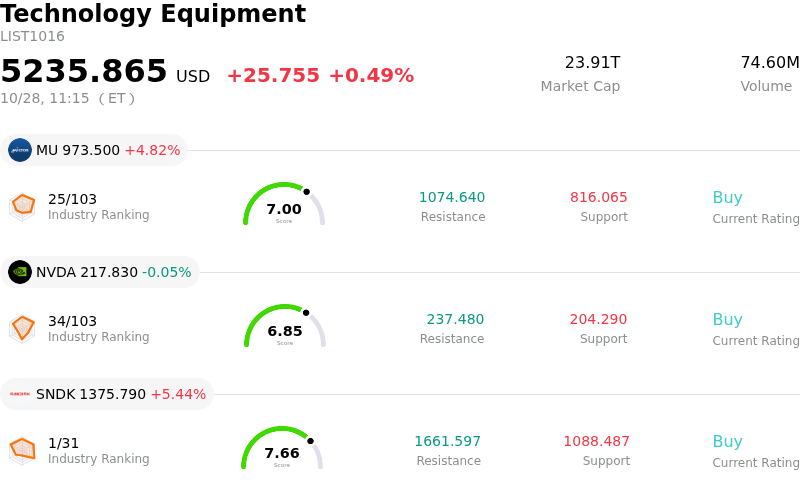
What is driving Garmin Ltd (GRMN)’s stock price down today?
Garmin experienced notable downside pressure following its third-quarter financial release, despite delivering bottom-line earnings per share that surpassed Wall Street expectations and raising its full-year guidance. Market sentiment was weighed down primarily by top-line revenue, which landed essentially in line with consensus projections rather than providing a decisive upside beat. Having entered the earnings event following a multi-month rally that elevated valuation multiples above industry averages, the absence of a substantial top-line beat prompted investors to engage in a classic sell-the-news profit-taking reaction.
A granular examination of operating profitability further tempered institutional enthusiasm. While consolidated gross margin expanded to record levels, investors noted that the figure benefited from a one-off item, specifically thirty-three million dollars in tariff refunds. Adjusting for this discrete item reveals that core gross margin expansion, while healthy, was somewhat less dramatic than the headline metric suggested. Additionally, underlying segment divergence added to execution concerns. Strong momentum in the Fitness and Outdoor divisions—fueled by new product introductions such as the fēnix 9 smartwatch lineup—was partially overshadowed by persistent softness in Auto OEM, where revenue dropped twenty percent year-over-year and resulted in an operating loss.
Looking forward, Garmin raised its full-year revenue outlook to approximately $8.15 billion and pro forma earnings per share to $10.80, pointing toward positive momentum as the business enters the critical holiday selling period. However, given macroeconomic headwinds surrounding high-end consumer hardware demand and elevated equity valuations, market participants appear to be demanding more balanced revenue acceleration across all segments before establishing new long positions.
Technical Analysis of Garmin Ltd (GRMN)
Technically, Garmin Ltd (GRMN) shows a MACD (12,26,9) value of -0.358, indicating a neutral signal. The RSI at 37.586 suggests neutral condition and the Williams %R at 85.834 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Garmin Ltd (GRMN)
Garmin Ltd (GRMN) is in the Technology Equipment industry. Its latest annual revenue is $7.25B, ranking 7 in the industry. The net profit is $1.66B, ranking 7 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $288.30, a high of $370.00, and a low of $220.00.
More details about Garmin Ltd (GRMN)
Company Specific Risks:
- Automotive OEM Revenue Contraction and Operating Losses: In its Q3 2026 8-K earnings release, Garmin reported a 20% year-over-year decline in Automotive OEM segment revenue to $131.91 million—driven by lower domain controller volumes—resulting in a $12 million operating loss for the segment and underscoring persistent headwind in auto technology contracts.
- Consensus Top-Line Revenue Miss: Despite reporting record quarterly sales overall, Garmin's Q3 2026 net revenue of $1.986 billion fell short of Wall Street consensus estimates of $1.989 billion, sparking intraday volatility and institutional concern regarding top-line growth momentum.
- Valuation Premium and Multiple Compression Risks: Trading at an elevated forward P/E multiple above 27x—a significant premium relative to consumer durables peer averages—the stock faces heightened vulnerability to profit-taking and valuation rerating upon any revenue growth deceleration.
- Rising Component Costs and Supply Chain Volatility: Recent analyst commentary highlights ongoing input cost risks, specifically rising memory chip prices and electronic hardware component inflation, which threaten gross margin expansion across core fitness and outdoor device lines.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles










Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.