


Intel Corp Stock (INTC) Moved Up by 3.74% on Oct 26: Drivers Behind the Movement



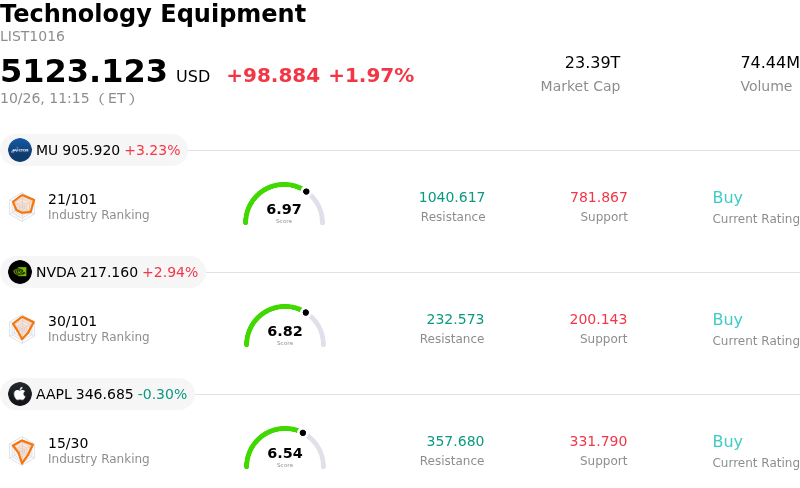
Intel Corp (INTC) moved up by 3.74%. The Technology Equipment sector is up by 1.97%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) up 3.23%; NVIDIA Corp (NVDA) up 2.94%; Apple Inc (AAPL) down 0.25%.
What is driving Intel Corp (INTC)’s stock price up today?
Intel Corporation experienced an upward rebound accompanied by significant intraday volatility as market sentiment stabilized following a recent pull-back across the broader semiconductor sector. Investors capitalized on lower entry levels to buy the dip, absorbing recent industry-wide concerns regarding tech supply chain bottlenecks. The renewed buying interest highlights growing market confidence in the semiconductor industry's fundamental demand drivers, particularly across data center compute and central processing units.
A key catalyst behind the positive price action was institutional enthusiasm generated by Wall Street coverage updates. Analyst research from firms such as New Street shifted to a more bullish stance, upgrading the stock to a Buy rating on expectations that structural CPU scarcity will strengthen Intel's operational turnaround. Moreover, market participants are actively positioning ahead of the company's third-quarter earnings release, where consensus forecasts project substantial year-over-year top-line and bottom-line growth driven by robust demand across server segments and advanced packaging solutions.
While short-term momentum remains supportive, investors continue to monitor several critical operational and macroeconomic factors. The market is focused on management's ability to execute its foundry manufacturing roadmap, scale advanced packaging capacity, and navigate elevated capital expenditures without compromising free cash flow generation. Additionally, ongoing competitive pressure in artificial intelligence accelerators and potential macroeconomic headwinds require sustained operational execution to validate valuation levels and maintain institutional support.
Technical Analysis of Intel Corp (INTC)
Technically, Intel Corp (INTC) shows a MACD (12,26,9) value of -4.135, indicating a sell signal. The RSI at 37.643 suggests neutral condition and the Williams %R at 82.075 suggests oversold condition. Please monitor closely.
Media Coverage of Intel Corp (INTC)
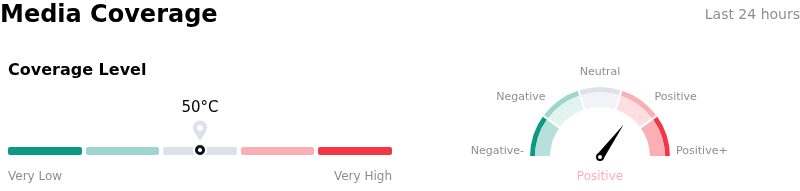
In terms of media coverage, Intel Corp (INTC) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Intel Corp (INTC)
Intel Corp (INTC) is in the Technology Equipment industry. Its latest annual revenue is $52.85B, ranking 6 in the industry. The net profit is $-267.00M, ranking 111 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $115.09, a high of $200.00, and a low of $80.00.
More details about Intel Corp (INTC)
Company Specific Risks:
- Upcoming Earnings Volatility and Valuation Risk: Options traders are pricing in a near 10% post-earnings move ahead of the Q3 2026 financial report on October 29, reflecting market hesitation over elevated forward earnings multiples following a 29% stock drawdown over the past month.
- Persistent Server and PC Market Share Losses: Institutional research from JPMorgan highlights structural market share erosion, with Intel's server x86 CPU revenue market share declining to 53% and PC share falling to 68%, alongside expectations of additional market share losses to key competitors in upcoming quarters.
- Slow External Foundry Commercialization: Despite heavy investments into its 18A process node, Intel's external foundry revenues remain low at approximately $1 billion annualized, raising institutional concerns regarding third-party customer adoption and manufacturing scale compared to foundry rivals.
- Free Cash Flow Pressure and Shareholder Dilution: Massive capital expenditure requirements for global fab expansions combined with negative adjusted free cash flow necessitated a recent $20 billion common stock offering, creating potential balance sheet drag and equity dilution risks.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.