


Lam Research Corp Stock (LRCX) Moved Down by 9.80% on Oct 22: Key Drivers Unveiled



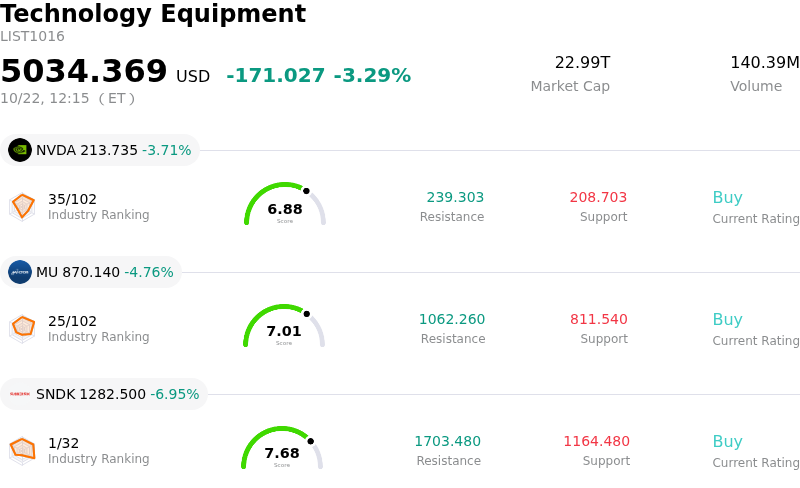
Lam Research Corp (LRCX) moved down by 9.80%. The Technology Equipment sector is down by 3.29%. The company underperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) down 3.66%; Micron Technology Inc (MU) down 4.76%; SanDisk Corporation (SNDK) down 6.95%.
What is driving Lam Research Corp (LRCX)’s stock price down today?
Lam Research experienced significant downward pressure following the release of its fiscal first-quarter financial results. Although the semiconductor equipment manufacturer delivered quarterly revenue and earnings beats alongside record gross and operating margins, the market responded with a pronounced sell-the-news reaction. The primary driver of investor disappointment was forward revenue and earnings guidance for the December quarter. While management's projections formally met Wall Street's official consensus, they fell short of elevated buy-side whisper expectations that had priced in a steeper growth trajectory tied to artificial intelligence buildouts.
Compounding the negative sentiment, company executives highlighted operational constraints during the earnings call. Near-term supply chain bottlenecks and component shortages restricted shipment capabilities for the upcoming quarter, capping near-term revenue potential and pushing delivery timelines into subsequent quarters. Furthermore, sales to China represented over a third of total revenue during the quarter. Management signaled that regional revenue from China is expected to step down noticeably in subsequent quarters, reigniting investor concerns over geographic demand sustainability and ongoing export control risks.
The narrow beat margin offered little protection for a stock trading at rich valuation multiples. Following the earnings update, multiple Wall Street firms lowered their target prices, citing near-term supply chain constraints and geographic revenue shifts. The pullback also exerted broader pressure on peer semiconductor equipment makers, reflecting sector-wide re-evaluation of near-term capital expenditure growth rates despite strong long-term industry fundamentals driven by chip complexity and high-bandwidth memory demand.
Technical Analysis of Lam Research Corp (LRCX)
Technically, Lam Research Corp (LRCX) shows a MACD (12,26,9) value of -16.965, indicating a sell signal. The RSI at 25.506 suggests sell condition and the Williams %R at 97.620 suggests oversold condition. Please monitor closely.
Media Coverage of Lam Research Corp (LRCX)
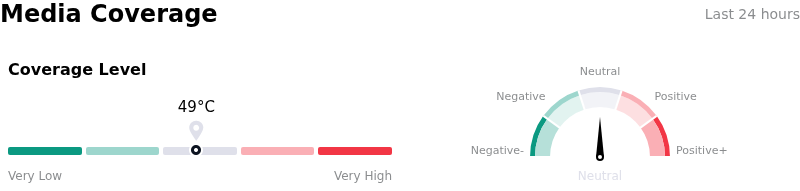
In terms of media coverage, Lam Research Corp (LRCX) shows a coverage score of 49, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Lam Research Corp (LRCX)
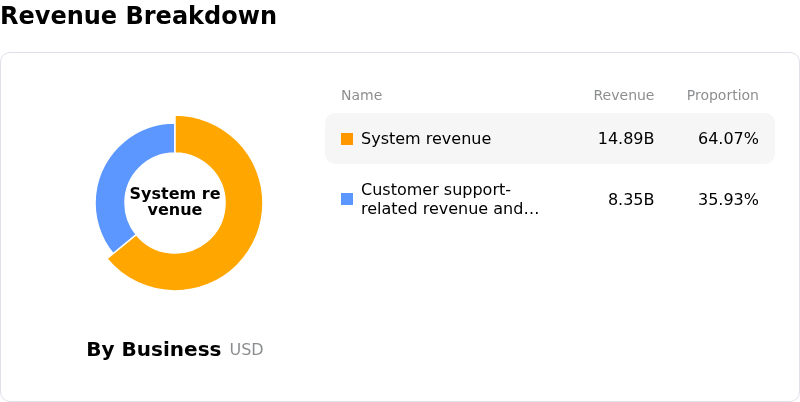
Lam Research Corp (LRCX) is in the Technology Equipment industry. Its latest annual revenue is $23.23B, ranking 12 in the industry. The net profit is $7.27B, ranking 7 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $370.58, a high of $500.00, and a low of $213.00.
More details about Lam Research Corp (LRCX)
Company Specific Risks:
- Supply Chain Bottlenecks and Cautious Guidance: Despite exceeding fiscal Q1 top-and-bottom line expectations in its Form 8-K filing, Lam Research provided a December-quarter revenue outlook ($8.6 billion midpoint) that failed to meet elevated market expectations. Management attributed the muted outlook to near-term supply chain constraints delaying equipment deliveries into subsequent quarters.
- Declining Revenue Contribution from China: Company executives indicated on the Q1 earnings call that revenue from China peaked at 35% of total sales in the September quarter and is projected to be "meaningfully down" in the December quarter, highlighting operational exposure to regional demand softening and strict semiconductor export restrictions.
- Analyst Price Target Downgrades: Following the outlook presentation, institutional analysts lowered their price expectations for the stock. Notable revisions included Needham cutting its price target from $390 to $290 and Morgan Stanley reducing its target to $339 due to near-term growth bottlenecks and whisper-number shortfalls.
- Stretched Valuation Multiples and Heavy Insider Selling: The earnings disappointment triggered a sharp selloff after trading at an inflated trailing price-to-earnings ratio relative to historical averages. Market pressure has been intensified by a lack of internal buy-side conviction, with insider sales totaling $168.7 million over the past 12 months against zero insider purchases.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.