


ASE Technology Holding Co Ltd Stock (ASX) Moved Up by 3.85% on Oct 19: A Full Analysis



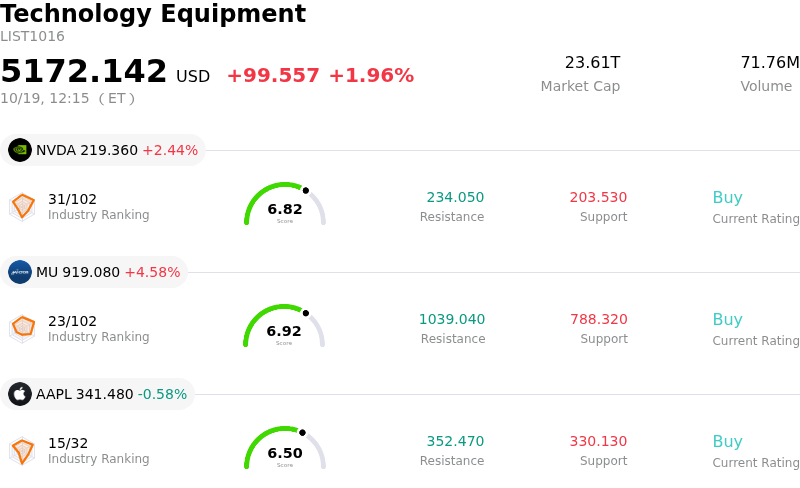
ASE Technology Holding Co Ltd (ASX) moved up by 3.85%. The Technology Equipment sector is up by 1.96%. The company outperformed the industry. Top 3 stocks by turnover in the sector: NVIDIA Corp (NVDA) up 2.44%; Micron Technology Inc (MU) up 4.58%; Apple Inc (AAPL) down 0.58%.
What is driving ASE Technology Holding Co Ltd (ASX)’s stock price up today?
ASE Technology Holding experienced a strong upward trajectory as buyer interest resumed following a brief sector-wide pullback across semiconductor equities. Market sentiment turned decisively positive as investors reassessed the company's recent quarterly performance, which featured substantial year-over-year top-line expansion led by a surge in its primary Assembly, Testing, and Materials business. Industry sentiment was further boosted by record financial results and upbeat forward guidance from primary foundry partner Taiwan Semiconductor Manufacturing Company, which underscored relentless structural demand for artificial intelligence hardware and advanced chip packaging solutions.
As the world's leading provider of outsourced semiconductor assembly and test services with a dominant global market share, ASE remains uniquely positioned to capture expanding workloads in high-performance computing and next-generation artificial intelligence accelerators. The recent price action reflects active bargain-hunting following short-term profit-taking that had temporarily pushed the stock toward key moving-average technical support levels. Institutional investors capitalized on the pullback, recognizing that high foundry utilization rates continue to spill over into outsourced back-end processing and testing capacity.
Looking ahead, institutional perspectives on the company remain constructive despite broader macroeconomic headwinds impacting price-sensitive consumer electronics segments. Analysts emphasize that ongoing packaging innovations and margin expansion initiatives in advanced assembly and test segments represent critical catalysts for sustained earnings growth. While capital intensity and customer concentration remain key operational variables to monitor, robust demand for advanced packaging and high monthly revenue visibility provide a solid foundation for long-term institutional confidence.
Technical Analysis of ASE Technology Holding Co Ltd (ASX)
Technically, ASE Technology Holding Co Ltd (ASX) shows a MACD (12,26,9) value of -1.781, indicating a neutral signal. The RSI at 43.701 suggests neutral condition and the Williams %R at 80.787 suggests oversold condition. Please monitor closely.
Fundamental Analysis of ASE Technology Holding Co Ltd (ASX)
ASE Technology Holding Co Ltd (ASX) is in the Technology Equipment industry. Its latest annual revenue is $20.71B, ranking 13 in the industry. The net profit is $1.30B, ranking 17 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Strong Buy, with an average price target of $50.02, a high of $58.00, and a low of $42.04.
More details about ASE Technology Holding Co Ltd (ASX)
Company Specific Risks:
- Executive Insider Disposals: Recent disclosure of insider share sales by top corporate officers following the stock's rally to multi-year highs has intensified market concerns regarding near-term upside limitations, accelerating institutional profit-taking.
- Valuation Compression Risk: The stock's trailing price-to-earnings multiple expanded sharply above 50x during its peak run—substantially above its historical median—leaving shares vulnerable to sector-wide chip pullbacks and aggressive valuation repricing.
- Capital Expenditure Burden & Cash Flow Pressure: Massive capital spending required to build out advanced chip packaging and power platforms (PowerSiP and LEAP) has driven free cash flow into negative territory, increasing reliance on external debt financing in a high-yield environment.
- EMS Margin Contraction & Cyclical Demand Exposure: Margin compression within the Electronic Manufacturing Services (EMS) segment, coupled with broader industry reports of spot-market demand softening, threatens near-term operational margins and overall earnings trajectory.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.