


SanDisk Corporation Stock (SNDK) Opened Down by 3.07% on Oct 16: Key Drivers Unveiled



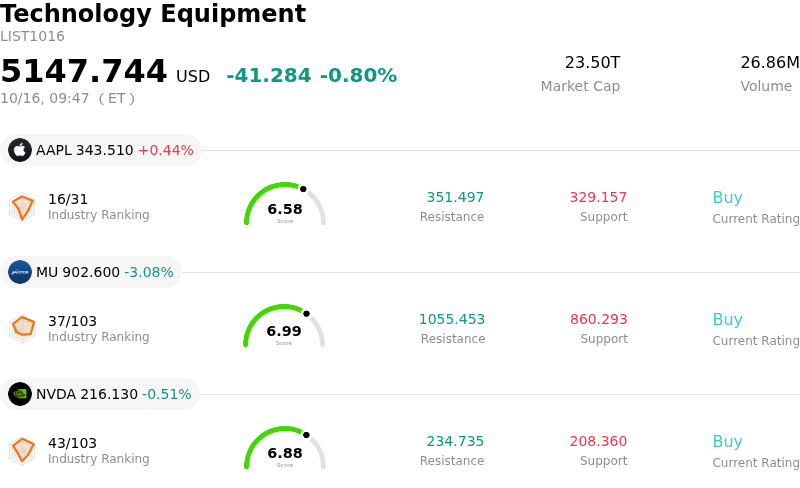
SanDisk Corporation (SNDK) opened down by 3.07%. The Technology Equipment sector is down by 0.80%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Apple Inc (AAPL) up 0.43%; Micron Technology Inc (MU) down 2.87%; NVIDIA Corp (NVDA) down 0.43%.
What is driving SanDisk Corporation (SNDK)’s stock price down today?
SanDisk Corporation experienced downward pressure during the trading session, reflecting broader risk-off sentiment across the semiconductor and enterprise data storage sectors. The primary catalyst driving the pull-back stems from heightened market anxiety surrounding the sustainability of artificial intelligence infrastructure spending. As major cloud service providers face intense scrutiny over capital expenditure returns, investors are questioning whether the recent surge in demand for enterprise solid-state drives and high-capacity storage memory can maintain its upward trajectory. Additional headwinds emerged from macroeconomic pressures, as elevated Treasury yields continue to weigh on high-valuation technology equities.
Adding to the selling pressure are growing concerns regarding competitive dynamics within the global memory landscape. Recent reports highlighting technological progress by international memory producers have stoked investor fears over potential medium-term supply expansion. Although the immediate technological advancements primarily target adjacent memory categories, overarching market sentiment remains hypersensitive to supply-demand balance shifts that could erode pricing power across the broader storage ecosystem. Consequently, institutional investors have shown reluctance to maintain aggressive long positions given the historically cyclical nature of memory pricing.
Intraday volatility was further magnified by positioning adjustments ahead of SanDisk's upcoming quarterly earnings report. Following a substantial multi-month rally, market participants are actively taking profits to manage exposure and lock in gains. Growth and gross margin expectations are elevated, leaving little room for sentiment missteps regarding pricing trends and consumer segment demand. While structural demand from artificial intelligence workloads and long-term customer contracts provide underlying fundamental support, short-term valuation debate and profit-taking continue to dictate market price action.
Technical Analysis of SanDisk Corporation (SNDK)
Technically, SanDisk Corporation (SNDK) shows a MACD (12,26,9) value of -90.769, indicating a sell signal. The RSI at 32.118 suggests neutral condition and the Williams %R at 84.608 suggests oversold condition. Please monitor closely.
Media Coverage of SanDisk Corporation (SNDK)
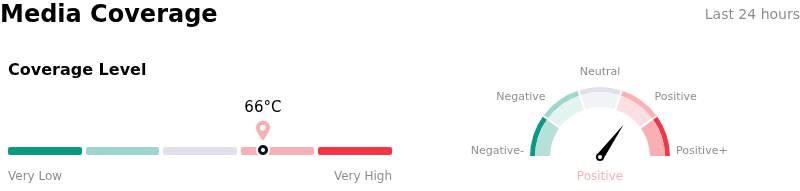
In terms of media coverage, SanDisk Corporation (SNDK) shows a coverage score of 66, indicating a high level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of SanDisk Corporation (SNDK)
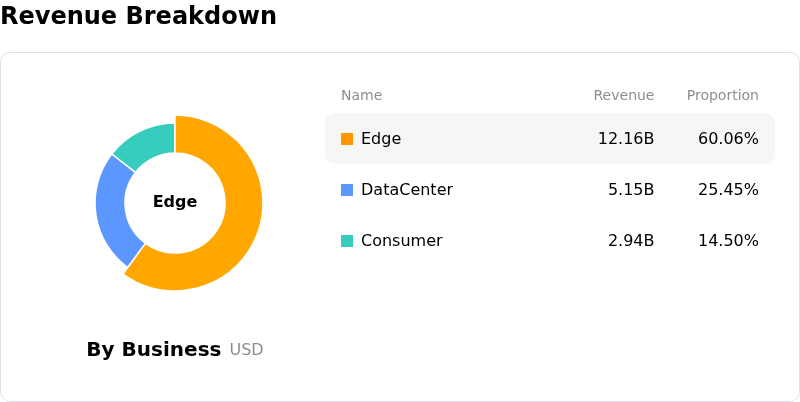
SanDisk Corporation (SNDK) is in the Technology Equipment industry. Its latest annual revenue is $20.25B, ranking 8 in the industry. The net profit is $11.43B, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $2133.62, a high of $3000.00, and a low of $1020.00.
More details about SanDisk Corporation (SNDK)
Company Specific Risks:
- Memory Pricing Normalization and Margin Compression: Recent spot price weakness in NAND flash wafers—including a 2.9% drop in 512Gb TLC spot pricing—has intensified institutional concerns that peak-cycle memory pricing is ending, threatening to erode Sandisk's high gross margins (guided at 83% to 85%) as global supply normalizes.
- Intensifying Foreign Competition and Supply Pressures: Market sentiment has been rattled by progress reports from China's ChangXin Memory Technologies (CXMT) regarding next-generation server-grade memory products, fueling fears of rising global memory supply and eventual ASP erosion across enterprise solid-state storage.
- Consumer Segment Contraction and AI CapEx Exposure: Recent quarter metrics revealed a sharp drop in consumer revenue down to $556 million, leaving company performance heavily dependent on enterprise data center growth and uniquely vulnerable to any slowdown or re-evaluation in cloud AI infrastructure capital expenditure.
- Extreme Valuation Sensitivity and Technical Breakdown: High beta volatility (estimated between 3.5 and 5.2) and a recent breakdown below 20-day and 50-day moving averages have accelerated institutional profit-taking, causing a 20%+ drawdown in recent sessions ahead of the upcoming Q1 FY2027 earnings release.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles









Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.