


Applied Materials Inc Stock (AMAT) Moved Down by 4.39% on Oct 15: Key Drivers Unveiled



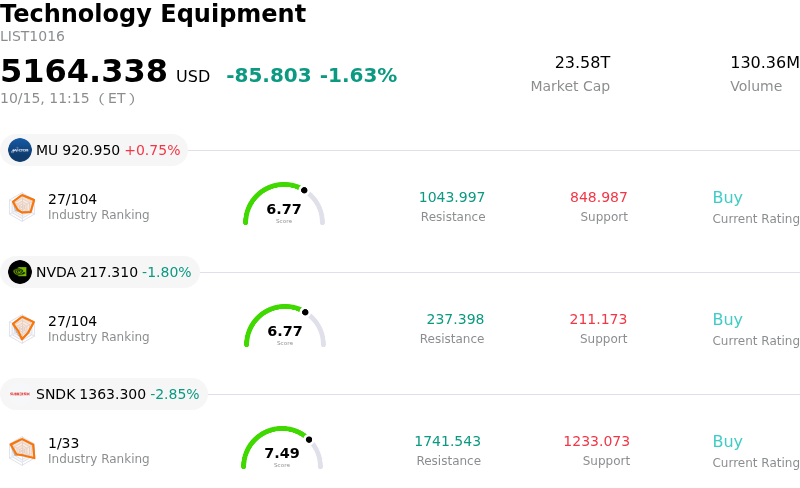
Applied Materials Inc (AMAT) moved down by 4.39%. The Technology Equipment sector is down by 1.63%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) up 0.44%; NVIDIA Corp (NVDA) down 1.97%; SanDisk Corporation (SNDK) down 2.85%.
What is driving Applied Materials Inc (AMAT)’s stock price down today?
Applied Materials experienced noticeable downward pressure and elevated intraday volatility as market participants reacted to ongoing uncertainty regarding near-term capital expenditure timelines across the semiconductor industry. Following recent investor events and strategic updates surrounding the expansion of next-generation research hubs, management highlighted robust multi-year opportunities in artificial intelligence and advanced packaging. However, the decision to withhold specific near-term wafer fab equipment spending targets created friction among institutional investors seeking concrete operational visibility for upcoming quarters. Without firm short-term spending commitments from major foundry and memory customers, market sentiment shifted toward risk reduction.
The selling momentum was further amplified by broader weakness across the semiconductor equipment sector, where peers faced similar valuation recalibrations. Investors remain focused on execution risks tied to global fab construction schedules, energy infrastructure delays, and supply chain constraints that could defer equipment installations despite secular AI demand. Additionally, geopolitical considerations, particularly shrinking sales exposure in mainland China and shifting export policy environments, have added an extra layer of macro complexity, causing traders to take profits and reassess elevated multiples across capital-intensive hardware names.
From an institutional perspective, the long-term thesis for Applied Materials remains supported by its leading market share in materials engineering, high-bandwidth memory packaging, and growing service revenue streams. However, in the short term, the market is demanding greater clarity on how and when AI-driven demand will translate into confirmed equipment purchase orders. Until chipmakers finalize expanded capital expenditure budgets, the stock is likely to remain sensitive to macroeconomic sentiment and sector-wide volatility, presenting a consolidation phase as investors digest long-term targets against near-term demand pacing.
Technical Analysis of Applied Materials Inc (AMAT)
Technically, Applied Materials Inc (AMAT) shows a MACD (12,26,9) value of -17.337, indicating a neutral signal. The RSI at 32.368 suggests neutral condition and the Williams %R at 93.474 suggests oversold condition. Please monitor closely.
Media Coverage of Applied Materials Inc (AMAT)
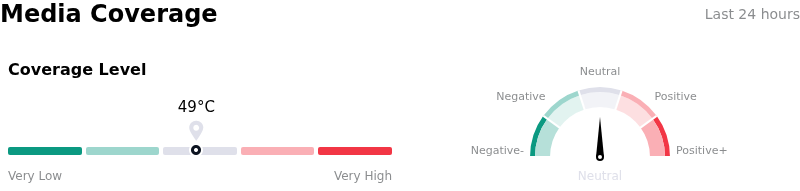
In terms of media coverage, Applied Materials Inc (AMAT) shows a coverage score of 49, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Applied Materials Inc (AMAT)
Applied Materials Inc (AMAT) is in the Technology Equipment industry. Its latest annual revenue is $28.37B, ranking 11 in the industry. The net profit is $7.00B, ranking 8 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $630.90, a high of $900.00, and a low of $308.00.
More details about Applied Materials Inc (AMAT)
Company Specific Risks:
- Omission of Wafer Fab Equipment Spending Forecast: Management declined to issue a specific Wafer Fabrication Equipment spending forecast during its SEMICON West Investor Day presentation, citing ongoing cleanroom space constraints, supply chain delays, and energy infrastructure challenges, which triggered sharp intraday selling.
- Elevated Valuation Premium and Technical Deterioration: Shares extended a multi-session decline below key moving averages as institutional analysts highlighted valuation pressure, with the stock trading at an elevated price-to-earnings multiple of nearly 38x despite a moderating equipment growth cycle.
- Contraction of Revenue from China Due to Export Controls: Tightening U.S. export controls and persistent trade policy restrictions have reduced sales contributions from China from 35% to 28% of total revenue, creating operational headwinds in a key region.
- High Customer Concentration Risk: Applied Materials maintains significant customer concentration, with its top two foundry partners generating over one-third of total net revenue, leaving business performance vulnerable to any capital expenditure cuts by primary clients.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.