


Intel Corp Stock (INTC) Moved Down by 4.24% on Oct 14: Key Drivers Unveiled



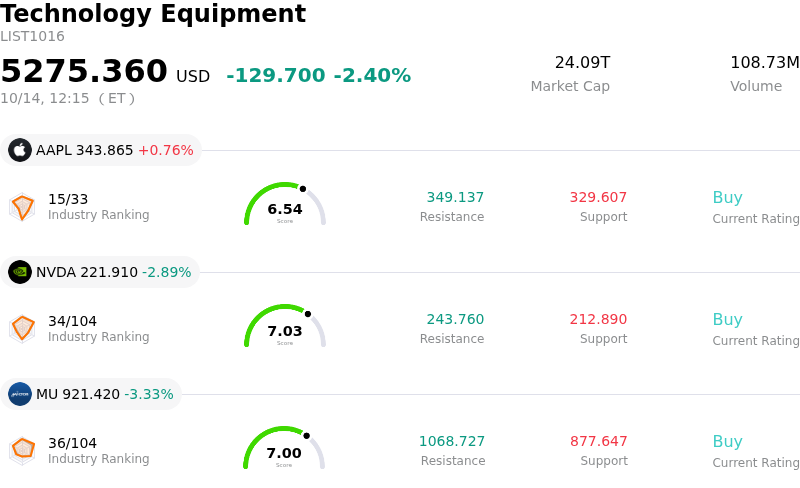
Intel Corp (INTC) moved down by 4.24%. The Technology Equipment sector is down by 2.40%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Apple Inc (AAPL) up 0.76%; NVIDIA Corp (NVDA) down 2.88%; Micron Technology Inc (MU) down 3.25%.
What is driving Intel Corp (INTC)’s stock price down today?
Intel Corporation experienced notable selling pressure during the session, driven primarily by headlines that threaten market expectations surrounding its core turnaround catalyst: Intel Foundry Services. Reports confirming that major technology customer initiatives are in active discussions with competitor Taiwan Semiconductor Manufacturing Company for dedicated production capacity served as a sharp reminder of the intense competition in cutting-edge semiconductor manufacturing. For institutional investors who had priced in potential high-volume wafer allocations from prominent automotive, aerospace, and artificial intelligence ventures, the risk of losing prime foundry share directly challenges the narrative of rapid external customer adoption for Intel's advanced process nodes.
This operational update hit a stock that had already seen significant multiple expansion following a powerful year-to-date rally. With market valuations baking in an aggressive turnaround trajectory, the stock became increasingly susceptible to narrative shocks and profit-taking. Investors remain sensitive to the heavy capital intensity required to build out next-generation fabs, particularly as the foundry segment continues to digest substantial setup costs and operating losses. Compounded by cautious sentiment regarding traditional client computing and PC market momentum ahead of the upcoming earnings release, market participants are reassessing the timeline required for new manufacturing investments to generate meaningful bottom-line accretion.
From an institutional strategy standpoint, Intel's broad strategic position in enterprise data center processors and its pivotal role in re-shoring domestic semiconductor capacity provide a solid long-term foundation. However, near-term price discovery will be dictated by concrete evidence of major third-party customer commitments and margin stabilization. Institutional managers are likely to maintain a disciplined approach, evaluating fab utilization rates and capital allocation efficiency before rebuilding aggressive long exposure. Investors should closely monitor management's upcoming earnings commentary for updated guidance on external foundry order backlogs and node ramp timelines.
Technical Analysis of Intel Corp (INTC)
Technically, Intel Corp (INTC) shows a MACD (12,26,9) value of -5.629, indicating a neutral signal. The RSI at 38.309 suggests neutral condition and the Williams %R at 98.624 suggests oversold condition. Please monitor closely.
Media Coverage of Intel Corp (INTC)
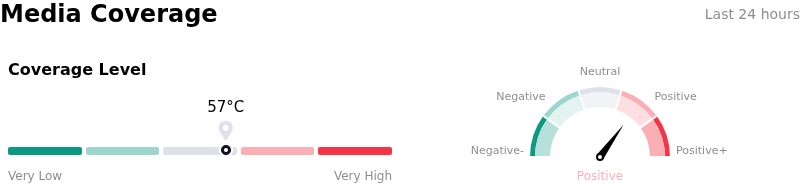
In terms of media coverage, Intel Corp (INTC) shows a coverage score of 57, indicating a moderate level of media attention. The overall market sentiment index is currently in bullish zone.
Fundamental Analysis of Intel Corp (INTC)
Intel Corp (INTC) is in the Technology Equipment industry. Its latest annual revenue is $52.85B, ranking 6 in the industry. The net profit is $-267.00M, ranking 111 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $116.57, a high of $200.00, and a low of $80.00.
More details about Intel Corp (INTC)
Company Specific Risks:
- Foundry Customer Dilution Risk: Recent disclosures indicating that Elon Musk's Terafab initiative is negotiating a dedicated chip production facility with TSMC threaten to dilute Intel's projected role as a primary manufacturing partner for Tesla, SpaceX, and xAI, creating downside pressure on expected foundry pipeline revenues.
- Severe Operating Drag from Foundry Segment: Intel's foundry division continues to weigh heavily on corporate profitability, incurring an operating loss of approximately $2.1 billion while requiring massive ongoing capex spend, keeping net profit margins negative near -20% during its costly turnaround process.
- Elevated Valuation and Multiple Contraction Risk: Despite pulling back over 20% from September highs to test the $100 support level, the stock trades at a premium forward earnings multiple of roughly 48x expected 2027 earnings, leaving little buffer for execution missteps ahead of upcoming quarterly earnings reporting.
- PC Market Softness and Process Node Delays: Weakening end-market demand across the core Personal Computer segment, alongside recurring market concerns regarding process node execution timing, continues to restrict gross margin expansion and challenge near-term revenue recovery expectations.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.