


Lam Research Corp Stock (LRCX) Moved Down by 3.34% on Oct 14: Key Drivers Unveiled



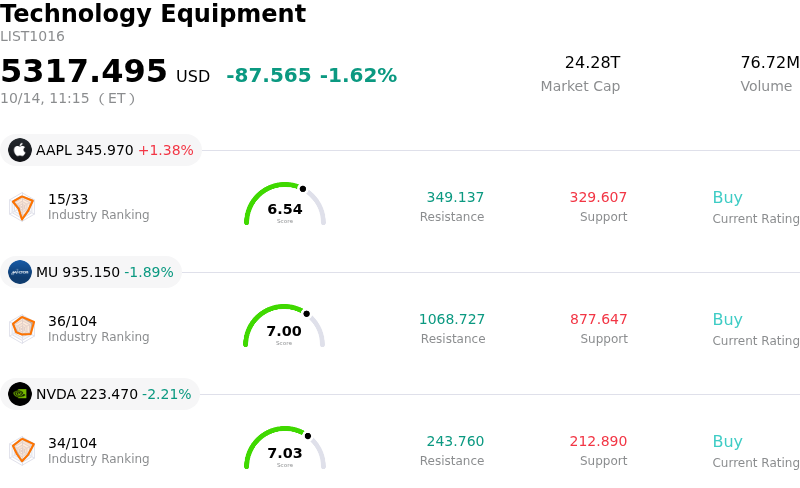
Lam Research Corp (LRCX) moved down by 3.34%. The Technology Equipment sector is down by 1.62%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Apple Inc (AAPL) up 1.40%; Micron Technology Inc (MU) down 1.96%; NVIDIA Corp (NVDA) down 2.24%.
What is driving Lam Research Corp (LRCX)’s stock price down today?
Lam Research experienced downward pressure accompanied by heightened intraday volatility, primarily driven by broader profit-taking across the semiconductor equipment sector. Following an extended rally fueled by aggressive capital expenditures in artificial intelligence infrastructure and advanced wafer fabrication, institutional investors have adopted a more cautious stance. As the industry enters a critical quarterly earnings season, market participants are closely scrutinizing whether capital spending by major memory and logic manufacturers can sustain its recent trajectory, leading to short-term position reductions across chip gear suppliers.
The pullback also reflects tactical positioning ahead of the company's upcoming quarterly financial disclosure. While structural demand for Lam Research's deposition, etch, and clean technologies remains robust due to increasing chip complexity and AI-driven node transitions, elevated valuation multiples have made the stock more vulnerable to sentiment shifts. Furthermore, broader macroeconomic uncertainty and persistent geopolitical considerations regarding global trade controls continue to weigh on market sentiment. Overall, the trading activity reflects short-term sector-wide profit-taking and volatility management rather than a deterioration in the company's core operational fundamentals.
Technical Analysis of Lam Research Corp (LRCX)
Technically, Lam Research Corp (LRCX) shows a MACD (12,26,9) value of -7.215, indicating a neutral signal. The RSI at 38.830 suggests neutral condition and the Williams %R at 97.546 suggests oversold condition. Please monitor closely.
Media Coverage of Lam Research Corp (LRCX)
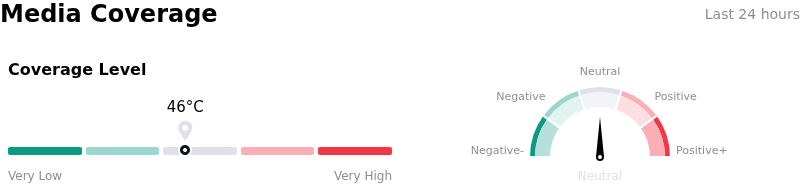
In terms of media coverage, Lam Research Corp (LRCX) shows a coverage score of 46, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Lam Research Corp (LRCX)
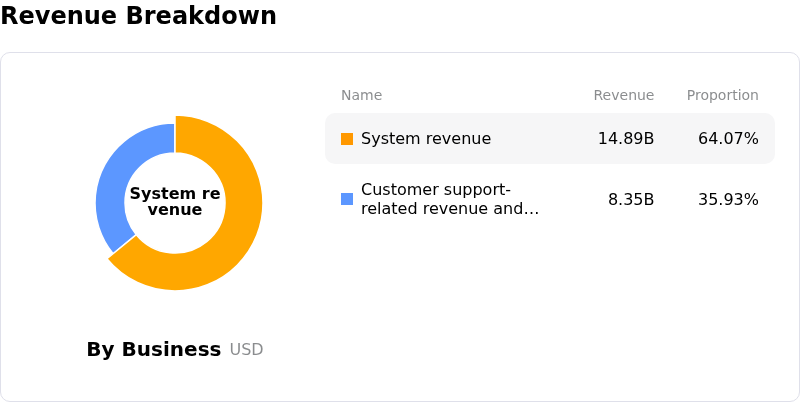
Lam Research Corp (LRCX) is in the Technology Equipment industry. Its latest annual revenue is $23.23B, ranking 12 in the industry. The net profit is $7.27B, ranking 7 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $371.82, a high of $500.00, and a low of $213.00.
More details about Lam Research Corp (LRCX)
Company Specific Risks:
- Valuation Multiples and High Execution Expectations: Trading at elevated valuation multiples well above intrinsic historical medians, the stock faces downside volatility as institutional investors pull back risk ahead of earnings, demanding flawless execution to justify premium pricing.
- China Geopolitical Exposure and Local Competition: Significant revenue concentration in China exposes the business to regulatory risks from tightening U.S. export controls and aggressive market share gains by domestic equipment competitors such as AMEC and Naura.
- High Customer Concentration Risk: Heavy reliance on a small cluster of leading foundries and memory chipmakers, including TSMC, Samsung, and Micron, leaves order visibility vulnerable to customer-specific capital expenditure cuts and fabrication delays.
- WFE Capex Sensitivity and Cyclical Volatility: High operational beta and exposure to memory and logic wafer fabrication equipment spending mean any deceleration in hyperscaler AI infrastructure investments directly threatens forward margin expansion and order backlogs.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.