


Oracle Corp Stock (ORCL) Opened Down by 6.61% on Oct 14: Key Drivers Unveiled



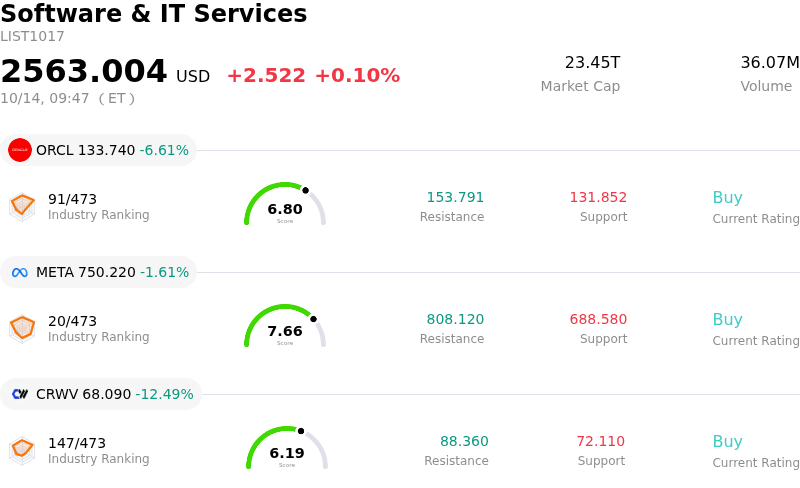
Oracle Corp (ORCL) opened down by 6.61%. The Software & IT Services sector is up by 0.10%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Oracle Corp (ORCL) down 6.61%; Meta Platforms Inc (META) down 1.61%; CoreWeave Inc (CRWV) down 13.01%.
What is driving Oracle Corp (ORCL)’s stock price down today?
Oracle experienced downward selling pressure and heightened intraday volatility as market participants re-evaluated the execution risks and heavy capital commitments associated with the company’s aggressive artificial intelligence cloud infrastructure expansion. A central catalyst weighing on investor sentiment involves operational bottlenecks and escalating power logistics costs for its major data center developments, particularly Project Jupiter in New Mexico. Reports of pipeline regulatory approval delays have highlighted potential reliance on temporary, high-cost fuel delivery methods, sparking fears of near-term margin erosion and operational drag.
Compounding these operational hurdles is heightened market scrutiny over Oracle's substantial remaining performance obligations and artificial intelligence counterparty exposure. Recent industry reports pointing to softer-than-expected revenue figures from key cloud clients, notably OpenAI, have raised questions among institutional investors regarding the actual timeline and cash flow conversion of large-scale compute contracts. Given Oracle's significant capital expenditure commitments to support these workloads, uncertainty over client monetization speed has fueled skepticism around return on invested capital.
From a balance sheet perspective, Oracle’s ongoing transition from traditional high-margin enterprise software toward capital-intensive cloud infrastructure continues to compress gross margins in the near term. This structural shift, combined with elevated debt leverage accumulated to fund rapid data center build-outs, leaves the equity vulnerable to profit-taking and sentiment swings during sector-wide rebalancing. While long-term demand for cloud compute and ongoing enterprise partnerships offer structural growth potential, short-term price dynamics remain tied to management's ability to navigate regulatory hurdles, control infrastructure costs, and demonstrate tangible cash flow generation.
Technical Analysis of Oracle Corp (ORCL)
Technically, Oracle Corp (ORCL) shows a MACD (12,26,9) value of -0.364, indicating a sell signal. The RSI at 42.902 suggests neutral condition and the Williams %R at 81.410 suggests oversold condition. Please monitor closely.
Media Coverage of Oracle Corp (ORCL)
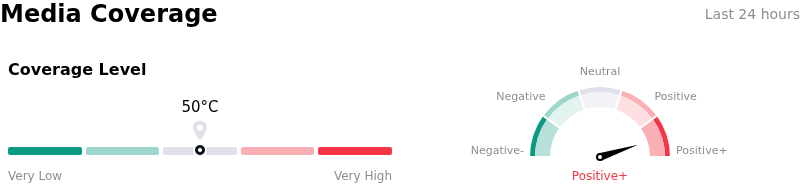
In terms of media coverage, Oracle Corp (ORCL) shows a coverage score of 50, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bullish zone.
Fundamental Analysis of Oracle Corp (ORCL)
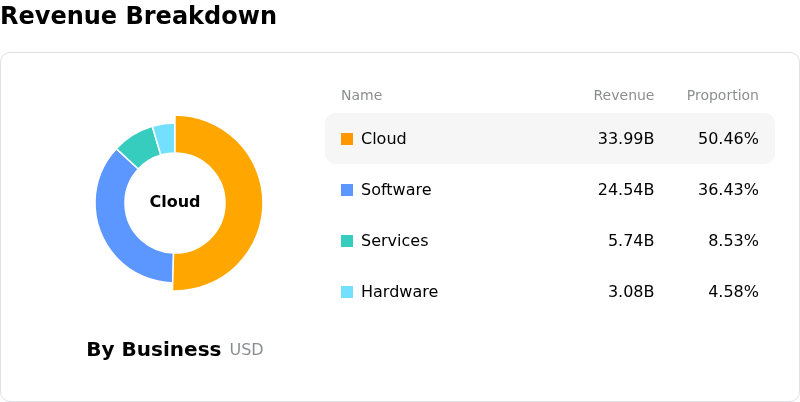
Oracle Corp (ORCL) is in the Software & IT Services industry. Its latest annual revenue is $67.36B, ranking 8 in the industry. The net profit is $16.98B, ranking 6 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $246.26, a high of $400.00, and a low of $110.00.
More details about Oracle Corp (ORCL)
Company Specific Risks:
- Data Center Infrastructure Delays and Logistical Cost Overruns: Regulatory rejection of the Green Chile natural gas pipeline route in New Mexico forced Oracle to declare force majeure and resort to trucking fuel to its 2.45-gigawatt Project Jupiter site. Trucking natural gas quadruples fuel costs relative to pipeline delivery, introducing substantial operational margin pressure and delivery delays for contracted AI compute capacity.
- High Financial Leverage and Credit Rating Vulnerability: Aggressive capital expenditures for AI infrastructure expansion have pushed Oracle's debt-to-equity ratio to 2.3x while free cash flow remains negative. S&P Global's credit rating downgrade to BBB- underscores heightened financial leverage risk, increasing borrowing costs as the company seeks additional debt financing.
- Customer Concentration and Softening AI Partner Monetization: Downside risks to cloud utilization intensified following disclosures that anchor AI customer OpenAI's annualized revenue run-rate reached $50 billion, missing prior market expectations of $68 billion. Slower revenue scaling among core AI tenants threatens Oracle's payback periods on massive GPU infrastructure investments.
- Regulatory Approval Hurdles and Fixed Power Contract Commitments: Oracle faces ongoing regulatory friction, including pending FERC pipeline approvals and local county commission scrutiny regarding infrastructure proposals. Furthermore, proposed energy service agreements obligate Oracle to $10 million in annual minimum power payments for ten years regardless of actual draw, embedding fixed liabilities amidst potential operational delays.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.