


Lam Research Corp Stock (LRCX) Moved Down by 3.38% on Oct 13: A Full Analysis



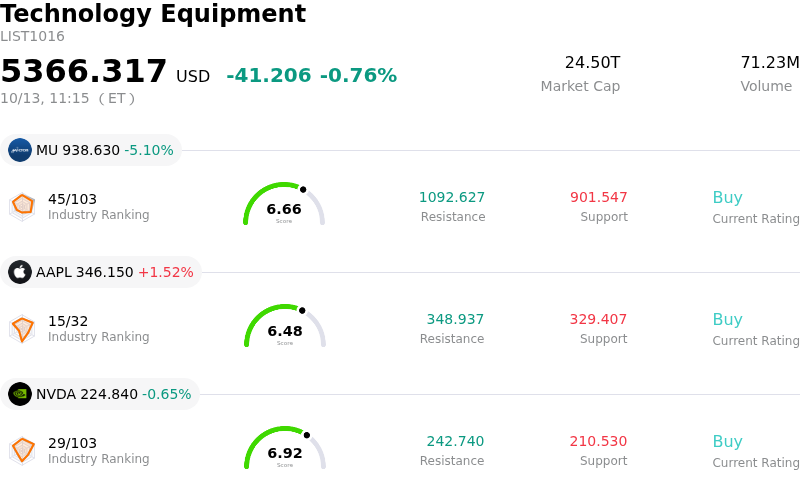
Lam Research Corp (LRCX) moved down by 3.38%. The Technology Equipment sector is down by 0.76%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) down 5.03%; Apple Inc (AAPL) up 1.51%; NVIDIA Corp (NVDA) down 0.64%.
What is driving Lam Research Corp (LRCX)’s stock price down today?
Lam Research Corporation experienced downside pressure today, driven primarily by short-term profit-taking and cautious portfolio rebalancing within the broader semiconductor capital equipment sector. Following a massive multi-quarter rally propelled by aggressive global artificial intelligence infrastructure spending, market participants appear to be taking profits off the table ahead of the company's upcoming quarterly earnings announcement. Given the stock's elevated valuation relative to historical multiples, investor expectations for revenue and margin expansion remain exceptionally high, creating heightened sensitivity to pre-earnings repositioning and short-term volatility.
Beyond broader sector dynamics, persistent macroeconomic and geopolitical concerns continue to weigh on market sentiment surrounding chip equipment manufacturers. Investors remain cautious regarding ongoing export restrictions on advanced semiconductor technology to China, which has historically represented a major revenue contributor for etch and deposition tools. Although demand for advanced logic and high-bandwidth memory equipment from global tier-one fabricators remains strong, the ongoing structural mix shift away from mainland Chinese customer spending continues to introduce an underlying overhang that volatility-sensitive institutional funds are monitoring closely.
Despite the intraday pullback, fundamental industry drivers supporting the company's core business remain structurally sound. The rapid rise of complex microarchitecture, advanced packaging, and memory transitions continues to drive high equipment intensity across global wafer fabrication facilities. While near-term stock movements reflect heightened volatility and pre-earnings risk management among institutional traders, the broader multi-year thesis remains tied to capital expenditure cycles among major hyperscalers and leading-edge chipmakers.
Technical Analysis of Lam Research Corp (LRCX)
Technically, Lam Research Corp (LRCX) shows a MACD (12,26,9) value of -4.427, indicating a neutral signal. The RSI at 41.981 suggests neutral condition and the Williams %R at 96.854 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Lam Research Corp (LRCX)
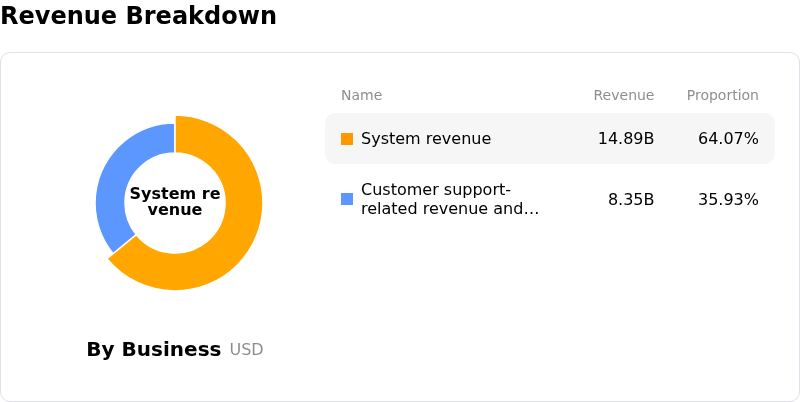
Lam Research Corp (LRCX) is in the Technology Equipment industry. Its latest annual revenue is $23.23B, ranking 12 in the industry. The net profit is $7.27B, ranking 7 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $371.82, a high of $500.00, and a low of $213.00.
More details about Lam Research Corp (LRCX)
Company Specific Risks:
- Pre-Earnings Position Trimming and Multiple Contraction: Intraday selling pressure and institutional de-risking have intensified ahead of the October 21 quarterly financial report, driven by concerns over stretched valuation metrics, including a forward P/E ratio exceeding 33x compared to historical averages.
- China Revenue Contraction and Geopolitical Trade Controls: Lam Research faces revenue deceleration as its China market revenue contribution declined from 34% to 26%, with ongoing trade tensions and U.S. export control restrictions threatening short-term equipment shipments to regional fabrication facilities.
- Memory Capex Cyclicality and Concentration Risk: Heavy reliance on DRAM and 3D NAND wafer fabrication equipment (WFE) leaves the company highly vulnerable to sudden capital spending pullbacks or project pauses by key foundry and memory clients such as TSMC, Samsung, and Micron.
- R&D Expense Intensity and Margin Pressure: Elevated research and development expenditures—which currently account for roughly 67% of total operating expenses—pose downside risks to operating margins and profitability if tool adoption rates or revenue growth slow down near-term.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.