


TTM Technologies Inc Stock (TTMI) Moved Down by 9.65% on Oct 12: Facts Behind the Movement



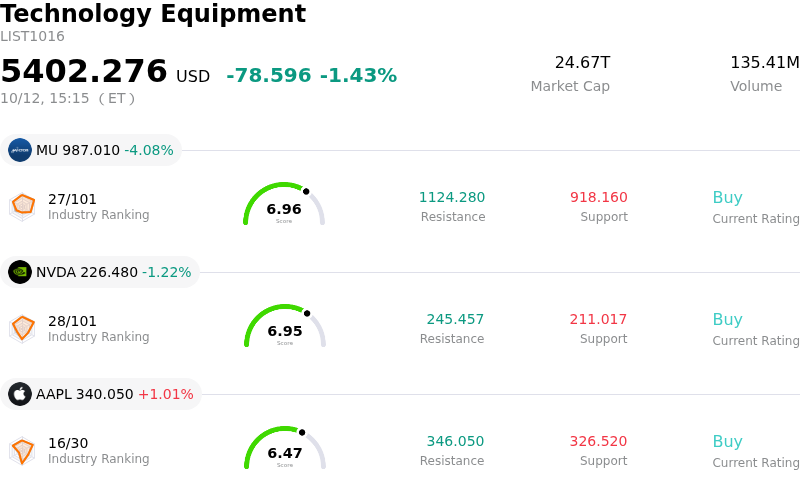
TTM Technologies Inc (TTMI) moved down by 9.65%. The Technology Equipment sector is down by 1.43%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) down 4.08%; NVIDIA Corp (NVDA) down 1.22%; Apple Inc (AAPL) up 1.01%.
What is driving TTM Technologies Inc (TTMI)’s stock price down today?
TTM Technologies experienced notable downward price pressure following the company's morning announcement of an incremental $400 million strategic investment plan to expand printed circuit board production across key facilities in China and Malaysia. While the capital deployment is designed to capture surging demand for artificial intelligence infrastructure, data center, and networking hardware, the immediate market reaction reflects investor hesitation regarding short-term capital intensity. Because this investment adds to an existing multi-year capital commitment, market participants reacted to the increased capital expenditure burden and potential near-term cash flow compression.
A major driver of the negative sentiment is the absence of concrete short-term revenue or margin targets accompanying the announcement. Management intends to leverage a brownfield approach by retrofitting existing facilities rather than constructing new sites to shorten the path to production, but investors are waiting for more granular financial guidance, which is deferred until the upcoming quarterly earnings release. Without immediate quantitative benchmarks to justify the heightened capital outlay, traders preferred to de-risk their positions, opting to evaluate the multi-year return on invested capital once formal projections are detailed.
Prior to this announcement, the stock had experienced a strong performance run driven by optimism around AI hardware integration and aerospace defense backlogs, leading to elevated valuation multiples relative to historical averages. The news served as a trigger for profit-taking in an environment where investors are increasingly sensitive to valuation levels and corporate debt loads. Furthermore, expanding operational capacity heavily within Asian facilities raises lingering geopolitical and supply chain execution concerns among institutional investors. Until management provides greater clarity on margin expansion and revenue conversion during its earnings call, the stock remains vulnerable to volatility as the market balances long-term AI growth opportunities against near-term cash commitment realities.
Technical Analysis of TTM Technologies Inc (TTMI)
Technically, TTM Technologies Inc (TTMI) shows a MACD (12,26,9) value of -2.389, indicating a neutral signal. The RSI at 37.402 suggests neutral condition and the Williams %R at 91.645 suggests oversold condition. Please monitor closely.
Fundamental Analysis of TTM Technologies Inc (TTMI)
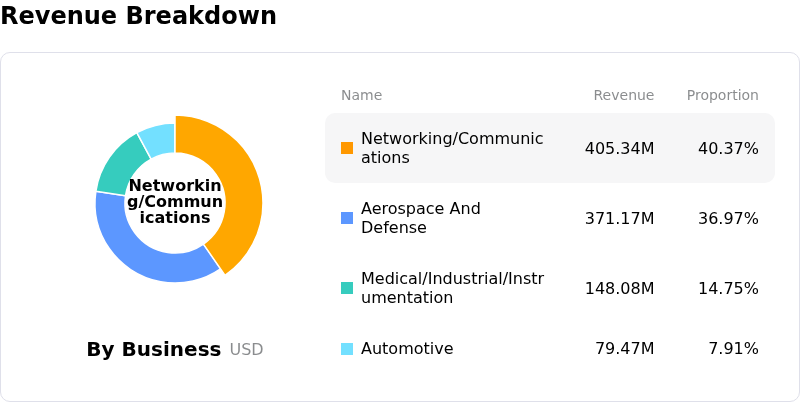
TTM Technologies Inc (TTMI) is in the Technology Equipment industry. Its latest annual revenue is $2.91B, ranking 32 in the industry. The net profit is $177.45M, ranking 35 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $203.83, a high of $236.00, and a low of $175.00.
More details about TTM Technologies Inc (TTMI)
Company Specific Risks:
- Substantial Capital Expenditure & Geopolitical Exposure: Announcement of a $400 million incremental investment plan to expand manufacturing capacity in China and Malaysia triggered a sharp intraday share decline exceeding 10%, highlighting market anxiety over rising capital intensity and heightened geopolitical risk in overseas operating regions.
- Elevated Debt Obligations & Acquisition Financing: Following the $1.1 billion acquisition of Epiq Solutions and a $500 million senior notes issuance, escalating leverage and interest obligations increase financial vulnerability, leaving less flexibility should market demand cool or integration costs escalate.
- Valuation Premium & Institutional Downgrades: Trading at a forward price-to-earnings multiple well above historical averages, the stock has prompted analyst downgrades from Strong Buy to Hold, driving institutional profit-taking as momentum indicators break below key moving averages.
- High Customer Concentration & Free Cash Flow Risk: With its top 10 clients accounting for 55% of total net sales, the business model faces high volatility and cash flow strain if major data center or defense customers trim capital expenditures or demand pricing concessions.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.