


Cerebras Systems Ord Shs Class A (Proposed) Stock (CBRS) Moved Down by 10.28% on Oct 12: Key Drivers Unveiled



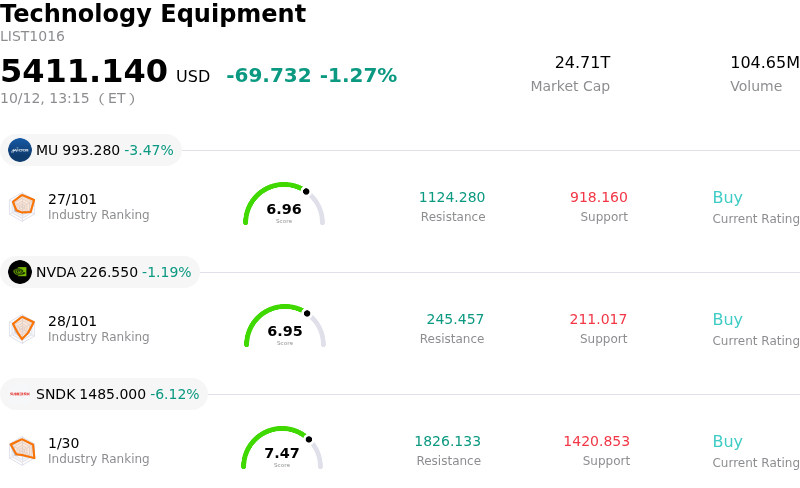
Cerebras Systems Ord Shs Class A (Proposed) (CBRS) moved down by 10.28%. The Technology Equipment sector is down by 1.27%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Micron Technology Inc (MU) down 3.47%; NVIDIA Corp (NVDA) down 1.19%; SanDisk Corporation (SNDK) down 6.12%.
What is driving Cerebras Systems Ord Shs Class A (Proposed) (CBRS)’s stock price down today?
Cerebras Systems experienced a sharp downward movement as high-valuation artificial intelligence hardware names faced broad profit-taking and heightened investor scrutiny over near-term monetization. As a recent public market entrant operating in the high-performance computing space, the stock remains particularly sensitive to shifts in market risk appetite and changes in the competitive narrative surrounding AI accelerator deployment.
A primary catalyst weighing on investor confidence stems from persistent debates regarding customer adoption and competition against established GPU incumbents. Recent industry reports indicating that key flagship generative AI inference workloads continue to rely heavily on incumbent chip architectures rather than alternative wafer-scale solutions have intensified fears over revenue concentration and contract ramp-up timelines. Additionally, recent insider filings disclosing executive stock sales under trading plans alongside venture capital share distributions have increased available floating supply in the market, amplifying downward pressure during periods of weaker market liquidity.
From a fundamental standpoint, while Cerebras maintains a substantial backlog of remaining performance obligations and significant cash reserves to fund platform expansion, its substantial cash burn rate and negative operating margins make the valuation fragile during semiconductor sector pullbacks. Institutional portfolio managers appear to be de-risking positions as current valuation multiples demand flawless operational execution. Until the company demonstrates broader commercial diversification, structural gross margin expansion, and sustained adoption wins across top-tier enterprise clients, the stock is likely to remain subject to heightened volatility driven by macro sentiment and industry news flow.
Technical Analysis of Cerebras Systems Ord Shs Class A (Proposed) (CBRS)
Technically, Cerebras Systems Ord Shs Class A (Proposed) (CBRS) shows a MACD (12,26,9) value of -7.289, indicating a sell signal. The RSI at 31.579 suggests neutral condition and the Williams %R at 99.419 suggests oversold condition. Please monitor closely.
Fundamental Analysis of Cerebras Systems Ord Shs Class A (Proposed) (CBRS)
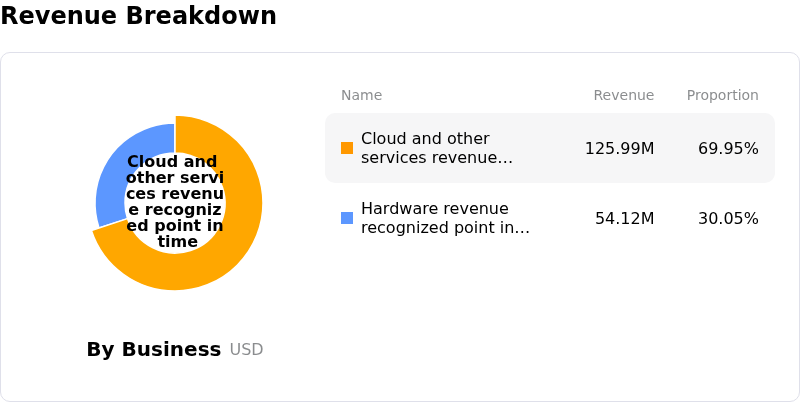
Cerebras Systems Ord Shs Class A (Proposed) (CBRS) is in the Technology Equipment industry. Its latest annual revenue is $509.99M, ranking 7 in the industry. The net profit is $87.88M, ranking 2 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $291.64, a high of $330.00, and a low of $209.00.
More details about Cerebras Systems Ord Shs Class A (Proposed) (CBRS)
Company Specific Risks:
- Customer Concentration and Competitive Displacement: Intraday volatility surged following reports that key customer OpenAI shifted high-speed AI workloads for its newest model tier away from Cerebras hardware and toward rival Nvidia GPUs, highlighting severe revenue concentration risk and competitive vulnerability.
- Post-Lockup Insider Selling Pressure: Following the expiration of the post-IPO lockup period, executive disclosures revealed $387.7 million in insider share sales by top leadership, accelerating a stock decline to a new 52-week low well below its $185 IPO price.
- Severe Earnings Drag and Profitability Miss: The company posted a quarterly adjusted net loss of $2.98 per share—drastically missing consensus estimates of a $0.21 loss per share—and recorded a GAAP operating loss of $477.2 million, emphasizing deep structural margin pressure.
- Capital Intensity and Debt-Fueled Cash Burn: Aggressive infrastructure scaling requirements—including plans to expand manufacturing capacity tenfold and fund over 600 MW in contracted data center capacity—are driving high cash burn and rising debt obligations, magnifying downside operational risk.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.