


Danaher Corp Stock (DHR) Moved Up by 3.32% on Oct 5: What Investors Need To Know



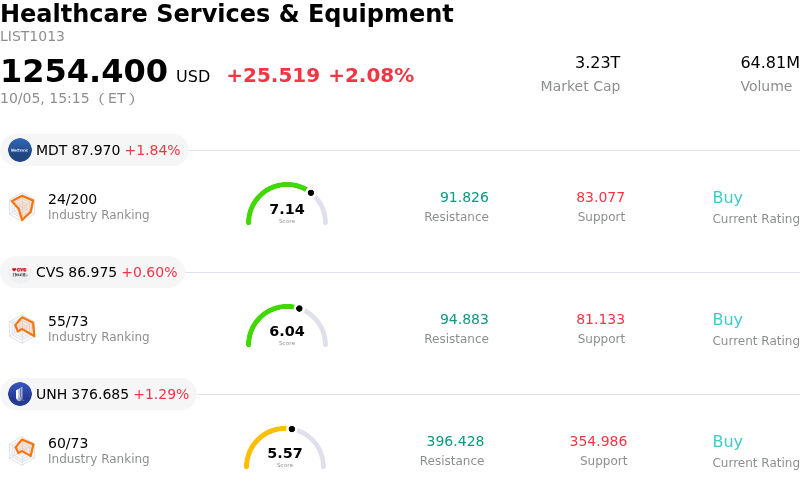
Danaher Corp (DHR) moved up by 3.32%. The Healthcare Services & Equipment sector is up by 2.08%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Medtronic PLC (MDT) up 1.84%; CVS Health Corp (CVS) up 0.60%; Unitedhealth Group Inc (UNH) up 1.29%.
What is driving Danaher Corp (DHR)’s stock price up today?
Danaher Corporation experienced a strong upward move accompanied by intraday volatility, driven primarily by favorable sell-side revisions and broader macroeconomic tailwinds across the life sciences domain. Wall Street analysts, notably RBC Capital, raised their price targets on the company while reiterating bullish ratings, citing an increasingly constructive setup ahead of third-quarter earnings and expanding valuation multiples across life sciences equipment peers. This positive analyst sentiment was further supported by industry data indicating a sharp rebound in biopharmaceutical funding, which alleviates recent market concerns regarding client capital spending delays and deferred bioprocessing shipments.
Market sentiment around the stock also stabilized following the official management handoff. While the equity faced short-term downward pressure at the start of the quarter after Julie Sawyer Montgomery formally assumed the role of Chief Executive Officer on October 1, investors quickly digested the transition. Confidence was restored by the structured, pre-announced succession plan and the continued involvement of outgoing leadership in an advisory capacity. Additionally, quarterly institutional holding reports revealed significant position building by major asset managers, signaling strong institutional backing during this cyclical transition phase.
Looking forward, momentum is being sustained by position building ahead of the upcoming third-quarter earnings report. Buyers stepped in to capitalize on short-term pullbacks following the recent ex-dividend date, pushing technical indicators back toward bullish alignment above key moving averages. While lingering risks remain around equipment delivery timing and international commercial pricing, the convergence of strategic leadership stability, firming end-market fundamentals, and analyst target hikes has reinvigorated buying interest.
Technical Analysis of Danaher Corp (DHR)
Technically, Danaher Corp (DHR) shows a MACD (12,26,9) value of -0.444, indicating a neutral signal. The RSI at 57.932 suggests neutral condition and the Williams %R at 30.812 suggests buy condition. Please monitor closely.
Fundamental Analysis of Danaher Corp (DHR)
Danaher Corp (DHR) is in the Healthcare Services & Equipment industry. Its latest annual revenue is $24.57B, ranking 7 in the industry. The net profit is $3.61B, ranking 4 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $230.16, a high of $310.00, and a low of $200.00.
More details about Danaher Corp (DHR)
Company Specific Risks:
- CEO Leadership Transition Friction: The official takeover by Julie Sawyer Montgomery as President and Chief Executive Officer on October 1, 2026, succeeding Rainer Blair, introduces operational execution risk and leadership transition friction as the company navigates a cyclical downturn in demand across life sciences and diagnostics.
- Bioprocessing Equipment Order Deferrals: Persistent customer project delays resulting in biopharmaceutical clients postponing over $100 million of bioprocessing equipment and chromatography resin shipments into 2027 continue to constrain core revenue growth outlook and near-term top-line realization.
- Margin Compression and Masimo Acquisition Debt: The integration of the $9.9 billion Masimo Corporation acquisition has increased balance sheet debt leverage and extended operations into lower-margin patient monitoring, contributing to operating margin contraction and profitability concerns.
- China Procurement and Pricing Headwinds: Ongoing regulatory volume-based procurement policy changes and commercial pricing pressures in China impose an estimated $75 million to $100 million direct revenue drag, exposing the stock's elevated valuation multiple to downside re-rating.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles






Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.