


SpaceX Stock (SPCX) Opened Up by 3.37% on Oct 5: Key Drivers Unveiled



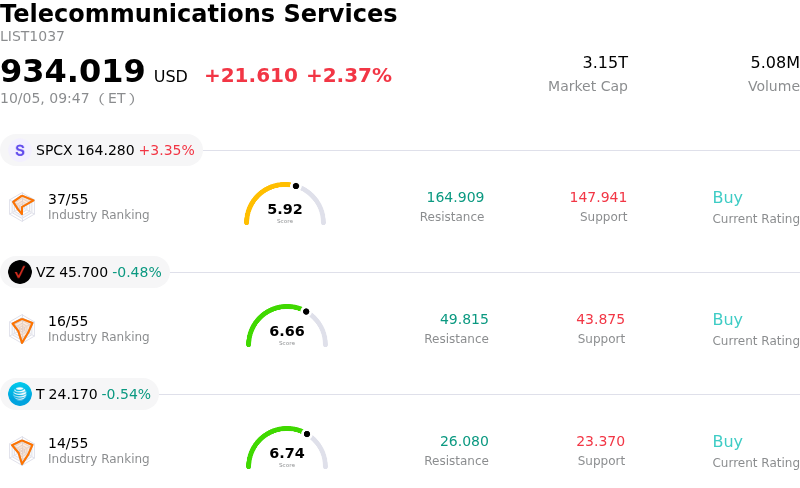
SpaceX (SPCX) opened up by 3.37%. The Telecommunications Services sector is up by 2.37%. The company outperformed the industry. Top 3 stocks by turnover in the sector: SpaceX (SPCX) up 3.37%; Verizon Communications Inc (VZ) down 0.48%; AT&T Inc (T) down 0.54%.
What is driving SpaceX (SPCX)’s stock price up today?
Space Exploration Technologies Corp displayed strong upward momentum alongside heightened intraday volatility, driven by a convergence of favorable analyst coverage, fundamental operational achievements, and strategic positioning in space-based infrastructure and artificial intelligence. Investor sentiment was bolstered by a positive research note from Morgan Stanley, which highlighted the company as appealingly valued ahead of the anticipated Starship Flight 15 test. The investment bank maintained a bullish long-term outlook, citing potential upside as upcoming flight tests and operational scaling help address critical orbital bottlenecks in power and processing infrastructure.
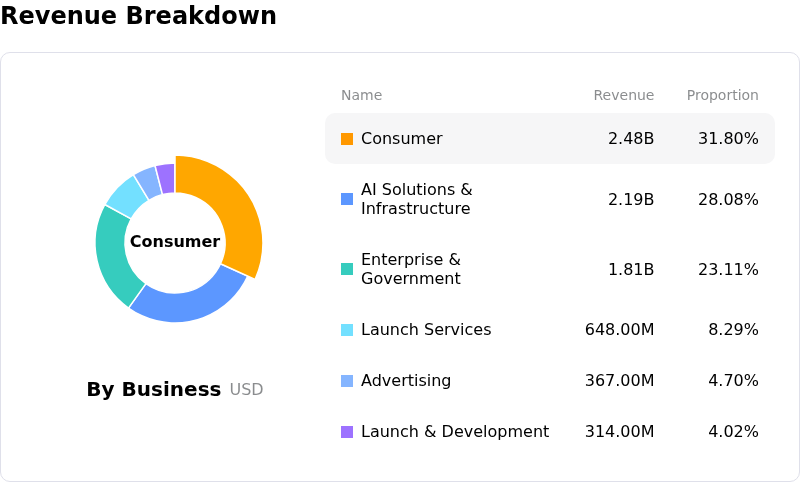
Fundamental momentum remains anchored by recent operational milestones, notably Starship achieving its first successful orbital deployment of next-generation Starlink V3 satellites. This expansion enhances the capacity of the company's high-margin global broadband network, which serves as its primary revenue driver. Simultaneously, investor interest has broadened into space-based computing following joint orbital missions testing advanced processing hardware in space. Management's recent commentary clarifying that commercial enterprise customers generate the vast majority of annual revenue has also reassured institutional investors regarding commercial viability and reduced dependence on government defense contracts.
The noticeable intraday volatility reflects rapid rotation and tactical position adjustments among both institutional and retail traders. Following a strong multi-day rally, price action experienced short-term friction near technical resistance boundaries. Furthermore, active trading across single-stock leveraged and inverse exchange-traded funds tied to the underlying ticker contributed to amplified intra-day price swings. Despite these short-term fluctuations, broader market focus remains fixed on recurring subscriber growth from satellite internet services, execution timelines for upcoming launch cadence, and expanding monetization opportunities across satellite communications and orbital computing.
Technical Analysis of SpaceX (SPCX)
Technically, SpaceX (SPCX) shows a MACD (12,26,9) value of 1.425, indicating a buy signal. The RSI at 65.020 suggests neutral condition and the Williams %R at 0.449 suggests overbought condition. Please monitor closely.
Fundamental Analysis of SpaceX (SPCX)
SpaceX (SPCX) is in the Telecommunications Services industry. Its latest annual revenue is $18.67B, ranking 10 in the industry. The net profit is $-4.94B, ranking 61 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $228.26, a high of $800.00, and a low of $100.00.
More details about SpaceX (SPCX)
Company Specific Risks:
- Customer Concentration and Short Contract Cancellation Windows: Revenue exposure has concentrated sharply, with a single AI hosting client accounting for nearly 20% of quarterly revenue, while major contracts like the Anthropic agreement permit client cancellation on just 90 days' notice.
- Strict Infrastructure Delivery Schedules and Penalty Provisions: Major commercial hosting agreements, such as the multi-year Google compute capacity deal, carry stringent rollout deadlines where failing to hit target GPU infrastructure milestones allows clients to terminate contracts or reduce compensation.
- Hardware Supply Chain Reliance on Third-Party Vendors: Rapid expansion of AI compute infrastructure depends heavily on external chip suppliers for next-generation GPU allocations, leaving operations vulnerable to supply chain delays outside of the company's direct control.
- Slower Contract Ramps and Massive Data Center Cash Burn: Analysts have reduced near-term AI revenue estimates through 2027 due to slower contract implementation schedules alongside substantial capital expenditure requirements for scaling gigawatt-scale data center infrastructure.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles






Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.