


FPS.NB Stock (FPS) Moved Up by 7.82% on Oct 2: Key Drivers Unveiled



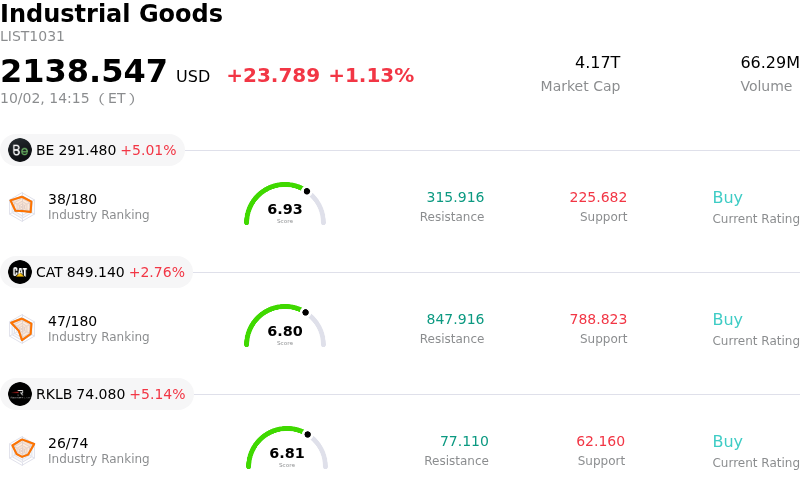
FPS.NB (FPS) moved up by 7.82%. The Industrial Goods sector is up by 1.12%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Bloom Energy Corp (BE) up 4.95%; Caterpillar Inc (CAT) up 2.76%; Rocket Lab USA Inc (RKLB) up 5.14%.
What is driving FPS.NB (FPS)’s stock price up today?
Forgent Power Solutions experienced strong upward price momentum driven primarily by a high-profile bullish analyst initiation from Bernstein. The firm initiated coverage on the electrical distribution equipment manufacturer with an Outperform rating, pointing to a valuation disconnect between the stock and its long-term structural growth opportunities. Wall Street responded enthusiastically to the coverage, which emphasized that public markets have not fully priced in the company's multi-year earnings potential stemming from accelerating demand across artificial intelligence infrastructure and data center buildouts.
At the core of the constructive investment thesis is the company's pure-play exposure to critical infrastructure, with approximately four-fifths of its revenue tied directly to data centers and the power grid. Analysts highlighted the ongoing secular shift toward modular data center construction as a pivotal growth catalyst that could significantly expand the company's content value per megawatt over the coming years. Furthermore, projected earnings growth rates above broader Wall Street consensus and positive operational efficiency gains, such as improved factory utilization and expanding margins, bolstered institutional confidence in the stock's long-term trajectory.
This analyst optimism builds upon strong fundamental momentum established following the company's recent record full-year financial results, which exceeded guidance boundaries and yielded an all-time high order backlog. While high valuation multiples have contributed to intraday price volatility, robust demand for custom-engineered transformers, switchgear, and integrated powertrain solutions continues to underpin investor sentiment. A supportive broader market backdrop following key economic data releases provided additional tailwinds that sustained buying interest throughout the session.
Technical Analysis of FPS.NB (FPS)
Technically, FPS.NB (FPS) shows a MACD (12,26,9) value of 0.866, indicating a buy signal. The RSI at 61.065 suggests neutral condition and the Williams %R at 1.427 suggests overbought condition. Please monitor closely.
Fundamental Analysis of FPS.NB (FPS)
FPS.NB (FPS) is in the Industrial Goods industry. Its latest annual revenue is $1.42B, ranking 95 in the industry. The net profit is $81.84M, ranking 88 in the industry. Company Profile
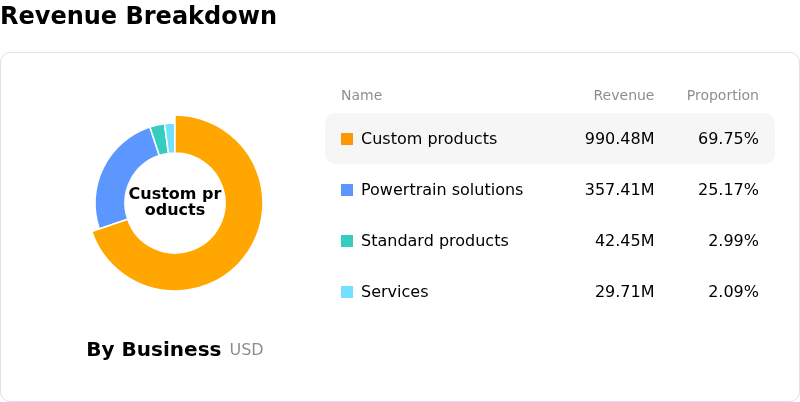
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $56.50, a high of $76.00, and a low of $44.00.
More details about FPS.NB (FPS)
Company Specific Risks:
- Elevated Valuation and Multiple Contraction Risk: Despite recent stock pullbacks, FPS trades at an extreme trailing P/E ratio exceeding 100x, leaving the equity sharply vulnerable to sell-offs and volatility whenever broader market sentiment sours on high-multiple AI infrastructure names.
- Private Equity Monetization and Share Dilution Overhang: Controlling private equity sponsor Neos Partners and insiders continue to exert downside pressure through large-scale secondary offerings and share liquidations, generating lingering share dilution and market supply overhang.
- Production Capacity Expansion and Backlog Execution Risk: Converting the company's $3.0 billion order backlog into recognized revenue relies heavily on seamlessly scaling manufacturing capacity, including a $35 million expansion at its Tijuana facility, where any operational delays or supply chain bottlenecks would harm earnings trajectory.
- Escalating Working Capital Requirements and Debt Burden: Supporting 90%+ annual top-line growth has rapidly expanded inventory and accounts receivable demands, placing heavy pressure on operational cash flow while the company services over $580 million in total outstanding debt.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles







Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.