


Twilio Inc Stock (TWLO) Moved Down by 7.15% on Sep 25: What Signal Does It Send?



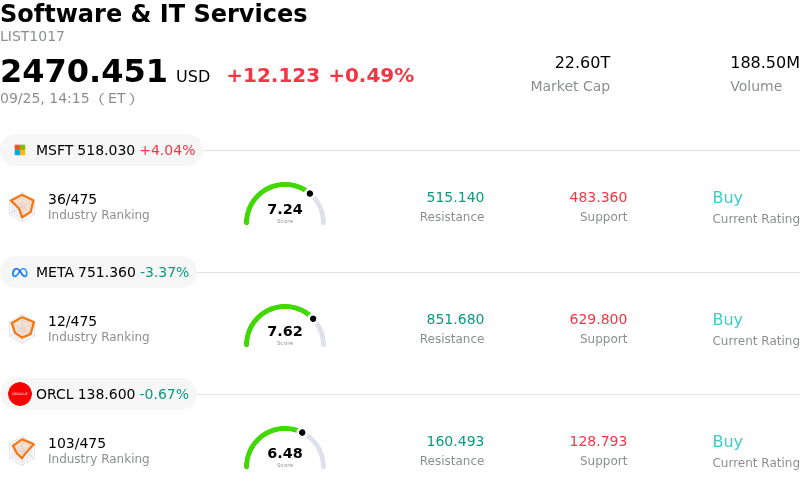
Twilio Inc (TWLO) moved down by 7.15%. The Software & IT Services sector is up by 0.49%. The company underperformed the industry. Top 3 stocks by turnover in the sector: Microsoft Corp (MSFT) up 4.03%; Meta Platforms Inc (META) down 3.38%; Oracle Corp (ORCL) down 0.67%.
What is driving Twilio Inc (TWLO)’s stock price down today?
Twilio experienced significant downward pressure following a notable Wall Street downgrade from HSBC, which lowered its rating on the communications software platform to Reduce. The research note highlighted growing skepticism regarding the company's capability to capture high-margin revenue from the rapid expansion of artificial intelligence infrastructure. While the proliferation of autonomous AI agents, including Meta Platforms' Muse AI assistant, is expanding the sheer volume of voice calls, transactional messages, and user authentication steps, analysts cautioned that higher traffic does not automatically yield proportional top-line monetization or expanding profit margins for software intermediaries.
The downgrade underscored structural concerns about where Twilio fits in the value chain of AI-enabled engagement. Equity research indicated that the platform's role in routing AI traffic could remain largely focused on lower-margin underlying connectivity and carrier handoffs. In this domain, the business faces strong competition from alternative cloud communications providers and wholesale carriers. Additionally, major tech enterprise customers retain the leverage to establish direct network connections with carriers or renegotiate bandwidth rates, which risks capping Twilio's margin expansion potential even as overall system throughput increases.
This research commentary triggered profit-taking and valuation compression after a period of strong momentum. The equity had experienced a powerful rally leading into late September, fueled by encouraging quarterly operational updates, raised organic growth guidance, and enthusiasm surrounding enterprise AI capabilities. However, the rapid multiple expansion left the stock sensitive to doubts regarding execution and pricing power. Coupled with historical insider selling activity over prior months, institutional investors trimmed positions to manage risk, re-evaluating whether market expectations had temporarily outpaced fundamental earnings potential.
Technical Analysis of Twilio Inc (TWLO)
Technically, Twilio Inc (TWLO) shows a MACD (12,26,9) value of 10.575, indicating a buy signal. The RSI at 63.639 suggests neutral condition and the Williams %R at 32.163 suggests buy condition. Please monitor closely.
Fundamental Analysis of Twilio Inc (TWLO)
Twilio Inc (TWLO) is in the Software & IT Services industry. Its latest annual revenue is $5.07B, ranking 62 in the industry. The net profit is $33.83M, ranking 188 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $255.85, a high of $330.00, and a low of $135.50.
More details about Twilio Inc (TWLO)
Company Specific Risks:
- Wall Street Downgrade on Overextended Valuation: HSBC downgraded TWLO from Hold to Reduce with a $211 price target, citing that market speculation surrounding Meta's Muse AI agent has pushed the stock's valuation to unsustainable levels relative to near-term fundamental growth.
- Limited High-Margin AI Revenue Capture: Wall Street analysis indicates that while AI agents increase overall messaging and voice volumes, client-side proprietary voice stacks restrict Twilio's exposure to lower-margin PSTN connectivity, limiting its ability to capture lucrative software revenue.
- CPaaS Commoditization and Customer Disintermediation: Rival communications platform providers like Bandwidth and Sinch offer direct network alternatives, while major tech clients retain the capability to bypass Twilio by connecting directly to wholesale carriers via SIP, creating fee compression risks.
- Persistent Net Insider Dispositions: SEC equity transaction disclosures reveal continuous net insider selling totaling over $130 million in recent months without any open-market insider share acquisitions, reflecting reduced insider confidence following the stock's sharp rally.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.