


SAP SE Stock (SAP) Moved Up by 4.79% on Sep 14: What Investors Need To Know



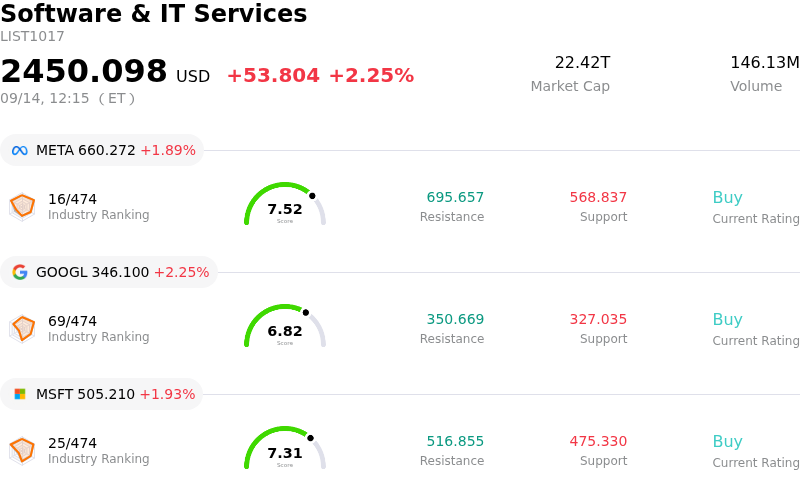
SAP SE (SAP) moved up by 4.79%. The Software & IT Services sector is up by 2.25%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Meta Platforms Inc (META) up 1.89%; Alphabet Inc Class A (GOOGL) up 2.19%; Microsoft Corp (MSFT) up 1.90%.
What is driving SAP SE (SAP)’s stock price up today?
Enterprise software giant SAP experienced a strong upward move driven by major enterprise customer wins and renewed institutional confidence in its cloud and artificial intelligence roadmap. Key market catalysts included the announcement of a large-scale global workforce technology contract with NTT DATA, which chose SAP SuccessFactors, Business Data Cloud, and the proprietary AI copilot Joule for its global operations. This high-profile win provided clear evidence of accelerating enterprise demand for SAP's next-generation SaaS ecosystem and AI integration, reassuring investors who had been closely watching the timeline for enterprise AI monetization.
The rally was further fueled by positive analyst coverage and active corporate capital allocation. Major Wall Street research firms, including Argus Research and Goldman Sachs, reaffirmed bullish ratings and high price targets on the company, emphasizing its deeply entrenched competitive moat and long-term cloud backlog potential. Additionally, market sentiment benefited from SAP's disclosure of ongoing aggressive share repurchases under its corporate buyback program. These buybacks continue to provide baseline demand for the stock while demonstrating management's confidence in intrinsic valuation despite recent broader software sector volatility.
From a macroeconomic perspective, broader technology shares gained traction as investors positioned for upcoming Federal Reserve policy decisions, driving renewed risk appetite toward resilient high-margin cloud platforms. CEO Christian Klein’s recent reaffirmations regarding SAP’s cloud migration pipeline underscored that roughly sixty percent of the legacy installed customer base has yet to transition to the cloud, representing a substantial long-term growth runway. Despite temporary margin digestion from recent niche AI acquisitions, the convergence of strong enterprise contract momentum, institutional backing, and sustained share repurchases generated substantial buying momentum during the session.
Technical Analysis of SAP SE (SAP)
Technically, SAP SE (SAP) shows a MACD (12,26,9) value of -4.512, indicating a neutral signal. The RSI at 59.092 suggests neutral condition and the Williams %R at 36.031 suggests buy condition. Please monitor closely.
Fundamental Analysis of SAP SE (SAP)
SAP SE (SAP) is in the Software & IT Services industry. Its latest annual revenue is $41.49B, ranking 14 in the industry. The net profit is $8.07B, ranking 13 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $259.59, a high of $367.98, and a low of $177.00.
More details about SAP SE (SAP)
Company Specific Risks:
- Critical Cybersecurity Vulnerabilities: Disclosure of maximum-severity security flaws (CVSS 10.0), including the OVERPASS kernel memory corruption (CVE-2026-44756) and NetWeaver authentication flaw (CVE-2026-58240), exposes enterprise clients to unauthenticated remote code execution, creating immediate operational and compliance liabilities.
- Analyst Downgrades and Cloud Backlog Deceleration: Recent analyst downgrades, including UBS lowering SAP to Neutral, stem from institutional concerns regarding an expected slowdown in second-half cloud backlog growth and extended timelines for monetizing agentic AI capabilities.
- Near-Term Profit Margin Dilution: Profitability remains under pressure following management's trimmed 2026 operating profit guidance of €11.8B to €12.2B, driven by integration costs and short-term earnings dilution from AI acquisitions such as Dremio and Prior Labs.
- Sales Model Transition and Service Revenue Drag: The strategic shift away from traditional ERP software migrations toward usage-based AI pricing models introduces execution risk, putting near-term downward pressure on consulting and service revenues while enterprise buyers scrutinize payback periods.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Recommended Articles








Comments (0)
Click the $ button, enter the symbol, and select to link a stock, ETF, or other ticker.